Does Your Pension Die With You

So, you’ve been squirreling away cash into a pension for decades. You’ve skipped lattes, driven a clunker, and dreamed of sandy beaches. Then someone drops the big, scary ques...
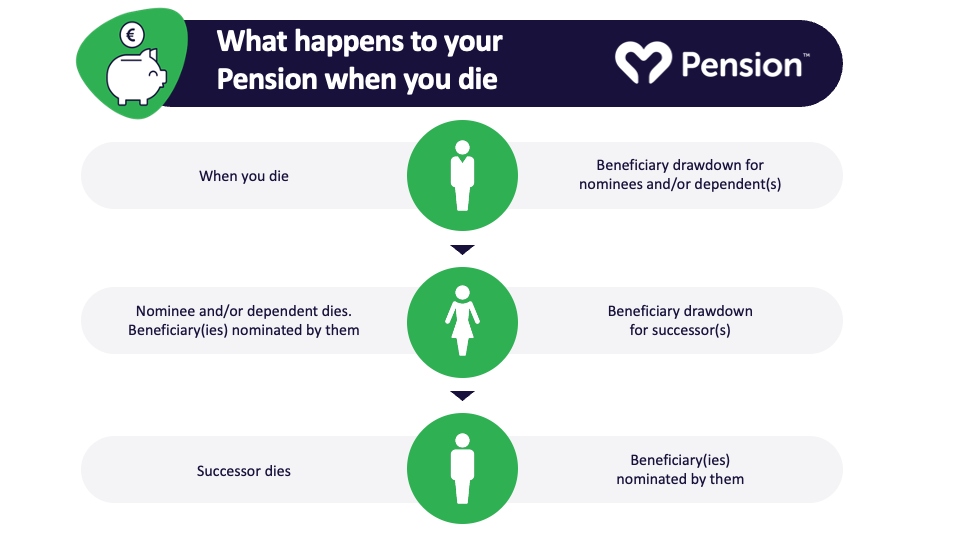
So, you’ve been squirreling away cash into a pension for decades. You’ve skipped lattes, driven a clunker, and dreamed of sandy beaches. Then someone drops the big, scary question: “Does your pension die with you?” Well, grab a cup of coffee (or that latte you missed), because we’re about to unravel this mystery together.
Let’s start with the good news: not all pensions vanish when you do. Some are designed to keep paying even after you’ve kicked the bucket—or, as I like to call it, “retired to the big golf course in the sky.” It all depends on the type of pension you have. Think of it like a pizza: some slices are for you alone, and others you can share.
The “You Alone” Pizza Slice: Defined Benefit Plans
If you’re lucky enough to have a defined benefit pension (the old-school kind from a job where your company promises a monthly payout), the rules can be tricky. Many of these plans pay you for life—but they often stop when you stop breathing. Poof! No more checks for your spouse or kids.
Unless, that is, you chose a joint-and-survivor option when you retired. That’s a fancy term that means your pension keeps paying a reduced amount to your partner after you’re gone. Think of it as a “survivor’s discount.” Your check gets smaller now, but your loved one gets a financial hug later. Just remember to read the fine print—or hire a golden retriever with a finance degree to do it for you.
The “Oops, I Forgot” Twist
Many people forget to tick that joint-and-survivor box. Then they die, and their spouse is left staring at an empty mailbox. Ouch. The lesson here? If you love someone, don’t let your pension ghost them. Talk to your HR department before you retire, and maybe buy your spouse a nice thank-you card for dealing with all this math.
The “You Can Pass It On” Slice: Defined Contribution Plans
Now let’s talk about defined contribution plans—things like 401(k)s, IRAs, or a pot of money you built yourself. This is the good stuff. You own the account, and whatever’s left when you die belongs to your beneficiary. It’s like leaving a treasure chest with a sticky note that says, “Enjoy, but I ate the chocolate first.”
 What happens to my pension when I die - National Pension Helpline
Your spouse, your kids, or even your pet iguana (if you named them as a beneficiary) can inherit this money. They can roll it into their own retirement account, take it as a lump sum, or—if they’re feeling wild—buy a lifetime supply of pickles. The key is to name a beneficiary. If you don’t, the government might step in and decide for you, and trust me, they’re terrible at choosing music for your funeral.
The “Oops, I Forgot Again” Twist (This One’s a Doozy)
If you’ve got a 401(k) but never named a beneficiary, the money might go to your estate—which means it goes through probate court. Probate is like a slow-motion car crash for your savings. It takes forever, costs money, and your loved ones will be pulling their hair out. So please, for the love of spreadsheets, fill out that beneficiary form. It takes five minutes, and it’s way easier than explaining to your ghost why your kids are crying over paperwork.
The “Government Gets It” Scenario: State Pensions
What about Social Security or a state pension? Ah, here’s the plot twist: Social Security does offer survivor benefits. Your spouse or kids might get a monthly check based on your earnings history. But it’s not automatic—they have to apply, and there are rules about age and marriage length. It’s like a bureaucratic treasure hunt, but with better odds than a lottery ticket.
State pensions vary wildly. Some are generous, some are stingy, and some are written in a language that looks like ancient runes. The rule of thumb? If your pension is tied to a government job, there’s usually something left for your family. But don’t assume—call them up. Pretend you’re ordering a pizza and casually ask, “Does this come with a death benefit?” They’ll either laugh or cry. Either way, you’ll get an answer.
 What Happens To Your Private Pension When You Die? 2026 Guide
The Ultimate Cheat Sheet
Here’s the one-sentence summary: Your pension dies with you only if you pick the wrong option, forget to name a beneficiary, or work for a company that hates joy. Otherwise, you can leave a financial legacy that makes your family say, “Wow, Aunt Carol really thought of everything!”
Pro tip: Don’t procrastinate. Check your pension statements today. If you can’t find them, pretend you’re a detective in a TV show. Cue dramatic music. Then call your plan administrator and ask, “What happens to my money when I become a ghost?” They’ll be impressed by your candor.
And Finally, the Uplifting Part
Here’s the beautiful truth: You can’t take your pension with you to the afterlife. (Unless you plan on living in a very expensive cloud.) But you can decide who gets the leftovers. By taking a few simple steps, you turn your pension from a “you-only” treat into a gift that keeps on giving. Your spouse can still afford Netflix. Your kids can buy a house. Your grandkids can put your photo on a wall and say, “That legend left us a pool fund.”
So go ahead—fill out that form, make a phone call, and maybe hug your pension statement. You’ve earned this peace of mind. And when you’re finally sipping cocktails on a beach in Bermuda (or just napping on your couch), you can smile, knowing your pension will live on—because you planned ahead like the rockstar you are. Cheers to that, my friend. Now go eat a cookie; you deserve it.
