How Many Years Of Ni For Full State Pension

Right, let’s talk about the state pension—specifically, how many years of National Insurance (NI) you need to get the full whack. It’s one of those grown-up questions that fee...
Right, let’s talk about the state pension—specifically, how many years of National Insurance (NI) you need to get the full whack. It’s one of those grown-up questions that feels a bit like trying to read the back of a shampoo bottle while wearing foggy glasses. But don’t worry, I’ve got the comb, the bottle, and the glasses cleaned up for you.
The Magic Number: 35 Years
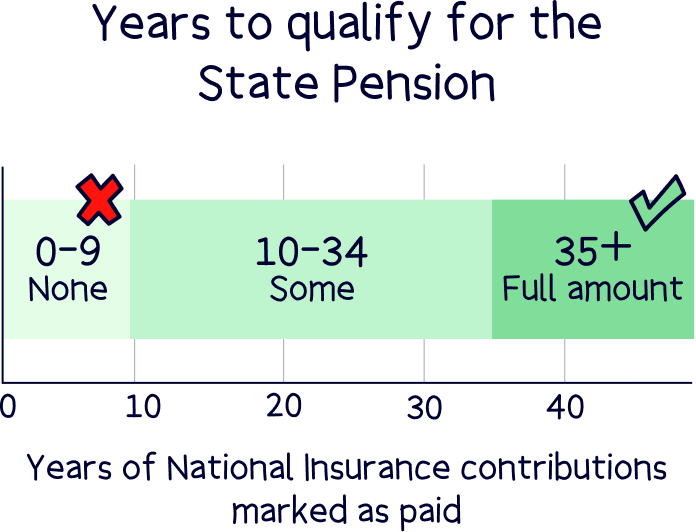
You need 35 years of NI contributions to qualify for the full new State Pension. Yes, 35—like the number of flavours at a posh ice cream shop, but with way less sprinkles and a lot more paperwork.
If you have fewer years, your pension gets trimmed down. Think of it like a pizza: 35 slices gets you the whole thing; 15 slices gets you a sad, lonely corner with a bit of cheese.
Must Read
But here’s the kicker: you don’t need to work for 35 consecutive years. You can have gaps, like that gap year you spent pretending to learn French in Provence, and it still counts—as long as you’ve got the required total.
What Counts as a ‘Year’ of NI?
A qualifying year is when you’ve paid—or been credited with—enough NI contributions. It’s like having a loyalty card for the government: 52 weeks of paying or getting credits, and you stamp your card for that year.
If you’re employed and earn over £242 a week (from one job), you automatically pay NI. Self-employed? You pay a flat rate, but you’re still in the game. Pro tip: if you earn under that threshold, you don’t pay—but you also don’t get a stamp. Bummer, I know.
But wait! There are National Insurance credits for times you’re not earning: looking after kids (Child Benefit claims), caring for a disabled person, or being on Jobseeker’s Allowance. It’s like the government saying, “We see you being a good human; here’s a free stamp.”
What If You Have Fewer Than 35 Years?
If you have between 10 and 34 years, you’ll get a partial pension. Think of it as the “budget airline” version: you still get a seat, but you might have to pay for your own peanuts.
You need at least 10 qualifying years to get any state pension at all. Below that? Nada. Zero. Zilch. The state basically says, “Thanks for playing, but your pension is a myth, like a unicorn or a quiet toddler.”
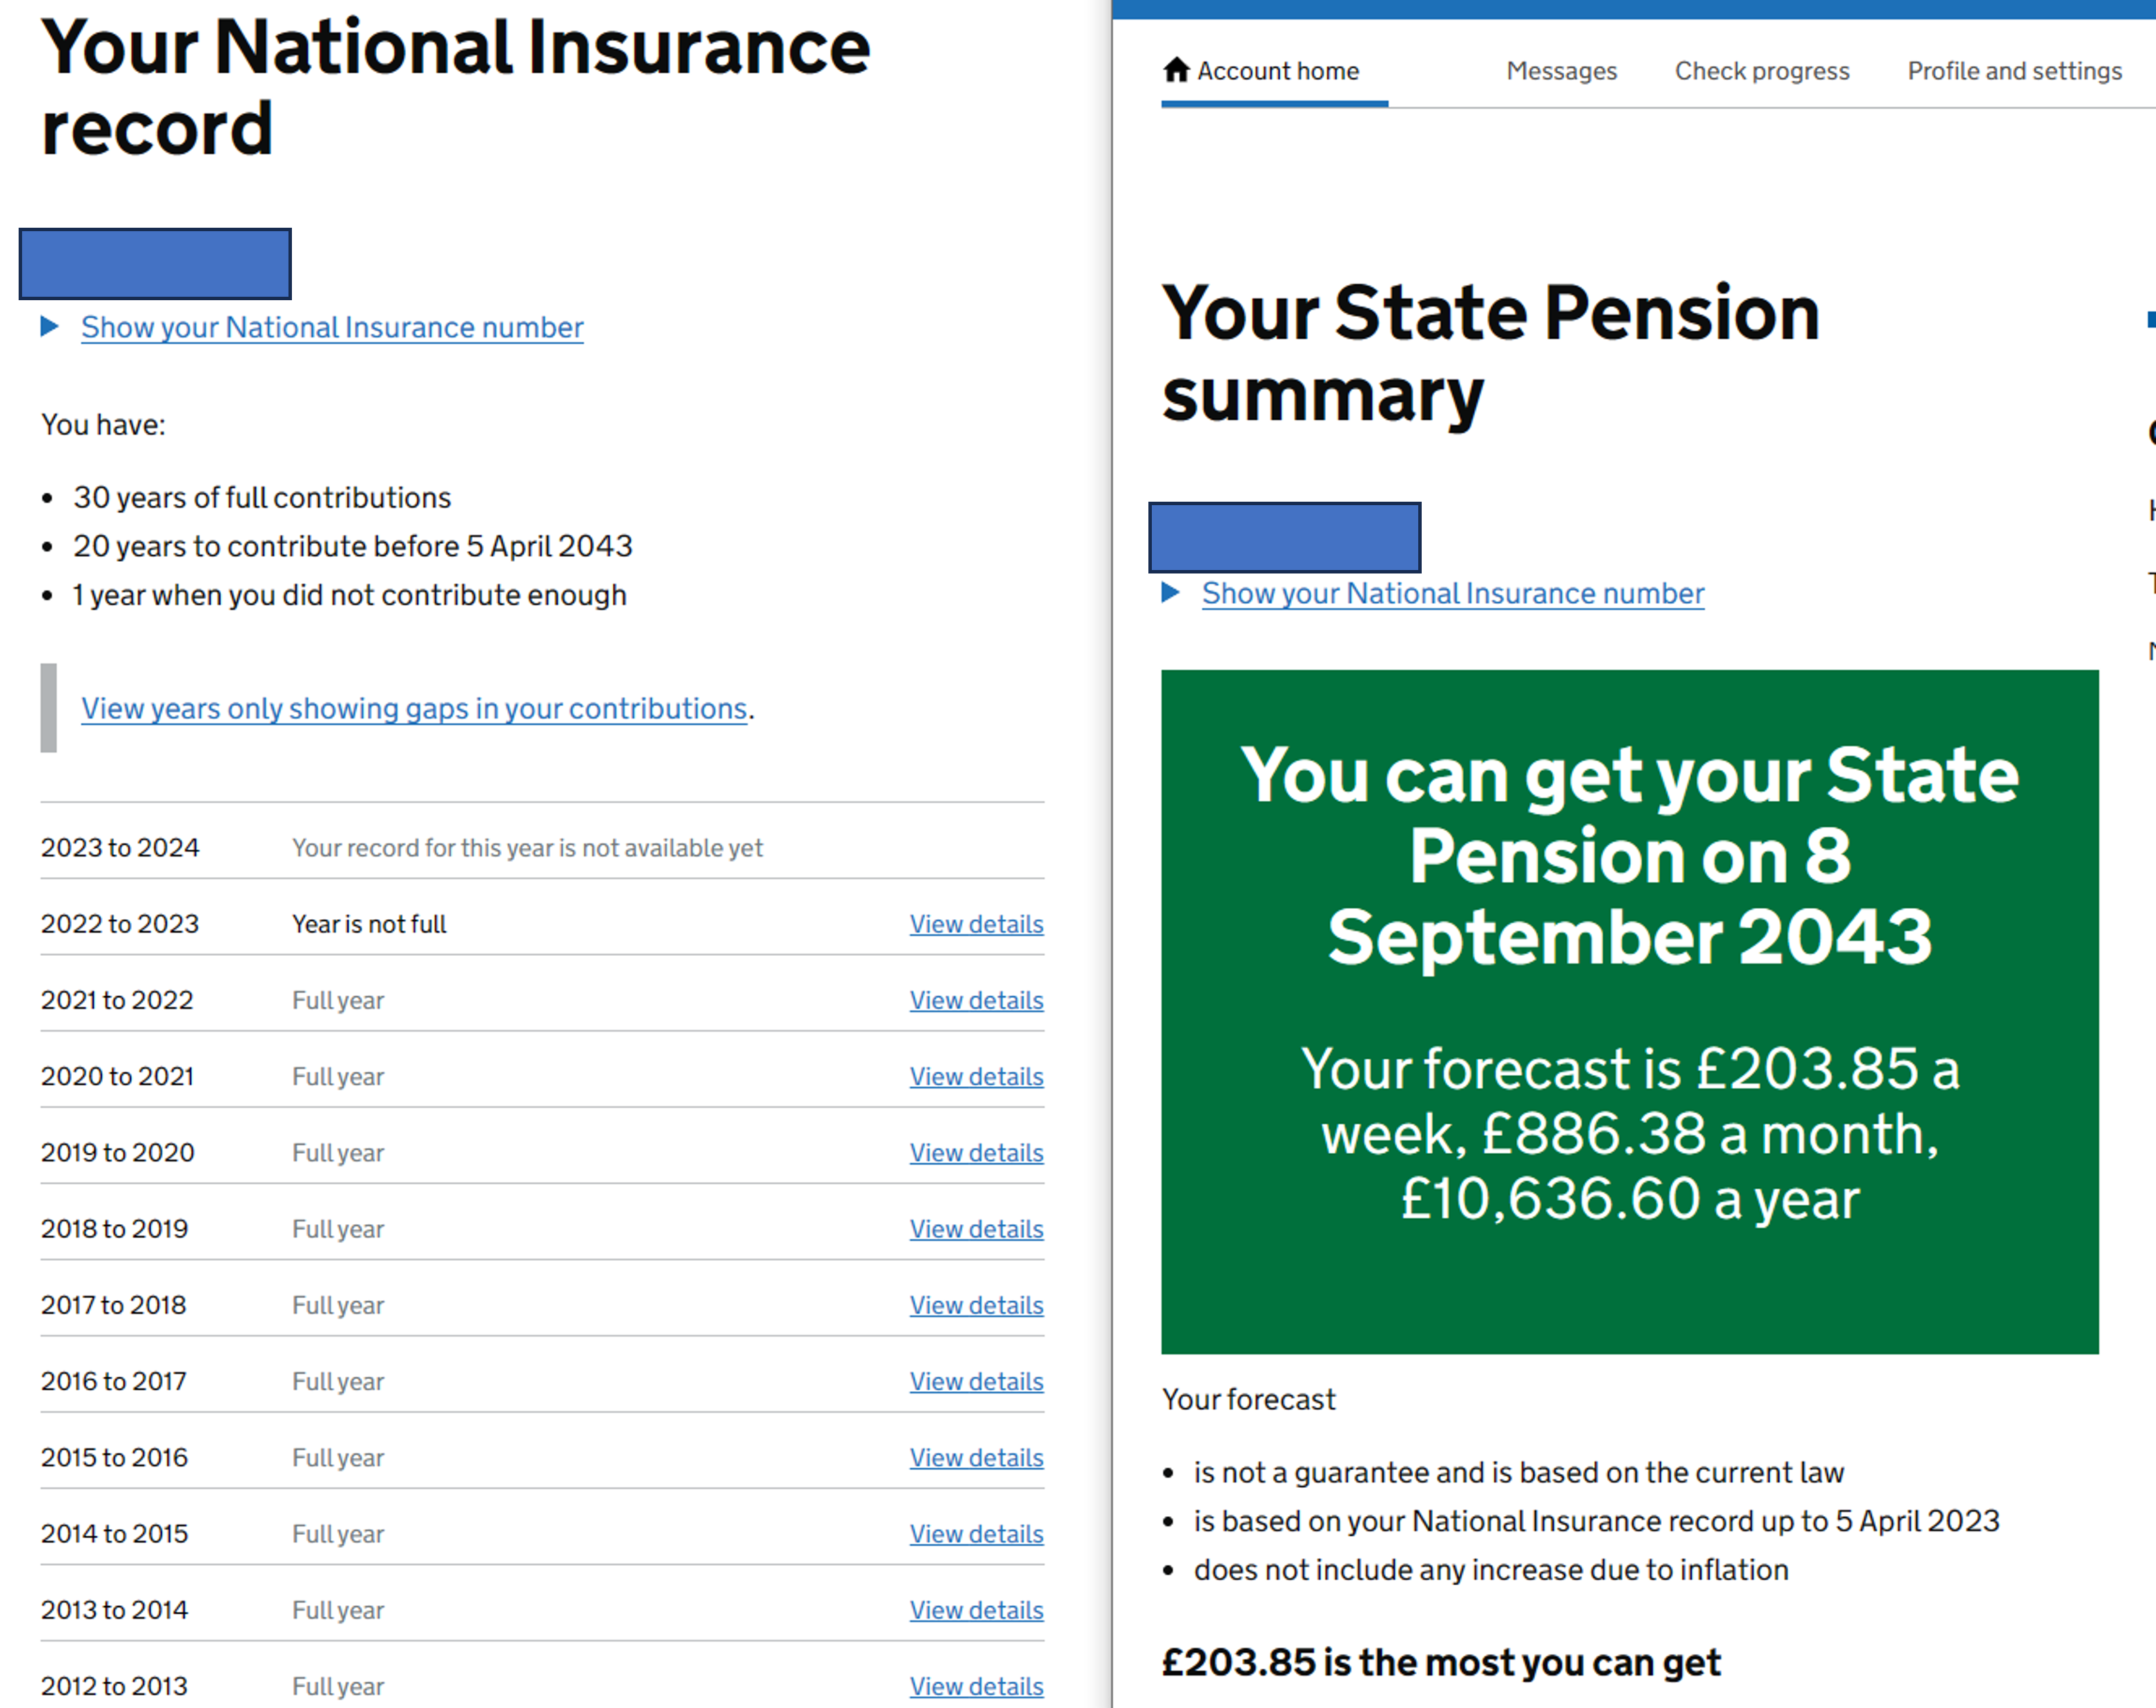 Only 30 years NI contributions but max pension already forecasted
But don’t panic—if you’re short, you can often buy extra years (called voluntary contributions). It’s like topping up your Oyster card before a long journey. You usually have a window to do this, so check online before it’s too late.
The ‘Old’ vs ‘New’ Pension Confusion
If you’re a man born before 6 April 1951, or a woman born before 6 April 1953, you’re on the old system—and you need 30 years for the full amount. That’s like the “retro edition” of the pension, with slightly different rules and possibly more wrinkles.
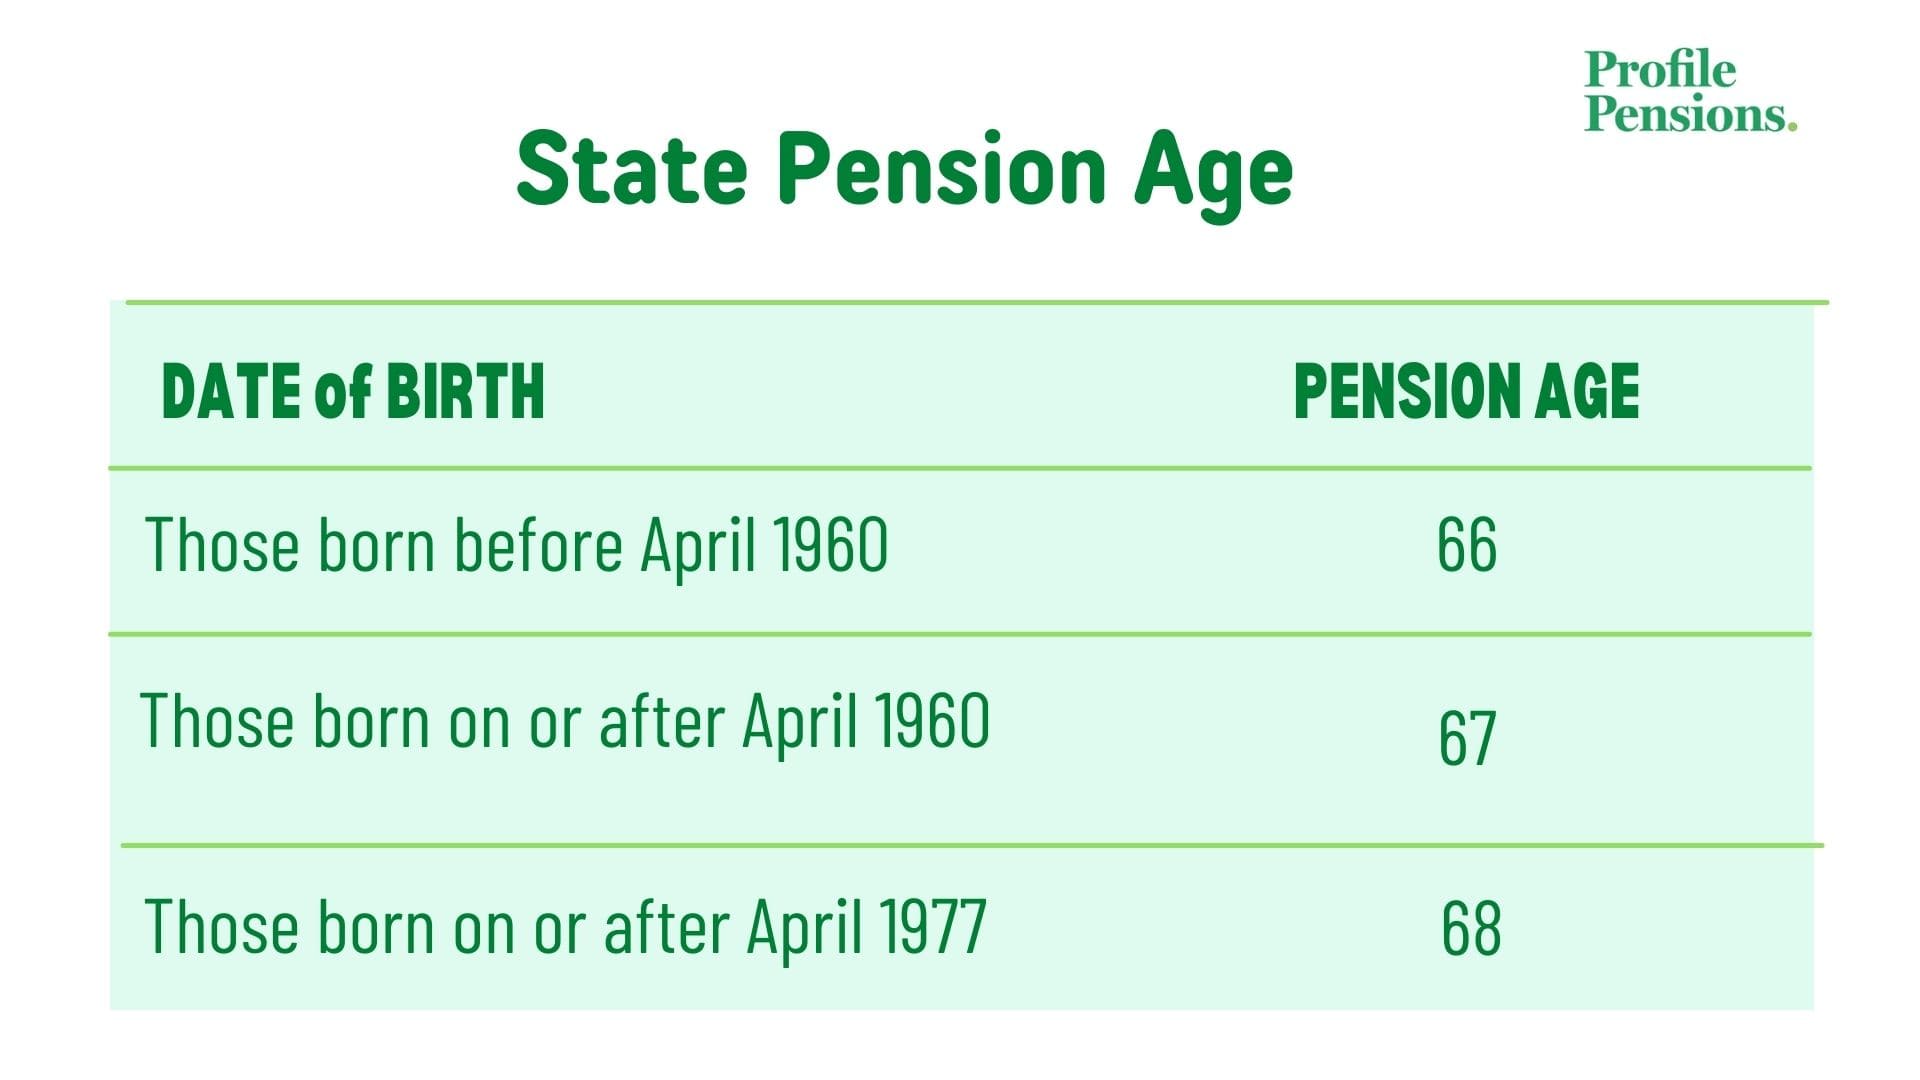
For everyone else (born after those dates), it’s the new State Pension—the one with the 35-year rule. So if you’re younger than a certain age, welcome to the club. The average age of the club is… well, let’s just say the playlist is mostly 80s hits.
One more twist: if you’ve been contracted out of the Additional State Pension (via a workplace pension), you might get a lower new State Pension. It’s like ordering a full English breakfast but being told, “Sorry, the beans are extra.” Check your National Insurance record online.
How to Check Your Progress
The easiest way is to check your State Pension forecast on the government website. It’s less scary than doing your taxes, and it involves zero spreadsheets (unless you’re into that sort of thing—no judgment).
You’ll see how many qualifying years you have so far, and how much pension you’re on track for. It’s like a video game where your health bar is money, and the boss is “retirement.”
 Pension Years For Full State Pension – RGNC
If you spot a gap, you can fill it by paying voluntary NI. The cost is around £17 a week for the current tax year (2024/25), but shop around because it changes. It’s not cheap, but it’s cheaper than a lifetime of eating bargain-bin tinned beans in your 70s.
A Playful Warning About Gaps
If you take time off to travel the world—lucky you—you might miss NI years. The state pension doesn’t care about your Instagram sunsets; it cares about stamps. So either buy voluntary contributions, or cross your fingers and hope your international jet-setting lifestyle pays off in a different way (like a wealthy Aunt Bertha leaving you a cottage in Cornwall).
And for the love of all that is holy, do not lose your National Insurance number. It’s more important than your favourite mug at work. Lose that, and you’ll be on hold with HMRC for three hours listening to a tinny version of “Greensleeves.”
The Uplifting Conclusion (Finally!)
So, to sum up: 35 years for the full story, 10 years for a teaser, and 0 years for a mysterious void. But here’s the beautiful part—you’re reading this, which means you’re already thinking ahead. You’re not the tortoise who napped through the race; you’re the one checking the map before you start running.
Yes, the system is a bit fiddly—like assembling flat-pack furniture with no instructions. But you’ve got time, you’ve got options, and you’ve got a sense of humour (you just read 800 words about National Insurance without falling asleep, so you’re basically a hero).
Go check your record, have a cuppa, and remember: retirement isn’t the end of the party. It’s the bit where you finally get to dance without worrying about the mortgage. And with those 35 years under your belt, you’ll have the music, the snacks, and enough cash to buy the good cheese. You’ve got this.
