Rv Financing Credit Score

Let’s be honest: dreaming about an RV is easy. You picture yourself sipping coffee in a national park, wearing novelty socks, and pretending you’re a rugged explorer. It’s the...
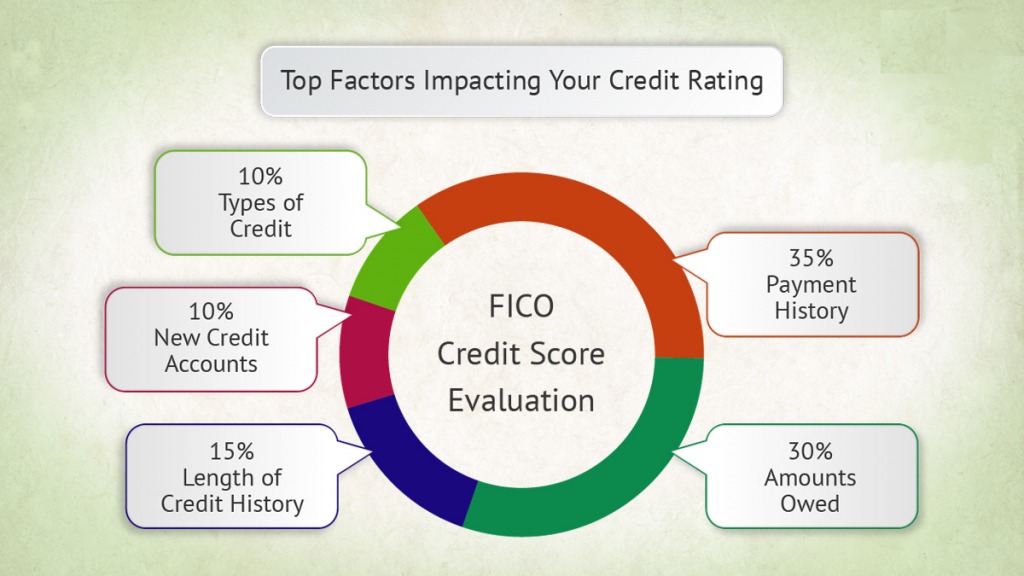
Let’s be honest: dreaming about an RV is easy. You picture yourself sipping coffee in a national park, wearing novelty socks, and pretending you’re a rugged explorer. It’s the reality of financing that hits like a pothole on a dirt road.
Nobody wakes up excited to talk about credit scores. It’s like planning a root canal, but with more paperwork. Yet, here we are—because that three-digit number is the gatekeeper to your rolling castle.
The Credit Score Circus
Your credit score is basically a report card for your adulting skills. Remember that time you forgot to pay a library fine? The credit bureaus remember. They’re like that nosy neighbor who logs every time you bring takeout home.
Must Read
When you walk into an RV dealership, your score either gets you a parade or a pity party. A good credit score (think 740 and above) makes you feel like a financial rockstar. A low one? You’ll get interest rates that feel like you’re borrowing money from a loan shark named “Vinnie the Calculator.”
I once met a guy who tried to finance a used RV with a score of 580. The dealer offered him a 23% APR. That’s not a loan; that’s a financial hostage situation.
The Cash Flow Reality
Here’s the thing: RV lenders don’t care if you have a dream. They care if you have income and a history of paying bills. It’s like trying to borrow your buddy’s lawnmower only if you promise to return it with gas still in it.
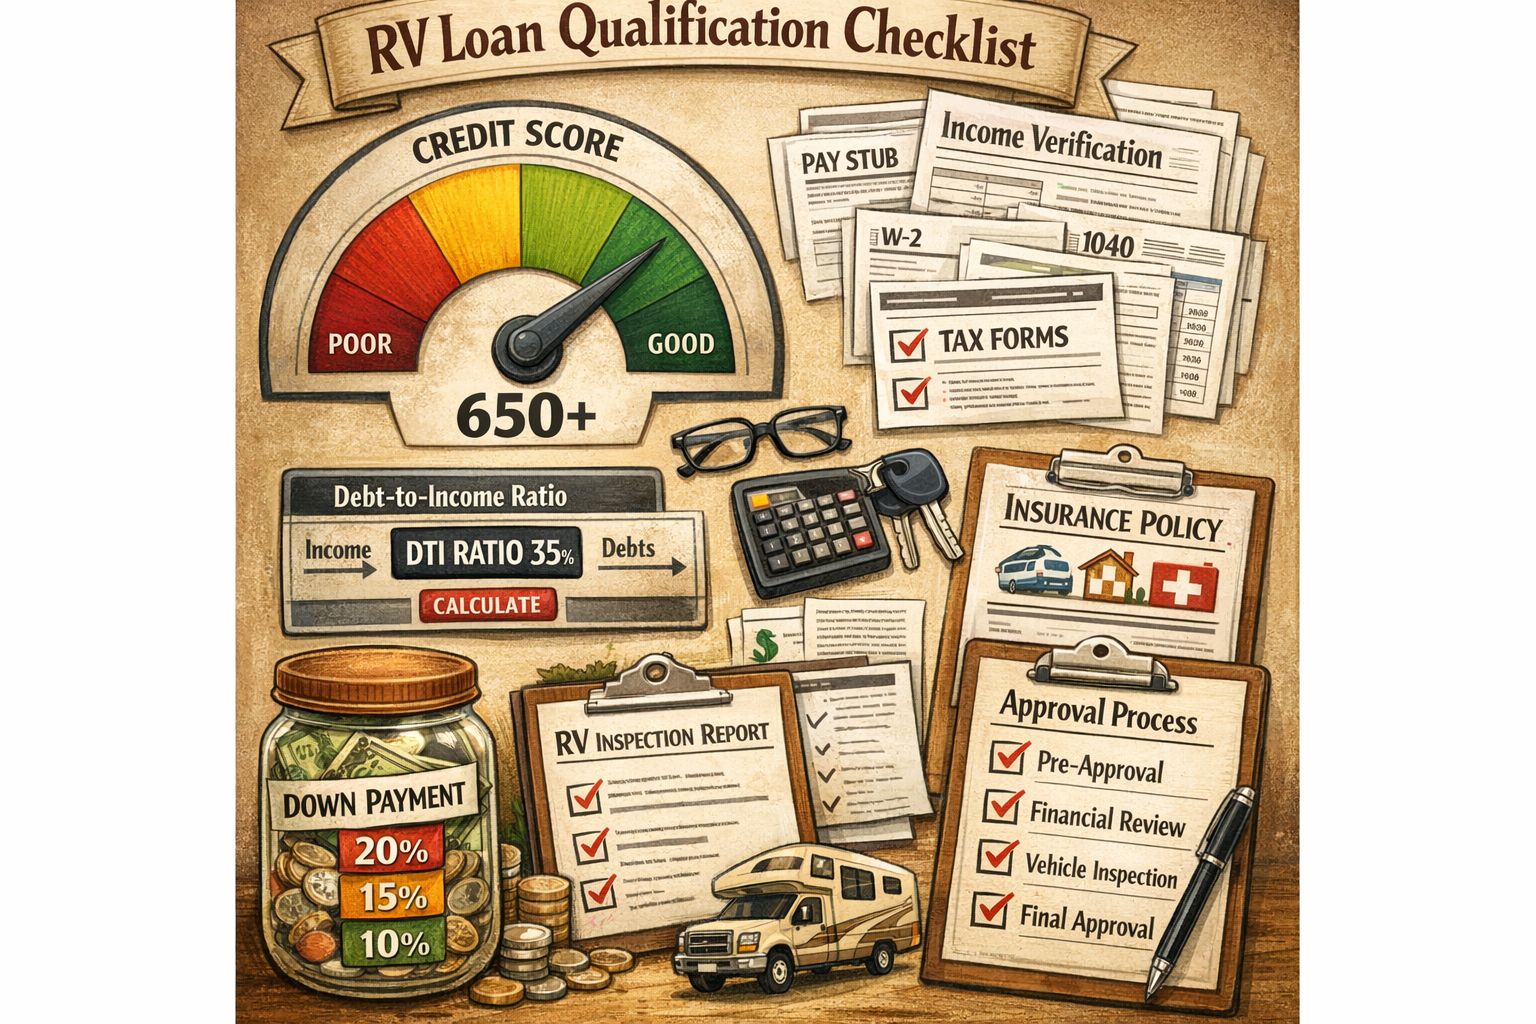
Your debt-to-income ratio is just as important. If you already spend half your paycheck on avocado toast and subscriptions you forgot about, the lender will sidestep you like a puddle. They want to see that your RV payment won’t make you eat ramen for a decade.
And let’s not pretend you’ll rent out the RV on weekends to cover costs. That’s like saying you’ll buy a treadmill and use it as a clothes hanger—we all know how that ends.
 Can You Get a Mortgage on an RV? Complete 2026 Financing Gu
Improving Your Score Without Losing Your Sanity
So you’ve got a score that’s “mediocre” at best. Don’t panic. You can fix it, but it takes time—like growing a beard or waiting for a slow Wi-Fi signal.
Start by paying your bills on time. That’s the golden rule. One late payment on your credit card is like showing up to a job interview in your pajamas. It’s a red flag, even if you’re qualified.
Also, don’t max out your credit cards. Lenders like to see you use about 30% of your available credit. If you’re using 90%, they think you’re one impulse buy away from applying for a clown college loan. Keep it low, and your score will thank you.
And whatever you do, don’t apply for a dozen credit cards in one week. That’s like speed-dating all the credit bureaus—they’ll compare notes, and you’ll look desperate. Pace yourself.
The Pre-Approval Dance
Before you fall in love with a shiny RV, get pre-approved. It’s like test-driving a car before promising to marry it. You’ll know exactly what you can afford, and you won’t get emotionally ambushed by a $600 monthly payment.
 Low Credit Score Rv Loans at Daniel Mcbryde blog
Dealerships love pre-approvals because it means you’re serious. Without one, you’re just a tourist with a dream and a cup of gas station coffee. They’ll show you the expensive models first, hoping you’ll cave and sign a 10-year loan with a payment that makes your wallet weep.
Pro tip: walk away if the monthly payment feels tight. Your future self will high-five you from a budget-friendly campsite.
The Funny Truth About RV Life
I know a couple who financed a $90,000 motorhome with a 720 credit score. They got a 5% APR and acted like they’d won the lottery. Then they spent the first trip stuck behind a slow truck, arguing about whether the GPS was wrong.
That’s the crux of it: the credit score gets you the RV, but it doesn’t buy you the experience. You’ll still have to fix a leaky faucet at 2 a.m. while mosquitoes treat you like a buffet. But you’ll do it in style—from your very own, financed-on-good-credit, home-on-wheels.
So, check your score. Pay down that credit card. And remember: even if your score is currently lower than your hopes, you can still get there. It just takes patience, discipline, and maybe a little prayer to the finance gods.
Now go forth and dream—but bring a calculator. Your RV future is waiting, and it might just come with a decent interest rate.
