Universal Credit Ask For Bank Statements

So my mate Dave—you know the type, always has a scheme—calls me the other day, panicked. He’s been on Universal Credit for a few months after his start-up went belly-up, and h...
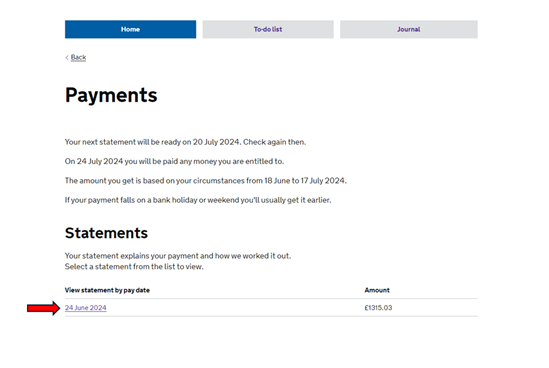
So my mate Dave—you know the type, always has a scheme—calls me the other day, panicked. He’s been on Universal Credit for a few months after his start-up went belly-up, and he gets this letter: “Please provide bank statements for the last four months.” He’s sweating bullets because, between you and me, he’d been doing a little cash-in-hand work for his cousin’s roofing company. “They’re gonna see the deposits,” he whispers, like he’s in a spy movie. I told him to breathe, but honestly? He’s not alone. That letter is landing in a lot of mailboxes right now, and it feels like getting called to the headmaster’s office.
Let’s be real: Universal Credit asking for your bank statements feels invasive, like they’re peeking into your sock drawer. But here’s the twist—it’s not always about catching you out. The Department for Work and Pensions (DWP) has been ramping up these requests as part of something called “Administrative Earnings Threshold.” Fancy term, I know. Basically, if your earnings fluctuate or you’ve reported a change, they want to cross-check. They’re looking for consistency, not a crime scene.
Why the sudden interest in your checking account?
Think of it this way: the system is dumb. Not malicious, just dumb. It relies on you reporting your income manually each month, and let’s face it, we’re all human—you might forget a shift, or round down a payment by a tenner. The DWP uses bank statements to verify what you told them matches what actually landed in your account. Ironically, it’s the same reason your mum asks to see your receipt after you “estimated” the grocery bill. If you’re consistently honest, it’s just a bureaucratic shuffle.
Must Read
But here’s where it gets spicy. They don’t just want a peek; they want all statements—savings, current accounts, even that old Monzo card you use for takeaway coffees. Side note: did you know they can request statements going back up to four years if they suspect fraud? Yeah, that’s the part that makes people’s stomachs drop. Don’t panic yet, though—most requests are for the last two to four months, just to “confirm your circumstances.”
The “gotcha” moments you need to know about
I’ll level with you: if you’ve been doing Dave-level dodgy stuff—like undeclared cash jobs or large deposits from a “mate”—this request is a minefield. But the DWP isn’t Sherlock Holmes. They’re looking for patterns: regular payments that look like wages, or sudden lump sums that exceed your declared capital. So if your Auntie Betty sent you £200 for your birthday, you’re fine. But if you’re getting £500 every Friday from “Bob’s Handyman Services” and you haven’t reported it? That’s a flag. And yes, they can see the transaction descriptions—so “Cash” or “Loan from mum” might get a second look.
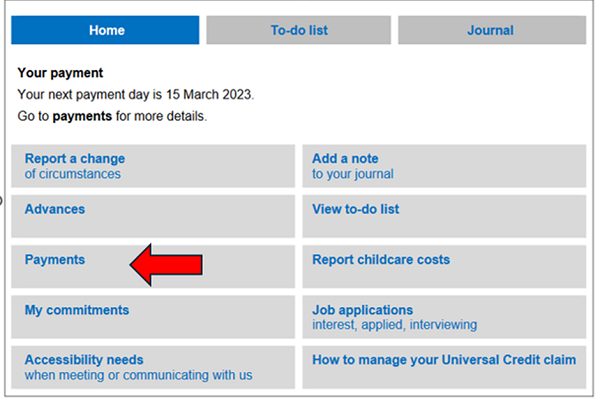 Getting claim information and statements from your online universal
What really gets me is the irony: the system is designed to catch cheats, but it mostly stresses out people who are just bad at paperwork. I know a single mum who had to send 27 pages of statements because she uses multiple apps for budgeting. The DWP didn’t find fraud—they found a woman who likes spreadsheets. She still had a panic attack. The moral? You’re not being targeted, but the process is designed to make you feel like you are.
How to survive the bank statement request (without losing your mind)
First, don’t ignore it. I know—shock, right? But people do. They hope the letter will self-destruct. It won’t. If you miss the deadline, they can stop your payments until you comply. That’s not a threat; it’s a fact. So grit your teeth and log into your online banking. You can usually download PDFs for each month. Pro tip: use a black marker to redact irrelevant stuff—like that subscription to “Desperate Cat Ladies Monthly.” The DWP only needs to see income, savings, and big deposits. They don’t need to know you spent £15 on avocado toast.
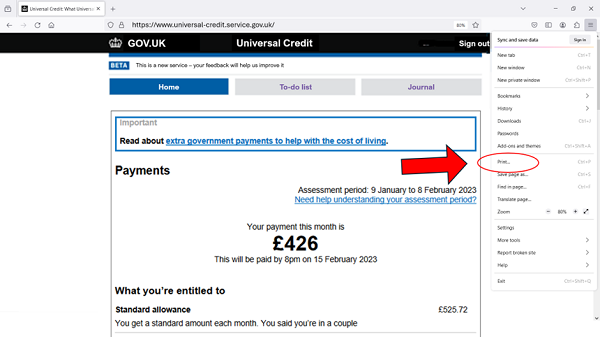 Getting statements from your online universal credit account | CPAG
Second, if you’re worried about a specific transaction—say, a one-off £300 from a freelance gig you forgot to report—don’t try to hide it. Explain it in the comment box on your Universal Credit journal. Write something boring like, “Gift from family member for car repairs.” The DWP is more likely to accept a boring lie than a suspicious hole. But honestly? If it’s undeclared income, you might need to update your earnings report first. That’s the grown-up move.
Lastly, remember that the entire system is built on trust but verify. The caseworkers are overworked and underpaid. They’re not scanning your statements for fun; they’re ticking boxes. You can even request a “welfare rights interview” if you feel overwhelmed—it’s free and anonymous. So take a breath. Dave ended up sending his statements, and guess what? They didn’t even question the roofing deposits. He’d stayed under the £2,500 threshold for “permitted work.” He got lucky. But you don’t have to rely on luck—just transparency and a bit of common sense.
