Va Investment Property Loan

Imagine this: You’re scrolling through Zillow on a lazy Sunday, half-watching a true-crime doc, and you spot a duplex that practically winks at you. The mortgage on your own h...
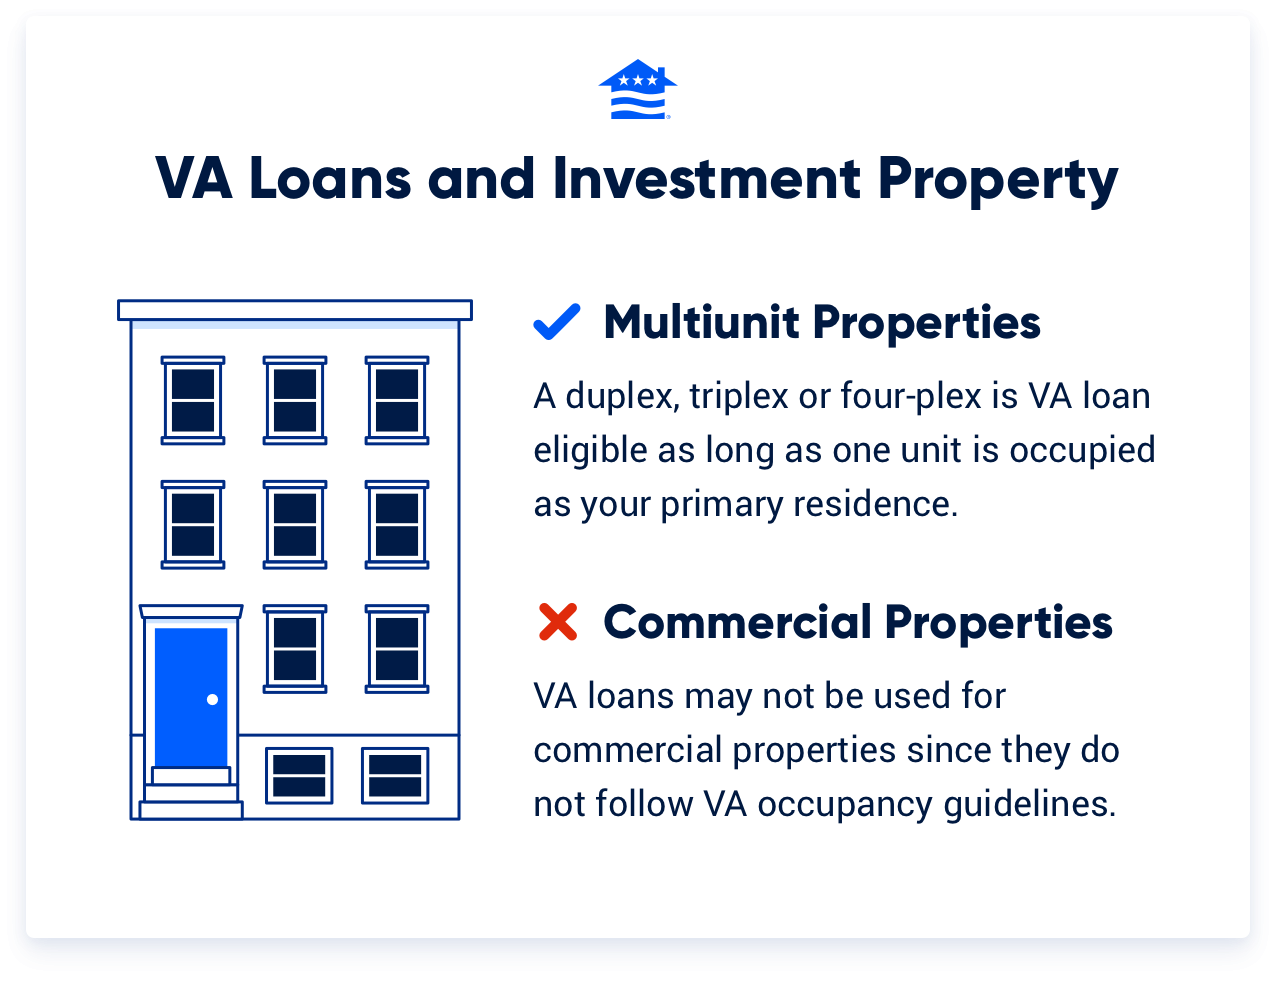
Imagine this: You’re scrolling through Zillow on a lazy Sunday, half-watching a true-crime doc, and you spot a duplex that practically winks at you. The mortgage on your own home is already a mood, but that investment property? It feels like the financial freedom you’ve been chasing—the kind you see influencers post about from Bali. Enter the VA Investment Property Loan, a tool that sounds like a unicorn but is actually just hard to get, not impossible.
First, let’s bust the biggest myth: Yes, the VA loan can be used for an investment property, but not in the way you’d use a conventional mortgage. The VA’s golden rule is that the property must be your primary residence at the time of purchase. But here’s the hack: you can buy a multi-unit property (like a duplex, triplex, or fourplex), live in one unit, and rent out the others. It’s called house hacking, and it’s basically the cheat code for first-time investors.
Fun fact: Frank Lloyd Wright designed several income-producing homes that doubled as his own living quarters. You’re channeling that same energy, minus the architectural ego. The VA lets you use your zero-down benefit on up to a four-unit building, as long as you move in within 60 days and stay for at least one year.
Why does this matter? Because real estate is still the most accessible wealth builder for middle-class families, and VA loans remove the biggest barrier: a down payment. According to the Urban Institute, veterans have a 23% higher homeownership rate than civilians, but most still don’t know they can use that same benefit to start a rental empire. The cultural reference? Think of it like Tony Stark building his first suit in a cave—you’re working with scrap parts (a zero-down loan) to create something powerful.
The Fine Print: It’s Not a Free-for-All
Here’s where the smooth jazz stops for a second. The VA requires a funding fee (2.15% for subsequent use), unless you have a service-connected disability. That fee can be rolled into the loan, but it adds to your monthly payment. Also, the property must meet Minimum Property Requirements, or MPRs—no crumbling roofs or leaky pipes. Think of it as a landlord exam: the VA wants proof the unit is safe for you to live in.
Practical tip: Use a lender who specializes in VA loans for investment properties. Not all loan officers know the nuance of renting out extra units while you live in one. Ask them, “Have you closed a VA house hack in the last six months?” If they hesitate, run. You want someone who treats the VA like a scalpel, not a hammer.
Another fun fact: The VA doesn’t limit how many units you can own, just how many you can use this benefit for simultaneously. You can have multiple VA loans for investment properties, as long as you’ve restored your entitlement (usually by selling the first property or paying off the loan). It’s like a loyalty card for veterans—except instead of getting a free coffee, you get a passive income stream.
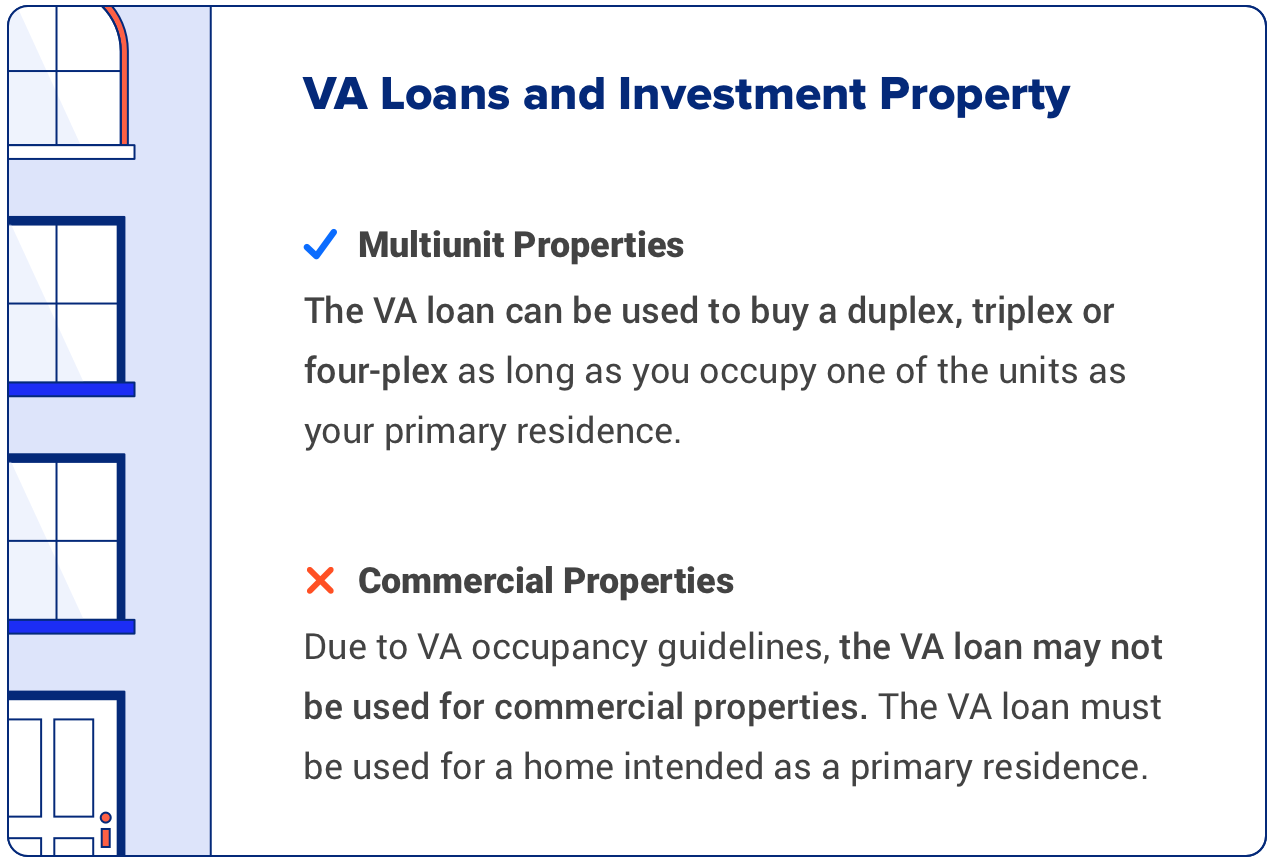 Can You Use Va Loan For Investment Property? - Get Money Saving
Making It Work in the Real World
Let’s talk numbers. In 2024, the average rental income for a two-bedroom unit in a duplex in a mid-tier city like Richmond, VA, is about $1,500 per month. If your mortgage (with zero down, at 6.5% interest) is $2,800 for the whole building, and you live in one unit, the other two units could cover $3,000. That’s negative rent for you—you’re living for free while building equity. It’s the financial equivalent of ordering a pizza and getting a free dessert because the app glitched.
Cultural reference time: Remember the scene in The Social Network where Mark Zuckerberg says, “A million dollars isn’t cool. You know what’s cool? A billion dollars.” You don’t need a billion. You just need one tenant who pays on time. Consistency beats big swings in real estate.
Biggest caution: Don’t overleverage yourself. The VA loan’s zero-down feature is seductive, but your debt-to-income ratio still matters. Lenders usually cap it at 41% for VA loans. That means your new mortgage plus existing debts (car, student loans, credit cards) can’t exceed 41% of your gross income. Punch those numbers on a napkin before you get starry-eyed.
Why Bother? The Lifestyle Angle
Real estate investment, especially via VA, isn’t just about money—it’s about time. Imagine a Friday morning where you’re not rushing to a 9-to-5 because your rental income covers your coffee and internet bill. That’s the slow-motion, morning-light version of freedom. It’s less “Wolf of Wall Street” and more “Winnie the Pooh with a 401k.”
 Hack Your VA Loan & Use it for Investment Property—Here's How
Practical tip for daily life: Automate everything. Use apps like Avail for rent collection, Stessa for tracking expenses, and a smart lock for keyless entry. Your future self will thank you when you’re at a yoga retreat and a water heater breaks—you can send a plumber remotely. The VA loan gets you the door; good systems keep you from screaming into a pillow.
Final fun fact: Thomas Edison once said, “Opportunity is missed by most people because it is dressed in overalls and looks like work.” A VA investment property loan is the overalls. It’s not glamorous paperwork, it’s a second mortgage on a fourplex in a decent neighborhood, and it’s listening to a tenant complain about a squeaky door. But that squeaky door? It’s paying for your kid’s summer camp.
Back to Your Daily Life
You’re still in your living room, maybe sipping a lukewarm latte, thinking about that fourplex. The internet is full of people selling “passive income” courses, but the VA loan is a real, tangible tool that costs you nothing to access. It’s the most patriotic leg up you didn’t know you had. Use it, don’t abuse it, and remember: every landlord started with one door.
So here’s the reflection: You don’t need to move to Bali to feel free. You just need a smart plan, a VA entitlement, and the patience to fix a garbage disposal on a Tuesday night. That, right there, is the modern American dream—not big houses, but big options. And a duplex with a tenant who pays rent on the 1st. No filter needed.
