What Age Can A Woman Get State Pension

Let’s be honest: trying to figure out the state pension age for women feels a bit like trying to assemble flat-pack furniture without the instructions. You know the goal is a...
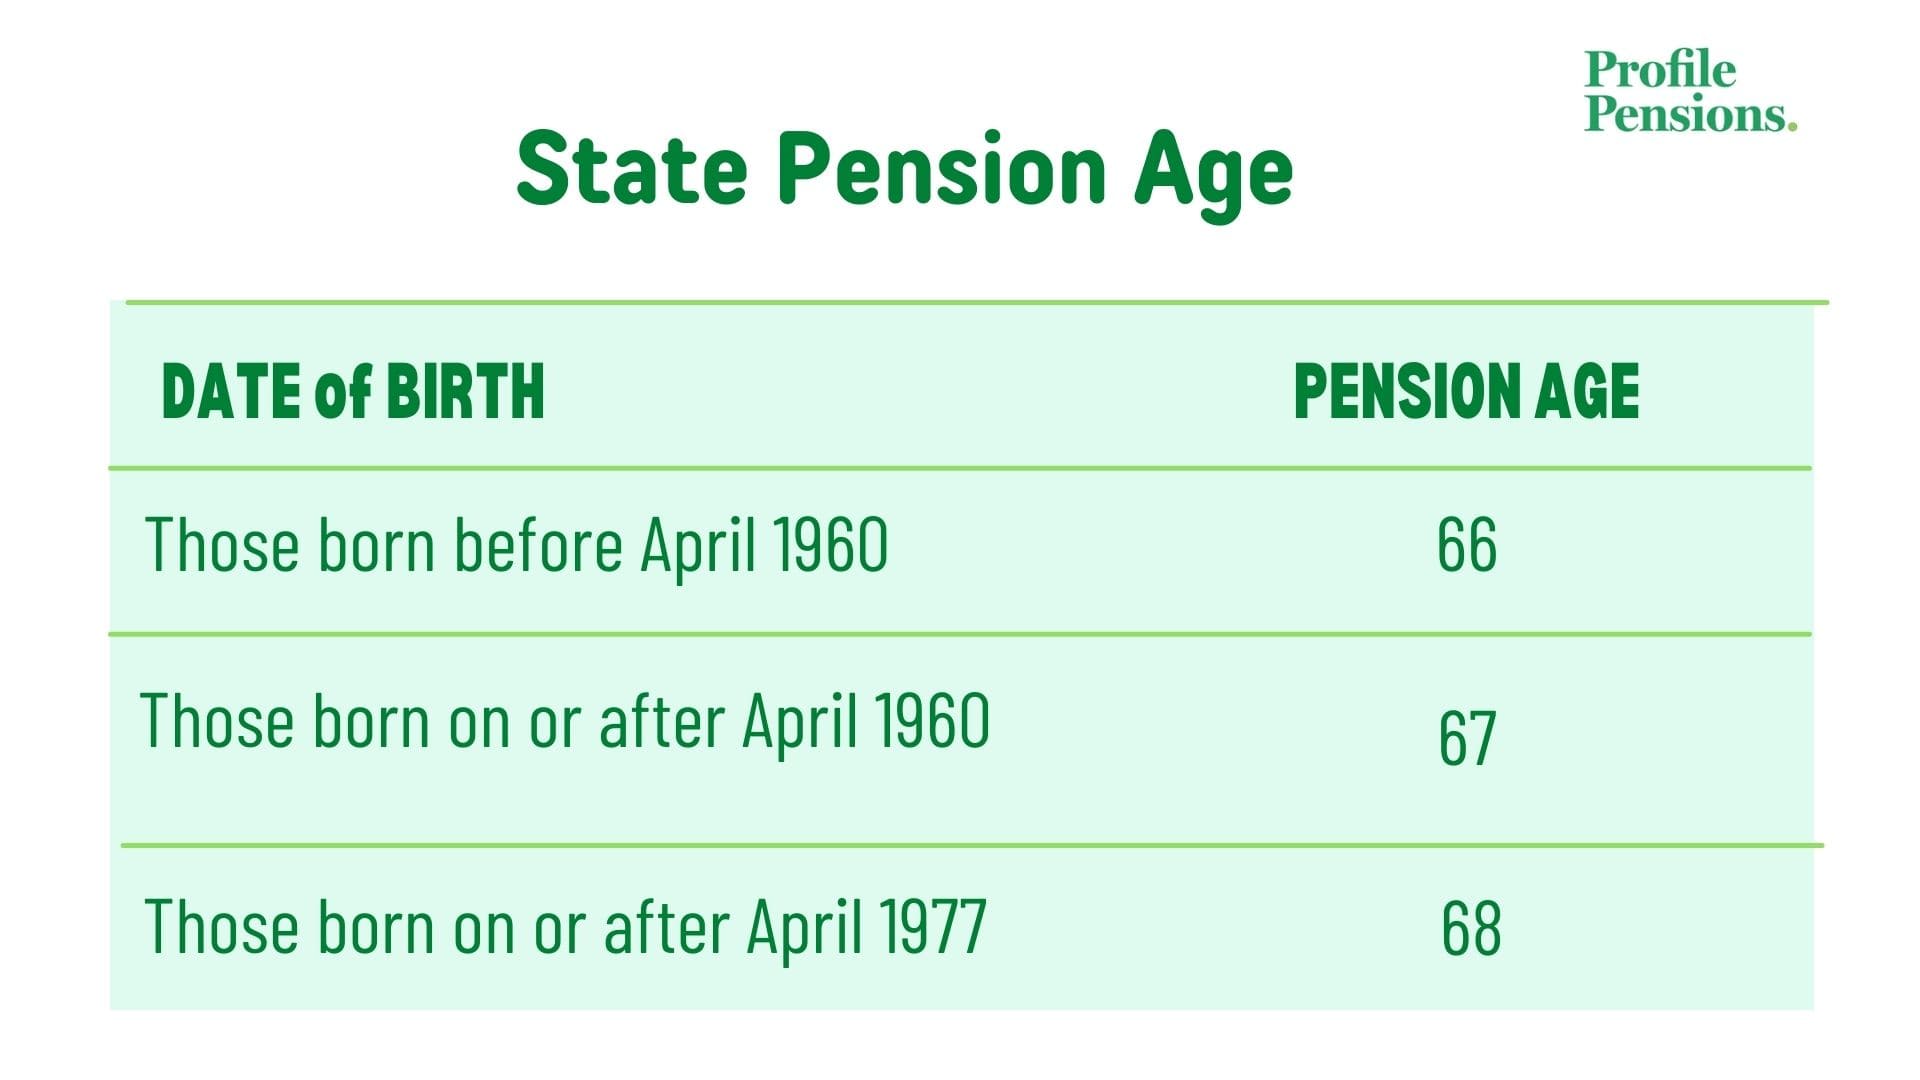
Let’s be honest: trying to figure out the state pension age for women feels a bit like trying to assemble flat-pack furniture without the instructions. You know the goal is a nice, stable retirement, but somehow you end up with a confusing pile of dates and rules. It’s enough to make you want to throw the whole thing out the window and just keep working until you’re ninety. But hey, nobody wants that, especially when your knees start making more noise than your kettle.
The short, not-so-sweet answer is that it’s not a single age anymore. Gone are the days when a woman could circle her 60th birthday on the calendar with a big, red, victory marker. That was the golden era, the time of “free bus pass and a cup of tea.” Now, that age has been moving like a teenage curfew after a bad report card. It’s been creeping up, year by year, leaving many women feeling like they’re stuck on a treadmill that keeps getting faster.
Why the change? Blame the birth certificate (and the government).
Your exact state pension age depends on a very specific piece of paper: your birth certificate. It’s like the universe decided to play a cruel trick based on which decade you were born in. If you were born in the early 1950s, you might have been expecting the magic number 60. Surprise! The finish line got moved while you were busy raising kids or paying off a mortgage. It feels a bit like training for a 5K race, then being told on race day it’s actually a half-marathon.
Must Read
For women born after April 1950, the state pension age started a slow, painful climb. It leveled out at 65 for a while, matching the old male retirement age. Then, just when you thought you could catch your breath, the government decided to shuffle the deck again. Now, for most women born after 1960, the chase is on for 66, and it’s climbing toward 67 for many. It’s the only time in your life you’ll hope to be a bit older than you actually are.
The “check your date” anxiety attack.
This leads to a very specific type of stress I call the “what year was I born again?” panic. You’ll find yourself googling “state pension age calculator” at 2 AM, feeling like you’re cracking a secret code. You type in your birthday, and the website spits out a date that feels like it belongs to your grandchild’s generation. You blink, refresh the page, and pray it was a glitch. Spoiler: it usually isn’t a glitch.
It’s a bit like discovering your favorite childhood candy now costs ten times more and comes in a smaller wrapper. The product is the same, but the deal has definitely gotten worse. You’re left wondering if you should start stockpiling cat food and tinned beans now, just to be safe.
 Full State Pension Years – Basic State Pension Calculator – QRBENE
The practical guide (with less screaming).
So, to put it in plain English: If you were born between 6 April 1970 and 5 April 1978, your state pension age is already 67. Yes, you read that right. You’ll be getting your pension card around the same time you’re considering your first hip replacement. For those born after 5 April 1978, the whispers suggest it might even hit 68. It’s a moving target, and the government keeps adjusting the sights.
Don’t shoot the messenger here. I’m just the poor soul trying to explain why your dreams of retiring to a beach house have turned into a plan to crochet blankets in a small flat. The best thing you can do is visit the official government website (yes, the boring one) and use their pension calculator. It will give you a definitive answer, even if that answer makes you want to lie down for a bit.
What can you actually do? (Besides rage-baking).
First, check your National Insurance record. It’s like checking your credit score, but for your future self. If you have gaps—say, from taking time off to raise children or care for a relative—you might be able to fill them with credits. It’s basically patching the holes in your retirement life raft before you set sail.
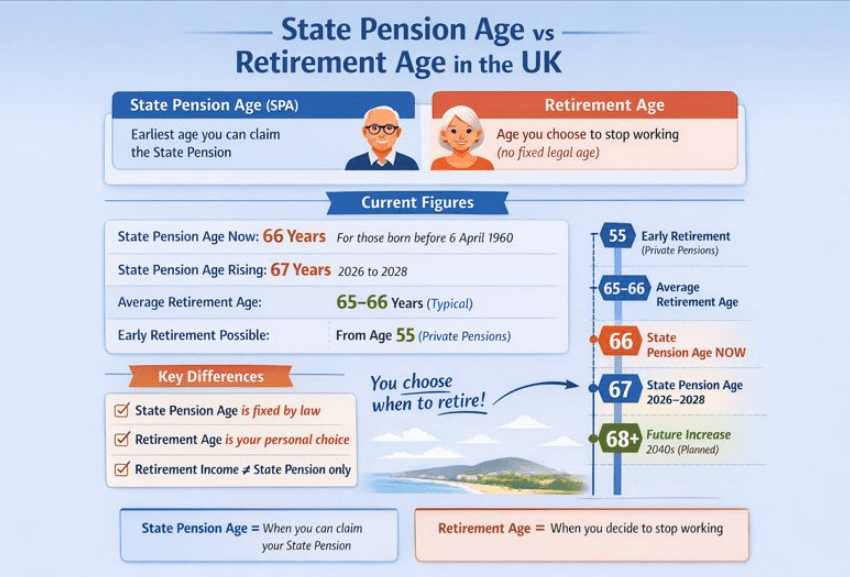 UK State Pension Age Retirement Changes & Timeline 2026
Second, start a private pension or a Lifetime ISA if you can. Think of it as a VIP pass for when the state pension queue gets too long. It’s not glamorous, but neither is eating plain pasta in your seventies. You don’t need to be a stock market wizard; just stash a little each month, like putting coins in a swear jar for the universe.
Finally, remember the triple lock rule. It’s a fancy name for the promise that the state pension will rise each year by whichever is highest: inflation, average earnings, or 2.5%. It’s the government’s way of saying, “Don’t worry, we’ll adjust the target a bit so you can still sort of see it.” It’s not perfect, but it’s better than a sharp stick in the eye.
In the end, it’s a waiting game.
Finding your state pension age feels like waiting in line for a popular ride at a theme park. You’ve been queuing for decades, the line keeps snaking, and you’re not sure if the ride will be worth it when you finally get on. But you’ve come this far, so you might as well see it through. Plus, the alternative—working forever—means you’ll never get to enjoy a Tuesday afternoon nap without guilt.
So, grab that calculator, take a deep breath, and accept the new normal. Your state pension age isn’t a secret society handshake; it’s just a number. A number that’s a bit higher than you hoped, sure. But it’s also the light at the end of a very long, very confusing tunnel. And when you finally get there, the tea will taste just as good, even if you’re now sipping it at 67 instead of 60. Cheers to that.
