What Credit Score Do You Need To Finance A Camper

So, you’ve decided to buy a camper. Maybe you dream of waking up to the sound of birds instead of your neighbor’s leaf blower. Or perhaps you just want a mobile panic room to...

So, you’ve decided to buy a camper. Maybe you dream of waking up to the sound of birds instead of your neighbor’s leaf blower. Or perhaps you just want a mobile panic room to escape your in-laws during the holidays. Either way, you’re now facing the thrilling question: what credit score do you actually need to finance this glorified tin can on wheels?
Let’s get the boring, official answer out of the way first. For a new camper, most lenders want a score of 660 or higher to get you a decent interest rate. For a used camper—which smells faintly of other people’s regrets and burnt coffee—you’ll need a 700 or better to avoid being eaten alive by the APR. Below that? You’re entering the “bless your heart” territory, where interest rates climb faster than a toddler up a jungle gym.
The Great Credit Score Camper Divide
Here’s the weird part: campers are not cars, and lenders know it. A car is a tool; a camper is a lifestyle decision that often ends up rusting in the driveway. Because of this, banks treat camper loans like unsecured personal loans with a side of suspicion. They’re terrified you’ll take the camper to a festival, live in it for a month, and then abandon it in a Walmart parking lot.
So, if your credit score is a glorious 780, congratulations! You’re the prom queen of the RV lot. You’ll get rates around 5-7% and a salesman who actually laughs at your jokes. If you’re sitting at 620, you’re in the “subprime” zone—which sounds like a cheap cut of beef, but feels like a root canal. Expect rates of 12-18%, and a monthly payment that will make you reconsider becoming a full-time tent dweller.
But wait! There’s a loophole, and it involves math that makes your high school algebra teacher cry. Your debt-to-income ratio (DTI) is often more important than your credit score. If you make six figures and your only debt is a Netflix subscription, lenders will throw money at you even if your credit score is a sad 640. They figure you’re just bad at paying bills, not stupid.
The “I Have Good Intentions” Score (600–640)
So you’re in this range? Don’t panic—yet. You’re the person who once paid a late fee on a library book and never recovered. Lenders will approve you, but they’ll do it with the enthusiasm of a dentist giving a root canal. Expect a down payment of 20-30%, which for a $30,000 camper means bringing $9,000 in cash to the table. That’s the price of a small used car—or exactly what you’d spend on therapy if you don’t take a vacation.
 BC Drive | What Credit Score Do You Need to Finance a Vehicle?
Also, the camper you can afford at this score is called a “pop-up trailer.” It’s essentially a canvas tent on a rusty frame that folds up like a sad accordion. It’ll leak in the rain, but on the bright side, you’ll become an expert in waterproofing and despair.
The “I Live Dangerously” Score (Below 600)
If your score is below 600, lenders will either laugh at you or offer you the “buy here, pay here” special. This is where you finance the camper through a dealer who charges 29% interest and installs a GPS tracker on your fridge. Miss a payment? A repo man will find you at that remote campsite and take the camper while you’re making smores. It’s not a loan; it’s a hostage situation with a mattress.
But here’s a hard truth: you don’t need a camper that bad. A 1999 Honda Odyssey with the seats folded down and a sleeping bag costs about $2,000. It has no toilet, but neither does the average campsite, so you’re really just cutting out the middleman. Plus, minivans are less likely to be stolen by raccoons.
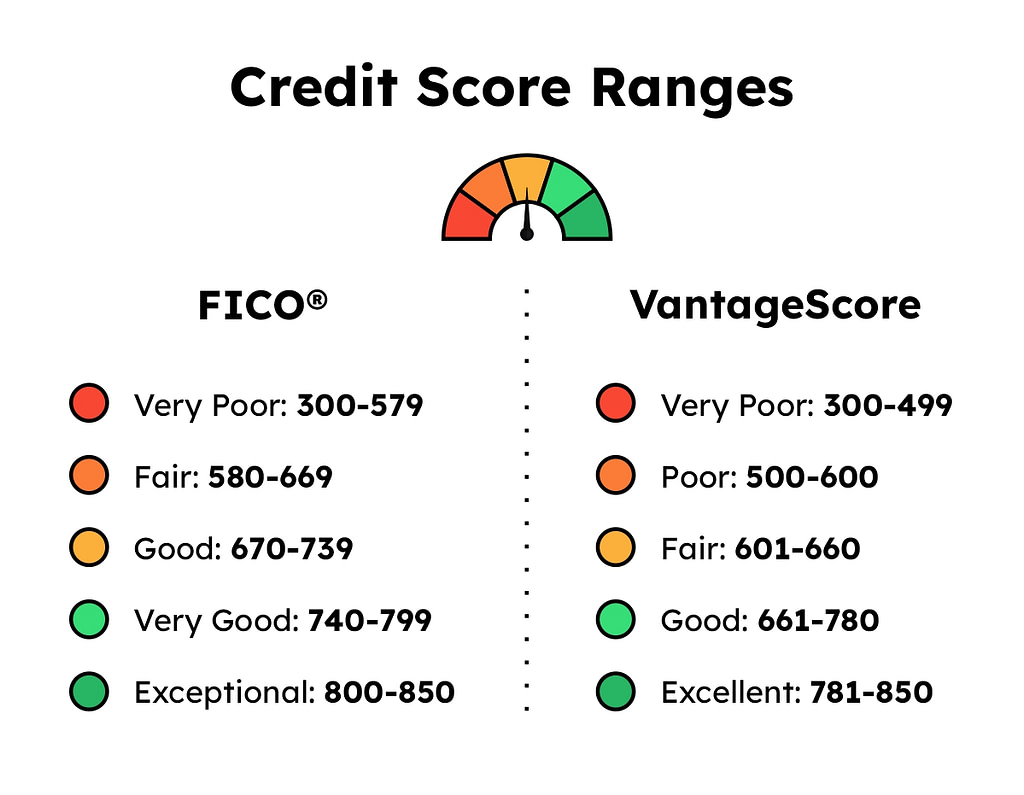 Credit Score Ranges: What They Mean and Why They Matter
The Surprising Fact That Will Save Your Wallet
Here’s the kicker: most people don’t know that campers depreciate like a rock thrown off a cliff. A new camper loses 20-30% of its value the second you tow it off the lot. That’s worse than the depreciation on a wedding dress, and at least a dress fits in your closet. So, financing a camper with a high interest rate is like buying a boat—you’ll be happy twice: the day you buy it, and the day you sell it for a tenth of what you paid.
What’s the credit score sweet spot? 720. At 720, lenders give you the “normal human” rate. You get a 6-8% interest rate with a 10-15% down payment. That’s the financial equivalent of a firm handshake and a cold beer. At 800? You’re basically a unicorn, and the dealer might throw in free camping chairs just to have you in their showroom.
How to Cheat the System (Legally)
If your credit score is mediocre, get a co-signer. Find a parent, an aunt, or that one friend who’s weirdly good at saving money. The catch? If you can’t pay, they’ll haunt your credit report forever. But hey, that’s what family reunions are for—awkward conversations and lingering financial grudges. Also, consider buying from a private seller instead of a dealer. Private sellers don’t check your credit. They just check if your cash is crisp. And you can often get a camper for half the price—just don’t ask why they’re selling it. The answer is always “our lifestyle changed,” which is code for “we hate each other now.”
In the end, the credit score you need is the one that lets you sleep at night—both physically and financially. If you have to sell a kidney to afford the payments, just buy a tent. Tents are the original campers, and they don’t require a FICO score. They only require the will to live and a can of bug spray. Happy camping, you beautiful disaster.
