What Happens To My Pension If I Die

So, my Uncle Bob—the guy who thought "retirement planning" meant buying a sailboat and hoping for the best—passed away last year. He spent decades paying into a pension, never...

So, my Uncle Bob—the guy who thought "retirement planning" meant buying a sailboat and hoping for the best—passed away last year. He spent decades paying into a pension, never really knowing what would happen to it if he didn't make it to the finish line. Turns out, his pension did a little disappearing act, and his widow was left with a fraction of what he'd earned. It wasn't malicious; it was just how the rules worked.
Let’s be real: thinking about dying and pensions is about as fun as a root canal. But if you’ve been slaving away for that golden envelope every month, you should know what happens to it when you kick the bucket. Here’s the kicker: it’s not all the same—your pension type decides who gets the cash, if anyone.
The Big Fork in the Road: Defined Benefit vs. Defined Contribution
First, figure out which basket your eggs are in. A defined benefit plan (the old-school, "I'll pay you a monthly check forever" kind) usually has a partner option. A defined contribution plan (like a 401(k) or a pot of money you invested yourself) is more like a bank account.
Must Read
Your spouse isn’t automatically the boss of your pension. In many defined benefit plans, you have to elect a "survivor benefit" during retirement paperwork. Skip that checkbox? Your pension payments might just stop dead when you do. Ironic, right? You spend years saving for a secure future, and the future doesn't even get a goodbye note.
Spouses, Partners, and the "So Sorry" Clause
If you're married in a defined benefit plan, the law in many places (like the US with ERISA) presumes your spouse gets at least 50% of your pension after you die. But guess what? You can waive that with a signed form—and sometimes people do it without thinking. If you’re single or divorced, your pension usually just vanishes back into the employer’s pot. No second place prize.
What about a lump sum payout? If you chose to take your pension as a giant check instead of monthly payments, that whole lump sum goes to your named beneficiary. It’s like winning the lottery for your heir—unless you forgot to name one. Then it goes to probate court, where lawyers feast like vultures.
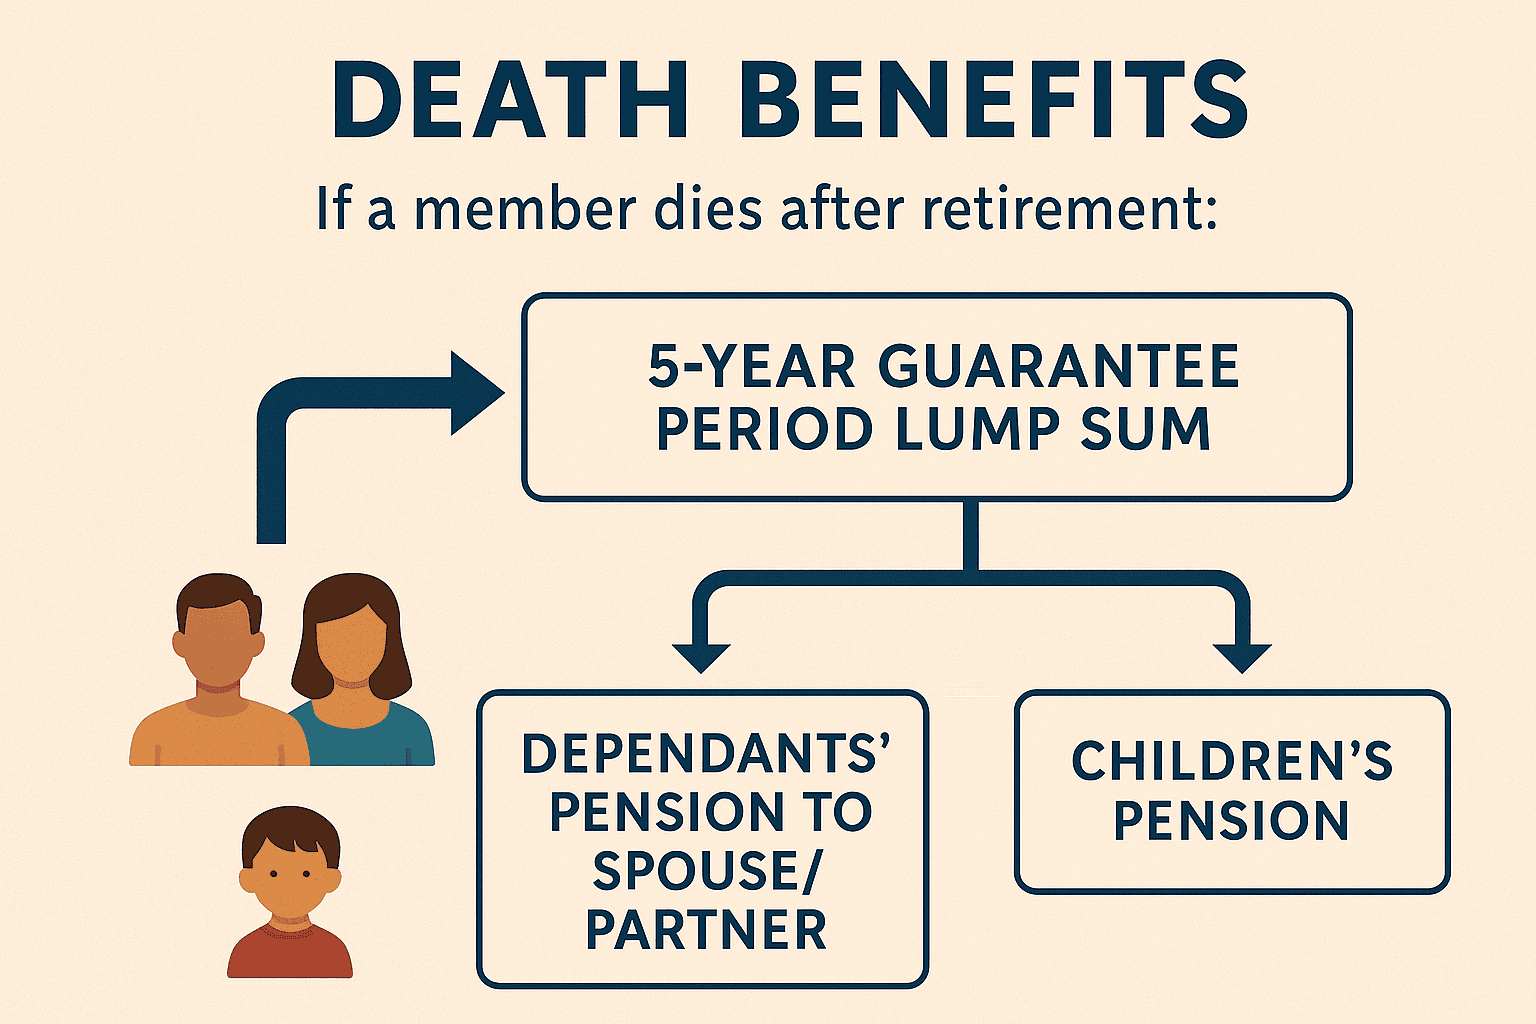 NHS Pension Contributions In 2025 : How Much Will I Get?
Defined Contribution Plans: The "You Own It" Trap
Your 401(k) is different: it’s your money, not the company’s promise. If you die, whoever you listed as a beneficiary gets the whole enchilada. But here’s the ugly twist: if you named your estate instead of a person, the taxman might take a bigger bite. Pro tip: name a human, not your will.
Now, what if you never got around to withdrawing any of it? Your heirs can inherit the account as an Inherited IRA, and they have to take it out within 10 years. That means they might get hit with a tax bill on a giant pile of money all at once. Not the worst problem to have, but still a headache.
The "What About Social Security?" Question
Social Security isn’t a pension in the strict sense, but people lump it in. If you die, your spouse might get a survivor benefit—but only if they’re old enough or caring for a minor child. If you’re divorced and married for 10+ years, same deal. But here’s a weird one: if you never claimed benefits, your spouse gets zilch. Timing matters.
And if you’re single with no kids? The government just pockets your contributions. It’s like paying for a pizza you never get to eat, and no one gets the leftovers. I call that the "cosmic irony" clause.
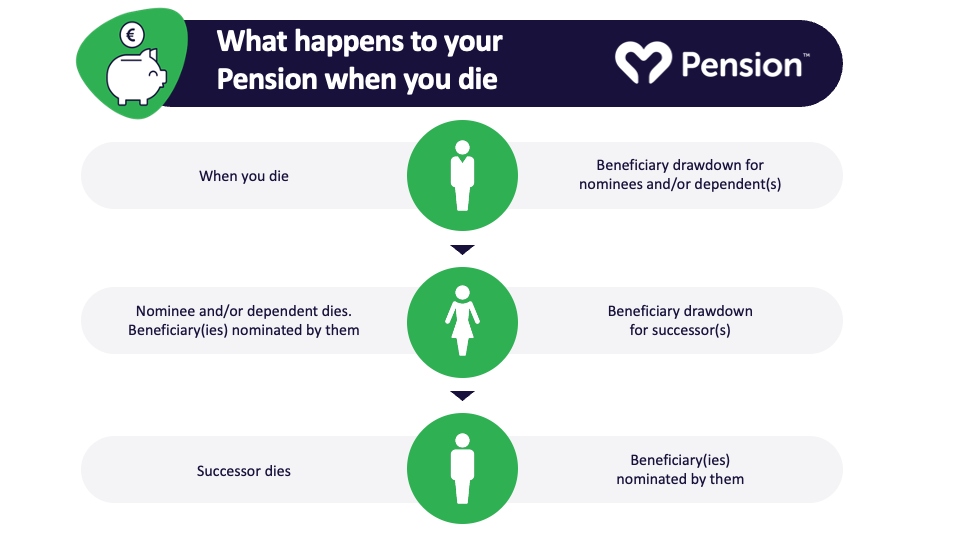 What Happens to My Pension When I Die? - MyPension
The "What Should I Do Right Now?" Checklist
First, grab your pension statement and look for the "survivor benefit" option. Do it today. Not tomorrow. Second, check your beneficiary designations on all accounts—401(k), IRA, life insurance. If it says "Estate," change it to a real person.
Third, talk to your partner or kids about what happens. It’s awkward, but less awkward than them finding out at the bank with a death certificate. Seriously. I’ve seen widows cry—and not just from grief.
Finally, consider a life insurance policy if your pension is skimpy on survivor benefits. That way, your family gets cash in hand while the pension formality plods through bureaucracy. It’s not romantic, but it’s practical.
So, what happens to your pension if you die? In some cases, it throws a party for your spouse. In others, it quietly disappears. The only way to win is to read the fine print now—and maybe buy a life insurance policy while you’re at it. Uncle Bob’s sailboat is still in the harbor, and I’d rather his widow had the cash.
