What Happens To My Pension When I Die

So, you’ve been squirreling away money for decades into that pension pot. You picture yourself sipping piña coladas on a beach, right? But then that little thought creeps in—w...
So, you’ve been squirreling away money for decades into that pension pot. You picture yourself sipping piña coladas on a beach, right? But then that little thought creeps in—what happens to all that cash if I kick the bucket before I get to enjoy it?
Let’s be real: dying is a bummer, but your pension doesn’t just vanish. It’s not like a ghost that haunts the bank vault. Nope, your hard-earned nest egg usually has a backup plan built right in.
The Big Secret: Your Pension Is a Chameleon
First, you gotta know there are two main types of pensions: defined benefit (the old-school gold watch kind) and defined contribution (your modern 401k-style pot). They react totally differently when you die—kind of like cats versus dogs.
Must Read
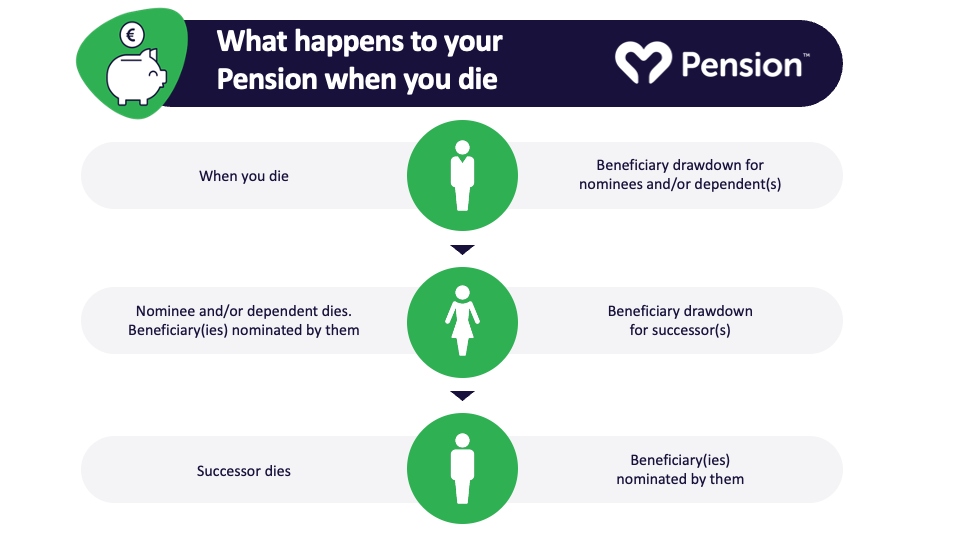
With a defined contribution plan, that pot is your money. It’s basically a giant savings account with tax perks. When you die, whatever’s left passes to your beneficiaries—usually your spouse, kids, or whoever you named.
But a defined benefit plan? That’s more like a rental agreement with your employer. You get a monthly check for life, but the leftover cash doesn’t automatically go to your heirs. Cool, right? It depends on how you set it up.
Spouse, Kids, or Stranger: Who Gets the Goods?
Here’s where it gets interesting. Most pensions let you choose a survivor benefit option when you retire. Think of it like ordering pizza: you can pick the “single life” option (cheaper monthly slices, but they stop when you’re gone) or the “joint life” option (smaller slices, but your spouse keeps eating after you’ve left the table).
If you go with joint life, your partner gets a percentage—often 50% to 100%—of your pension forever. Forever. That’s like a secret handshake that outlives you. Pretty rad, right?
But what if you’re single or your kids are grown? You might not care about survivor benefits. In that case, you can take the bigger monthly check and blow it all on travel. Your pension dies when you do—no leftovers.
 PPT - Pension Seminar for non-teaching pension plan members PowerPoint
The Taxman Cometh (But Maybe Not as Hard as You Think)
Let’s talk about the elephant in the room: taxes. When your pension goes to a spouse, it usually slides through tax-free in many countries. It’s like a permanent coupon that says “death doesn’t break the bank.”
If it goes to a non-spouse, like a sibling or a friend, they might have to pay income tax on the money. But here’s the cool part: they can often stretch the payments out over their own lifetime. It’s like inheriting a slow leak of cash instead of a fire hose—way easier to manage.
And if you die before you even start taking the pension? That untouched pot can be passed down with some serious tax advantages. It’s basically a treasure chest that says, “I saved this for you, now enjoy it.”
When Pensions Go Rogue: The Fine Print
Not all pensions are generous. Some plans—especially old-school ones—default to zero survivor benefits unless you explicitly choose them. It’s like buying a car without checking if it has airbags. Oops.
If you die without naming a beneficiary, your pension might get eaten by your estate or, worse, go to the state. That’s like leaving your wallet on the bus and hoping a stranger sends it back. Not fun.
But here’s the good news: most modern plans now require you to sign off on a survivor option. You literally cannot skip it. Think of it as a safety net for the people you love—or even for a charity you care about.
 What happens to my pension when I die - National Pension Helpline
So, Is Your Pension Your Legacy or a Ghost?
Here’s the thing: your pension isn’t just money; it’s a promise. A promise that keeps giving even when you’re not around. That’s kind of magical, if you ask me.
Imagine your spouse waking up ten years after you’re gone, and there’s still a check in the mail. Or your kid using that inherited pension to buy their first house. You’re basically a financial superhero from beyond the grave.
But here’s the kicker: none of this happens automatically. You have to choose. So grab your pension paperwork, take a deep breath, and decide who you want to high-five from the afterlife.
Bottom Line: Don’t Sweat It, Plan It
Yes, death is weird and scary. But your pension is one of the few things that can make it a little less messy. Name your beneficiaries, pick your survivor option wisely, and you’re golden.
Think of it like leaving a tip for the universe. You did the work, you saved the cash, and now someone else gets to enjoy the piña coladas. That’s not tragic—that’s actually pretty cool.
So go ahead: update that beneficiary form. Your future ghost will thank you.
