What Happens To My State Pension When I Die

Ever wonder what happens to your State Pension money when you’re no longer around? It’s a bit morbid, sure, but also kind of fascinating—like peeking behind the curtain of a g...
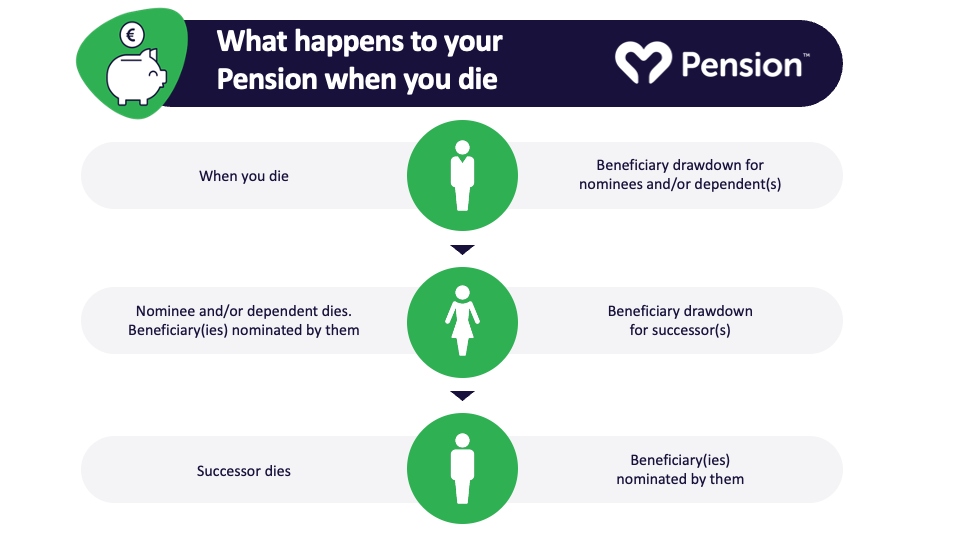
Ever wonder what happens to your State Pension money when you’re no longer around? It’s a bit morbid, sure, but also kind of fascinating—like peeking behind the curtain of a giant, ancient machine. Let’s chill out and explore this together, because understanding it actually feels pretty empowering.
The Short, Sweet Answer (Spoiler: It’s Not a Savings Account)
First up, let’s bust a big myth. Your State Pension isn’t like a personal piggy bank that you leave behind. Think of it more like a lifetime subscription to a streaming service—it pays out while you’re alive, then stops when you cancel.
So, if you die, the regular weekly payments usually stop. No, your family doesn’t get the “remaining” years of payments. But wait—don’t close the tab yet! There are some very cool exceptions that might surprise you.
Must Read
The “Dying Soon After You Claim” Scenario
This is where it gets interesting. If you pass away within a few years of starting to claim your State Pension, the government actually recognizes that as a bit unfair. It’s like paying for a full movie ticket and only catching the trailers.
In that case, your estate (that’s the legal term for all your stuff) can get a lump sum payment. It’s called a “guaranteed minimum payment,” and it usually covers the first five years of your pension, minus what you already received. Pretty neat, right? It’s like a refund on an unfinished service.
What About Your Spouse or Partner?
Here’s the part that feels like a plot twist in a financial thriller. If you’re married or in a civil partnership when you die, your partner might get a boost to their own State Pension. This isn’t automatic—it depends on your National Insurance record and the rules at the time.
For example, if you built up a much higher pension than your partner, they could inherit a chunk of yours. It’s like sharing a lifetime gym membership—if one person cancels, the other gets access to the premium level. But note: This only works for old-style “basic” pensions, not the newer single-tier system (introduced in 2016). So, if you retired recently, the rules are stricter.
 What happens to my pension when I die - National Pension Helpline
The “Inheritance” That Isn’t Cash
Here’s a fun comparison: think of your State Pension like a library card. You can’t pass along the books you checked out, but your partner can use their own card to borrow more. Similarly, your partner can “top up” their own pension using your contribution history.
This is especially cool if they took time off work to raise kids or care for relatives. Your extra National Insurance years become their gift—one that keeps paying out every week for the rest of their life. Talk about a legacy that doesn’t collect dust.
What If You’re Not Married?
Sorry, unmarried partners? The State Pension is pretty old-school here. It doesn’t recognize unmarried couples or friends you lived with as inheritors. This is one of those “wait, really?” moments—like finding out your favorite café doesn’t accept credit cards.
If you want your partner or family to get something, you’d need a separate private pension or savings. Think of the State Pension as a cozy, reliable house cat—it does one job well, but don’t ask it to fetch your slippers.
 What happens to my pension on death? - fmifa
The Weirdest “Perk” You Never Noticed
Here’s a mind-bending fact: if you die before you ever claim your State Pension (like at age 67, and you planned to wait until 70), there’s no inheritance for your family either. The money essentially evaporates back into the government’s system. It’s like buying a concert ticket, losing it, and the band still plays without you.
But don’t panic! This is precisely why financial planners scream “don’t delay claiming if you’re unwell!” It’s also why it’s smart to enjoy your own pension while you can. Because, honestly? You can’t take it with you, and neither can your dog.
So, Is This Cool or Just Bizarre?
Honestly, it’s a little of both. The system is built on a social contract: we all chip in during our working years so the current retirees get paid. When you die, your chips stay in the pot. That’s not cold—it’s communal. It’s the reason the pension exists for everyone.
The fascinating part? While you can’t pass down a wad of pension cash, you can leave behind a more stable system for your kids and grandkids. And if you plan smartly, your partner gets a little extra cushion. Not bad for a program invented in 1908.
Next time you think about pensions, remember: it’s less about “what you leave behind” and more about “what you leave on”—a safety net that catches the next generation, even if your own golden years didn’t get a sequel.
