What Happens With My Pension If I Die

Imagine you’ve built a cozy little retirement plan—like that perfect weekend playlist—only to wonder: what happens to it if I don’t make it to the encore? It’s a question nobo...
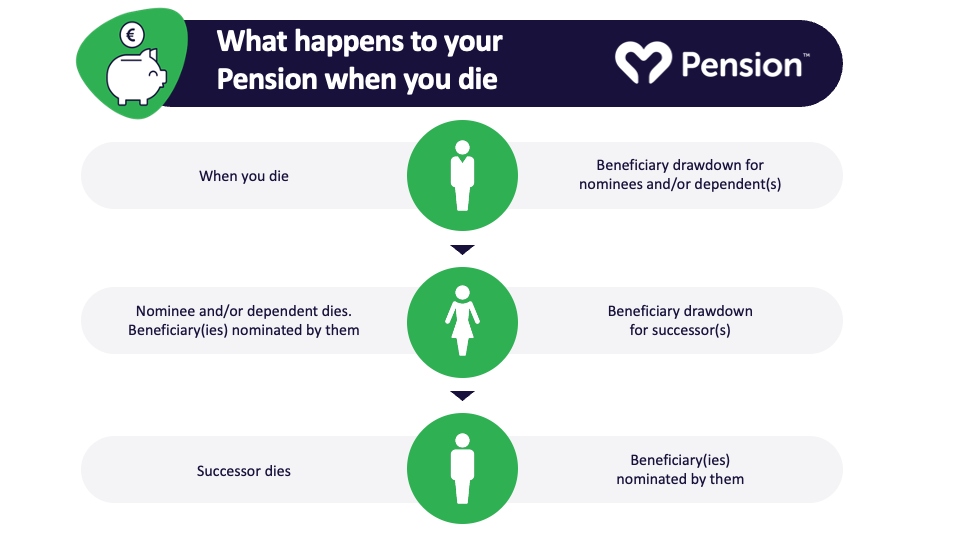
Imagine you’ve built a cozy little retirement plan—like that perfect weekend playlist—only to wonder: what happens to it if I don’t make it to the encore? It’s a question nobody wants to ask at brunch, but your future self (and your loved ones) will thank you for peeking behind the curtain. Let’s break it down with a smooth, no-panic vibe.
The Great Pension Mystery
First, a fun fact: your pension isn’t a single lump of cash under a mattress—it’s more like a subscription to a streaming service that pays you monthly. If you pass away before collecting a dime, the rules change depending on whether you have a defined benefit plan (classic employer pension) or a defined contribution plan (like a 401(k) or IRA). Think of it as the difference between a vintage vinyl collection and a Spotify playlist—one is curated by a company, the other is all yours.
In most cases, your pension doesn’t just vanish—it goes to a beneficiary you’ve named, or to your estate. But here’s the kicker: if you’re single and die before retirement, your defined benefit plan often keeps the money, like a canceled subscription. That’s why naming a beneficiary is your golden ticket.
Must Read
The Spousal Safety Net
If you’re married, the plot thickens—and gets warmer. In the U.S., federal law (ERISA) requires your spouse to sign off if you want to name anyone else as beneficiary for a defined benefit plan. It’s like a trust fall: your spouse automatically gets at least 50% of your pension as a survivor benefit, unless you both opt for a lower payout. Imagine you’re in a rom-com—your pension is the house, and your partner gets the keys (plus the mortgage-free vibe).
But here’s a practical tip: choose the “joint and survivor” option when you retire. It reduces your monthly check by about 5–10%, but it’s like buying insurance for your partner’s future. Think of it as a friends-with-benefits deal—but with your pension.
What About Your 401(k) or IRA?
Ah, the DIY pension—the cute little basket of stocks and bonds you built yourself. If you die, the full balance goes to your named beneficiary—no spousal drama, no limits. This is where you channel your inner Jeff Bezos: you can leave it to a charity, your best friend, or that cousin who always sends birthday memes. The catch? Your beneficiary must withdraw the money within 10 years (under the SECURE Act), or pay taxes like you’re buying a luxury handbag—slow and painful.
 NHS Pension Contributions In 2025 : How Much Will I Get?
Pro tip: Update your beneficiary forms every time you get a new partner, a new cat, or a new tattoo. Divorced? Remarried? Your ex might still be listed, and that’s a plot twist worthy of a Netflix thriller.
No Beneficiary? The State Steps In
Picture this: you die without a will and no beneficiary named. Your pension goes into probate, which is like a bureaucratic black hole where distant relatives and lawyers feast. In the U.S., probate can take 6–18 months—longer than a Taylor Swift tour stop. The state decides who gets the money, often your kids or parents, but it’s messy and expensive. Don’t be that person.
Fun fact: In Japan, some pensions literally disappear if you have no heirs—they call it “mushōkyō” (無償供与), which sounds poetic but tastes like sour grapes. So, fill out that beneficiary form today. It’s easier than assembling IKEA furniture.
Lump Sum vs. Monthly Payments: The Twist
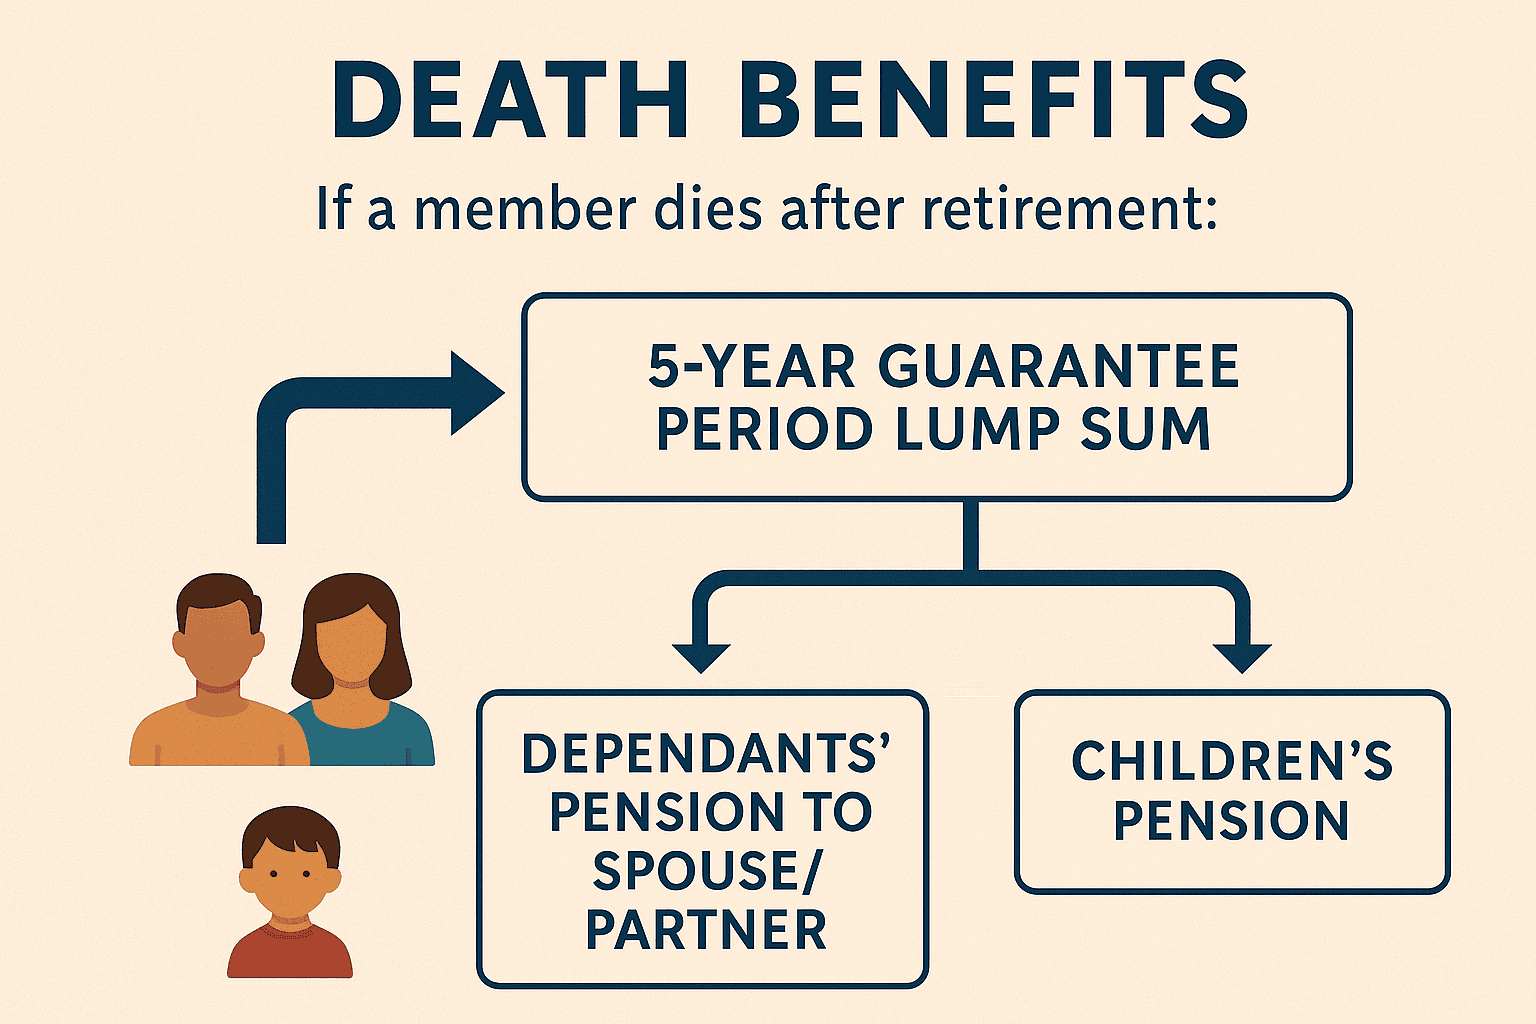
If you’re already retired and collecting payments, the game changes. Most pensions offer a lump sum when you die—your spouse gets the remaining value, but not the future payments. Think of it as canceling a subscription and getting a refund for unused months. But beware: some plans reduce the lump sum if you chose the “single life” option—the ego trip of retirement—which pays you more but leaves nada for anyone else.
 PPT - Pension Seminar for non-teaching pension plan members PowerPoint
Practical tip: Ask your HR or pension provider for a “survivor benefit estimate.” It’s like checking the weather before a picnic—suddenly, everything becomes clear. And remember, if you’re under 59½, your beneficiary might owe taxes on the lump sum, so chat with a tax pro before you plan the memorial playlist.
Cultural Snapshots: How the World Does It
In the UK, the “state pension” dies with you—no survivor benefit—but your partner can inherit a portion if you deferred it. Meanwhile, in Australia, superannuation (their 401(k) equivalent) is like a trust fund baby: it flows tax-free to your beneficiaries if it’s from a taxed source. Think of it as a barefoot wealth transfer. In Sweden? They have a system so flexible, you can name your dog as beneficiary (just kidding—but their rules are that chill).
Your Daily Life Connection
Here’s the reflection you didn’t know you needed: Your pension is a love letter to your future self—and one you can’t deliver if you don’t plan the address. The next time you’re waiting for your coffee order, pull out your phone and check your beneficiary form. It takes five minutes, which is less time than you spend scrolling through memes of cats knocking over plants.
Live your life like you’re writing a memoir—generous, prepared, and a little bit skeptical. Your pension isn’t a burden; it’s a handshake with tomorrow. So, name your person, update that form, and go enjoy your latte. Because the best legacy is a story that keeps giving—even when you’re not there to turn the page.
