What Happens With Your Pension When You Die

So, you’ve been squirreling away money into your pension for decades. You picture retirement: lazy mornings, maybe a little travel, definitely a lot of coffee. But then the st...
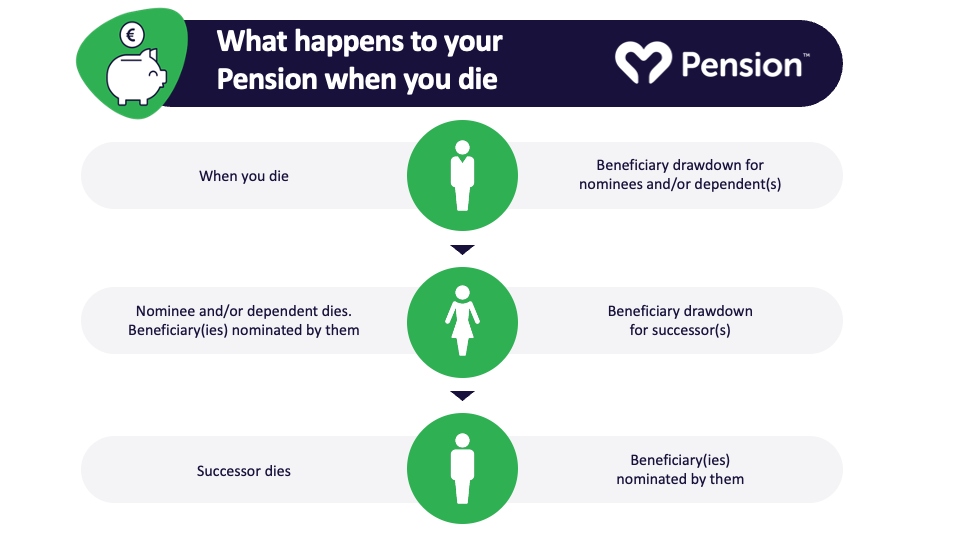
So, you’ve been squirreling away money into your pension for decades. You picture retirement: lazy mornings, maybe a little travel, definitely a lot of coffee. But then the sticky thought creeps in—what if I don’t make it to the finish line?
It’s a weird one, right? Pensions are all about you surviving to enjoy them, but life happens. The good news? Your pension doesn’t just vanish into a black hole. It’s actually pretty cool how the system handles the whole “departure lounge” scenario.
The Two Big Roads: Defined Benefit vs. Defined Contribution
First, you need to know what kind of pension you have. Think of it like choosing between a classic vinyl record and a streaming subscription.
Must Read
A Defined Benefit pension (the old-school company pension) promises a set monthly paycheck for life. This one is like a grandpa clock—reliable, steady, and full of rules. A Defined Contribution pension (a 401(k) or personal pot) is more like a mixed tape—you control what goes in, and it grows based on your choices.
And guess what? What happens to your money depends heavily on which road you’re on. Let’s break it down without the headache.
If You Die Before You Start Collecting
This is the “untimely departure” scenario. You’ve saved up, but you never actually took a dollar out. Who gets your savings?
In a Defined Contribution pot, the answer is refreshingly simple: your beneficiary gets the whole lump sum—usually tax-free or with very light tax. It’s like leaving an inheritance in a brown paper bag labeled “future fun.” But in a Defined Benefit plan, it’s trickier. You might get a refund of your own contributions only, or a small lump sum for your spouse, but the company keeps the rest. Ouch.
That’s why naming a beneficiary is so critical—it’s like leaving a map to your treasure chest. Without it, the government gets a say, and nobody wants Uncle Sam picking their pockets.
 What Happens To Your Private Pension When You Die? 2026 Guide
If You Die While Already Collecting
Now this is where it gets fascinating. Imagine you’re halfway through your dreamy retirement, and you pass away. What happens to the monthly checks?
For a Defined Benefit plan, it depends on the “survivor benefit” you chose when you retired. Did you opt for a 100% survivor benefit? Then your spouse keeps getting your full check forever. Did you pick a 50% survivor benefit? They get half. And if you chose the “single life” option for a bigger monthly check? Poof—the payments stop dead the day you do. It’s a gamble, but you knew that.
For Defined Contribution accounts, the drama is lower. Your remaining pot—anything not yet withdrawn—goes straight to your named person. They can take it as a lump sum or stretch it over their own retirement. It’s your money, and it stays in the family.
The Five-Year Rule (Don’t Panic)
Here’s a quirky little rule that makes you go “huh.” If you die while drawing a pension from a personal pot, the tax people sometimes hit your beneficiary with a big bill—unless you plan wisely. In many countries, if they don’t empty the account within five years, taxes can surge. It’s like a countdown timer on a game show: “Use the cash or lose it to the taxman!”
But some plans let them keep the money growing tax-free for decades if they treat it as their own pension. Naming a “successor beneficiary” is like passing the remote control to your kid.
 What Happens to Your Pension When You Die? The UK Rules Most People Don
Why This Is Actually Cool
Let’s be real: thinking about death is a downer. But here’s the twist—your pension is a living thing. It’s not just a pile of cash; it’s a legacy tool. You can set it up so your partner still travels, your kids buy a house, or your favorite charity gets a boost.
Compare it to a gold watch handed down through generations. Only this watch pays for groceries. That’s pretty awesome, right?
Plus, the rules are changing fast. More plans now let you leave your pot to a grandchild, who can stretch the tax benefits over their longer life. It’s like planting a money tree that blooms for decades after you’re gone.
The Golden Rule: Talk to a Human
Here’s the boring but vital bit: always update your beneficiary forms. If you got married, divorced, or had a kid, the old form from 2005 doesn’t count. It’s like a dead battery in a smoke detector—useless when you need it.
And please, talk to a financial advisor for five minutes. They can help you pick the right “survivor option” in a Defined Benefit plan or show you how to avoid the tax traps on a personal pot. It’s not romantic, but it’s the kindest thing you can do for the people you love.
So, next time you check your pension statement, smile. You’re not just planning for your future—you’re arranging a quiet, considerate goodbye that says, “I had your back, even when I wasn’t around.” And that is a pretty cool legacy.
