What Is A Guaranteed Interest Account

Last Tuesday, my Aunt Carol called me in a state of mild panic. She had just cleaned out her old filing cabinet and found a dusty certificate from 1998. “It says I put five th...
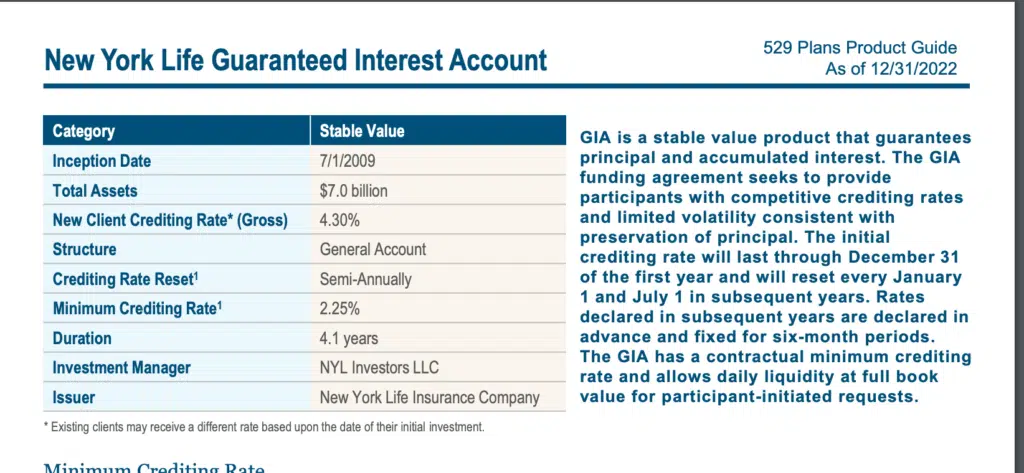
Last Tuesday, my Aunt Carol called me in a state of mild panic. She had just cleaned out her old filing cabinet and found a dusty certificate from 1998. “It says I put five thousand dollars in a ‘Guaranteed Interest Account,’” she whispered, like she’d discovered a treasure map. I could almost hear her eyebrows shoot up. “Is this thing worth anything, or did I just find a very fancy coaster?”
I laughed, but her question got me thinking. A Guaranteed Interest Account—or GIA, for the acronym lovers out there—sounds like something a wizard would offer you in a fantasy novel. But it’s actually a very real, very boring financial product, and boring is good when it comes to your money. It’s basically a savings account that promises you a fixed interest rate for a specific period, usually one to five years.
Let’s break this down with a little more nuance, since Aunt Carol deserves a real answer—and so do you. Imagine you lend your most reliable friend $100, and they swear on their life they’ll pay you back plus a little extra interest next Tuesday. That’s the simple version. A GIA is the same concept, but the “friend” is a bank or insurance company, and the “next Tuesday” is a commitment you can’t easily break.
Must Read
The Big Promise: No Surprises
Here’s the sexy part (yes, finance can be sexy in a plaid-shirt kind of way). The bank guarantees you a specific interest rate—let’s say 4%—for the entire term. If the market crashes and the economy turns into a dumpster fire, you still get that 4%. It’s like ordering a pizza and knowing, no matter what, the delivery guy will show up with exactly that pepperoni masterpiece. And he won’t be late.
But—and there is always a “but”—if interest rates skyrocket to 8% next year, you are stuck at 4%. That’s the trade-off for safety. Think of it as wearing a raincoat in a drizzle: you stay dry, but you also look a bit ridiculous when the sun comes out. You can’t cash out early without a penalty, either—usually a few months of forfeited interest. So, no using your GIA to fund a spontaneous trip to Bali. Sorry.
 The 8 Best Guaranteed Interest Investment Accounts
Where Do These Accounts Live?
You’ll find GIAs mostly at insurance companies or credit unions, not your typical big bank checking account. They are often called “Fixed-Rate Accounts” or “Investment Guarantees” in fancy brochures. Important side note: In Canada, they’re basically the GIC (Guaranteed Investment Certificate) you’ve heard your grandpa talk about. In the US, they’re sometimes called Multi-Year Guaranteed Annuities (MYGAs) when sold by insurers. Yes, the names are confusing. Financial people love jargon. It makes them feel important.
Let me get personal for a second. I once put $3,000 into a GIA for three years because I was terrified of the stock market. The rate was a paltry 2%, but I knew, come what may, that money would grow to $3,183.60. That certainty let me sleep at night while my friends were sobbing over their crypto portfolios. And you know what? That peace of mind was worth more than the extra 1% I might have scraped elsewhere.
When Should You Actually Bother?
You should consider a GIA when you have a lump sum—like a bonus, inheritance, or a tax refund—that you need to protect for a short to medium term. Maybe you’re saving for a house down payment in two years, or you’re retired and can’t afford to lose your principal. It’s your financial safety blanket. Don’t use it for your emergency fund, though—you need that cash available tomorrow, not in 2027.
 PPT - Maximizing Your Returns Unveiling the Power of Guaranteed
One thing that trips people up: the interest is usually taxable. If you’re in a high tax bracket, that guaranteed 4% becomes a net 2.5% after the tax man takes his cut. So, if you’re wealthy, you might be better off with stocks. But for the rest of us mortals, it’s still a solid, boring win.
Aunt Carol’s dusty certificate from 1998? She had a 15-year GIA at 6.5%. That’s a fantastic rate by today’s standards. But since it matured years ago, it started rolling over into whatever paltry rate the bank offered later—probably 0.5%. She felt a brief pang of nostalgia, then wisely moved the money into a new GIA at 4.5%. Smart lady.
So, to sum it up: A Guaranteed Interest Account is for people who value a good night’s sleep over a shot at the moon. It’s not flashy. It won’t make you a millionaire. But it will not betray you. It’s the financial equivalent of a handshake from a trustworthy friend—no asterisks, no fine print, just a promise. And in a world full of broken promises, that’s kind of beautiful, isn’t it?
