When Is Best Time To Renew Car Insurance

So there I was, last December, staring at my inbox like it owed me money. A single email subject line screamed: “Your Car Insurance Renewal—URGENT!” I’d completely forgotten m...
So there I was, last December, staring at my inbox like it owed me money. A single email subject line screamed: “Your Car Insurance Renewal—URGENT!” I’d completely forgotten my policy was up in two weeks. Naturally, I panicked, clicked “renew now” faster than a cat dodging a bath, and locked myself into a price that made my wallet weep. Later that week, my buddy Sarah told me she’d saved $300 by waiting just three more days before her renewal date. Ouch. Right then, I knew I had to figure out: when is the best time to renew car insurance—without the last-minute scramble?
The Lazy Answer (And Why It’s Wrong)
Most people think the “best time” is the day their policy expires. You know, because you have to have insurance to drive legally, so you just click “renew” and move on with your life. That’s what I did, and guess what? I paid for my laziness. Insurance companies love last-minute renewals—it signals that you’re not shopping around, and they can jack up your rate without you noticing. Don’t be that person. The real sweet spot is not the expiration day.
The Magic Window: 21 to 30 Days Before Expiry
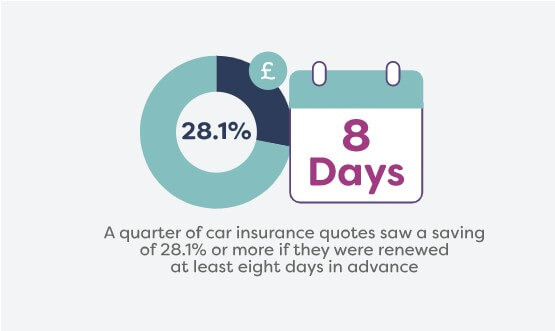
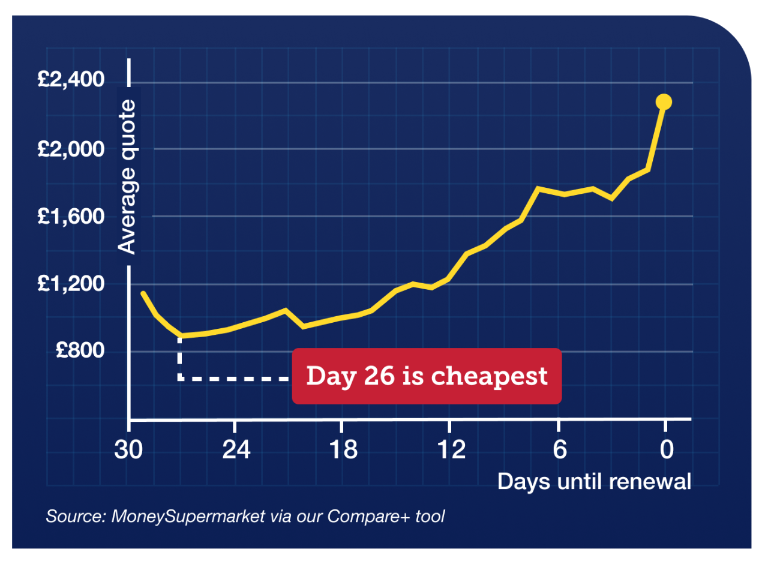
Here’s the cold, hard truth I learned the hard way: the best time to renew is about three to four weeks before your current policy ends. Why? Because that’s when insurers start sending you renewal quotes—but you haven’t entered the “automatic renewal” danger zone yet. You have breathing room to compare offers, call your current provider, and play hardball. Plus, most car insurance companies reward early birds with discounts for “loyalty” or “no-lapse coverage” when you renew ahead of time. Just don’t wait until the last week—that’s when prices mysteriously climb.
Must Read
But What If I’m a Chronic Procrastinator? (I See You)
Okay, fine—if you’re reading this with your policy expiring in, say, 10 days, don’t panic. You’ve still got options. The second-best time to renew is right now, but only if you switch providers. New customer quotes are often cheaper than your current renewal notice, because insurers fight for fresh blood. Seriously, I once got a quote from a competitor 40% lower than my renewal, just because I was a “new driver” to them (even though I’d been driving for years). But be warned: switching at the last minute can leave you uninsured for a day if you mess up the start date—so read the fine print, you lazy genius.
 Compare by MyEG: Online Car Insurance Comparison & Takaful Renewal Malaysia
The Seasonal Sneak Attack: Renew in Off-Peak Months
Here’s a curveball for you: the time of year matters too. Insurance rates fluctuate based on demand. For example, January and August are peak renewal months (everyone’s policy resets or they move for school), so prices are higher. Meanwhile, renewing in late fall—like November or early December—tends to be cheaper because fewer people are shopping. I renewed my policy in November last year (after my December disaster) and saved 15% just by shifting my renewal date by a few weeks. You can literally ask your insurer to move your renewal date to a slower month—most will let you do it for free. Mind blown, right?
The “Quote Runaround” Trap (Don’t Fall For It)
One thing nobody tells you: getting quotes too early can backfire. If you start comparing prices 45 days or more before your renewal, many insurers will give you a quote that expires before your policy ends. Then you’re stuck re-shopping and the price changes. I once got a great quote, waited three weeks to decide, and when I came back, the premium had shot up by $50 because of “market adjustments.” The lesson: start comparing quotes about 30 days out—that gives you a valid window to lock in a rate without the expiry sabotage.
 List Of Insurance Quotes Private Health Insurance Compare Quotes
The Bonus Trick: Use Your Own Record as a Weapon
Don’t just look at the calendar; look at your driving record. The absolute best time to renew is right after your last traffic ticket or accident falls off your record (usually three years). If you’ve been a good boy or girl for 12 months, call your insurer and say, “Hey, I’ve got a clean record now—can you lower my rate?” They’ll often adjust it mid-policy, but if they don’t, wait until that 30-day renewal window and switch providers to get credit for your newfound angelic driving. I did this after a speeding ticket expired, and my premium dropped by $200.
One Final Irony (Because Life Loves a Joke)
Here’s the funny part: after all this planning, I once renewed my car insurance exactly 29 days early, feeling like a financial ninja. Two weeks later, I got into a minor fender bender. My rates went up anyway. So yeah, the “best time” is a moving target. But the safest best time? Start shopping around 30 days before expiry, avoid the last-minute panic, and never, ever just hit “renew” without checking at least two other quotes. Your wallet—and your future self—will thank you. Now go check your calendar. Seriously. I’ll wait.
