How To Calculate Net Worth? Simple Formula For Assets Minus Liabilities
Let’s be honest: the phrase “net worth” sounds like something a billionaire in a boardroom would whisper over a glass of scotch. But it’s actually just a fancy way of saying “...

Let’s be honest: the phrase “net worth” sounds like something a billionaire in a boardroom would whisper over a glass of scotch. But it’s actually just a fancy way of saying “What you own minus what you owe.” It’s not about being rich; it’s about being aware.
Think of it like this: your net worth is the financial version of your closet. On one side, you have the cool stuff you actually own. On the other, you have the stuff you borrowed from a friend and keep forgetting to return. The real story is what’s left after you give everything back.
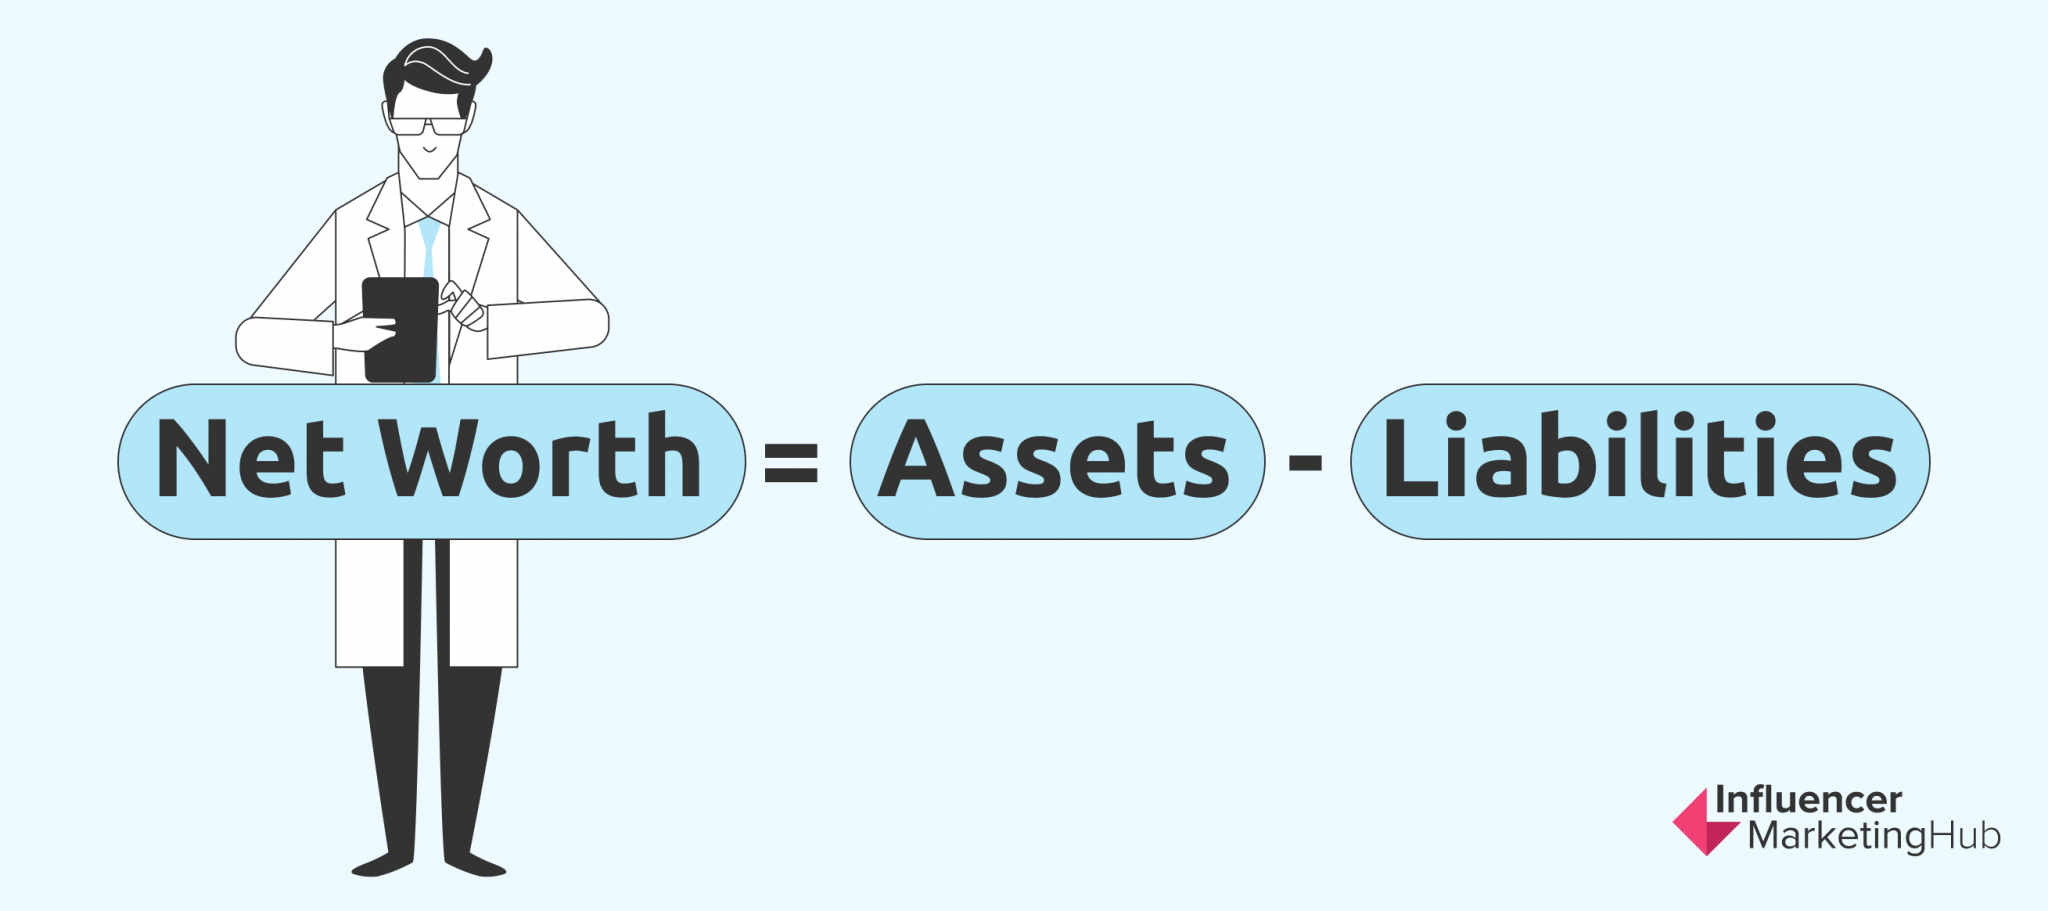
Let’s break it down with the simplest formula: Assets – Liabilities = Net Worth. That’s it. No calculus. No magic wand. Just a little subtraction that can change how you feel about your money.
Must Read
What the Heck Are Assets?
Assets are the things that put money in your pocket or have cash value. They are your financial “yes” pile. Your savings account? That’s an asset. Your car, even if it smells like last week’s takeout? Yep, also an asset—but only for what you could sell it for today.
Don’t forget the little things: that dusty coin collection, the bonds your grandma gave you, or the 401(k) you barely look at. Even your dog? No, he’s a liability (vet bills). Just kidding—your dog is an asset to your heart, but not on the spreadsheet.
Liability: The Party Crasher
Liabilities are the money you owe to other people or companies. They are the financial “not yet” pile. Think student loans, credit card balances, your mortgage, or that “buy now, pay later” couch you just had to have.
 Chip Explains: Net Worth - Chip Explains Finance
Here’s a fun (and slightly painful) example: Remember last year when you bought a brand new phone plan plus the latest iPhone? That monthly payment is a liability. Meanwhile, the phone itself is an asset—but it’s losing value faster than a leftover sandwich in the office fridge.
Liabilities are like that friend who always says, “I’ll pay you back next week,” but never does. You need to count them honestly to see your true picture.
The Magical Subtraction
Now comes the fun part. Grab a sticky note or open a notes app. Add up all your assets—your cash, car, home equity, investment accounts. Then add up all your liabilities—every loan, every credit card balance, every IOU.
 Chapter 3 – Consumer Credit Analysis: The Five Cs of Credit
Assets – Liabilities = Your Number. If the result is positive, you’re in the green. If it’s negative, don’t panic. You’re not alone. Many people start below zero. It’s just a starting line, not a finish line.
Let’s use Sarah, a real person. Sarah has $5,000 in savings, a car worth $10,000, and $3,000 in a retirement fund. Total assets: $18,000. She has $12,000 in student loans and $2,000 on a credit card. Total liabilities: $14,000. Her net worth? $4,000. Not a millionaire, but she’s in the black. That’s a win.
Why You Should Actually Care
Okay, but why does this matter on a Tuesday morning while you’re sipping lukewarm coffee? Because your net worth is a reality check without the judgment. It tells you if you’re building a castle or just piling up sand.
Think of it as your financial cholesterol. You don’t check it to feel bad—you check it to know if you need to eat more veggies (save more) or cut back on the cheeseburgers (spend less). A rising net worth means you’re making progress, even if slowly.
 Assets And Liabilities Formula
It also helps you make smarter, happier choices. Want to take that vacation? If your net worth is climbing, you might splurge. If it’s dropping, maybe you skip the overpriced airport sushi instead.
One Tiny Rule: Be Kind to Yourself
Your net worth is not your worth as a human being. It’s a number. A tool. Like a measuring cup, it just tells you how much dough you’ve got. Don’t compare your number to your neighbor’s—they might have a hidden inheritance or massive credit card debt you don’t see.
Track your net worth once a quarter. Watch it go up, watch it wobble. It’s like watching a plant grow—slow and unglamorous, but deeply satisfying when it finally blooms.
 Assets And Liabilities Formula
A Friendly Warning
Some people will try to tell you that net worth is only for the wealthy or for retirement planning. They’re wrong. It’s for anyone who wants to sleep better at night. When you know your number, you own your story.
Also, don’t include your emotional attachments. That vintage lamp from your aunt? It’s an asset only if you’d actually sell it. Sentimental value doesn’t pay the electric bill. Be real, be honest, and you’ll actually feel lighter.
So here’s your homework: Tonight, after you binge-watch your favorite show, spend ten minutes calculating your net worth. Use a napkin, a spreadsheet, or a cool app. Just do the simple math. Assets minus liabilities. That’s it.
You might be surprised. Maybe you’re richer than you think. Or maybe you’ll finally see that $8 daily latte habit is a tiny liability monster. Either way, you’ll be in control—and that feeling? That’s priceless.