Can I Claim My State Pension And Still Work

So, you’ve finally hit that magical age where the government starts sending you a little “thank you for surviving adulthood” bonus. But here’s the million-dollar question: Can...
So, you’ve finally hit that magical age where the government starts sending you a little “thank you for surviving adulthood” bonus. But here’s the million-dollar question: Can you claim your state pension and still work? Short answer: Absolutely yes—and you can even do a little happy dance while clocking in.
Let me paint you a picture. You’re sitting there, imagining yourself sipping tea in a rocking chair, but you’re also itching to keep your brain busy—or maybe you just want to buy more snacks. The good news? The state pension doesn’t care if you’re still slinging coffee, coding apps, or running a llama farm. It’s yours, no matter what.
The No-Sweat Rule
Unlike some jobs where your boss frowns at your side gig, the UK state pension has zero rules about working. Zero. Nada. You could be a 67-year-old TikTok influencer and still collect your full pension. The government isn’t peeking at your paycheck—they just want you to hit the qualifying age.
Must Read
Here’s the kicker: You don’t even have to stop your main job. Whether you’re a part-time cashier or a full-time CEO of your own jam-making empire, the pension keeps rolling in. The only “catch” is that you need to have paid enough National Insurance contributions during your working years—but that’s already sorted if you’re eligible.
But Wait—What About Taxes?
Ah, taxes. They’re like that one friend who always shows up uninvited to the party. Yes, your state pension is taxable income, but so is your salary. The good news? You get a tax-free personal allowance each year (usually around £12,570). If your total income stays under that, you pay zero tax. If it’s higher, you just pay a slice—and you can adjust your tax code to avoid a surprise bill.
Think of it this way: working while claiming your pension is like having two streams of cash—but only one of them gets taxed a little. Not bad, right?
Can You Get a Bonus for Delaying?
Now, if you don’t need the money right away (lucky you), you can choose to defer your state pension. For every nine weeks you delay, your pension goes up by 1%. Wait a whole year, and it’s about a 5.8% boost—like a loyalty reward for being patient. But if you’re still working, you might think, “Hey, I’ll just defer and get more later!”
Just remember: you can change your mind at any time. No pressure, no penalties. You could start claiming today, then stop next month if you fancy—but honestly, why would you? Cash in hand now is still pizza money now.
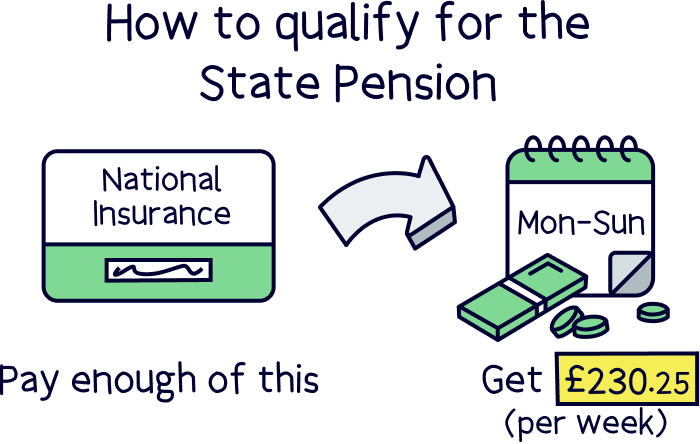 When can I claim my State Pension? - Nuts About Money®
What If You’re Self-Employed?
Oh, you’re a freelance wizard or a side-hustle ninja? Perfect. Self-employed folks can claim the state pension and work just like everyone else. In fact, you might even enjoy the security of a regular pension payment while you chase that next big project. No boss, no limits—just you, your laptop, and a steady stream of government-backed cash.
One tiny caveat: if you’re self-employed and still under pension age, you still have to pay National Insurance. But once you hit that golden age, you can stop paying Class 2 or Class 4 contributions—and keep working. It’s like getting a “work without the paperwork” upgrade.
The “Work” Part: How Much Is Too Much?
Here’s the beautiful truth: there’s no earnings limit. You could earn a million pounds a year (if you’re that good) and still get your full state pension. No one says, “Oops, you’re earning too much, so we’re cutting you off.” That’s for the old-style pensions—your state pension is like a sturdy friend who doesn’t care about your bank balance.
So, go ahead, pick up that extra shift, start that Etsy store, or finally teach that ukulele class. The pension is your foundation; the work is your fun money. Win-win.
But What About Your Employer’s Pension?
If you have a private or workplace pension too, you can claim that and your state pension and still work. It’s like a triple-decker sandwich of financial security. Just remember: private pensions might have their own rules about when you can take them, but the state one is always ready to party.
 How to Check Your State Pension Forecast Online - UK Finance 2026
One hilarious note: some people worry that working will “delay” their pension. Nope. It’s not like a soufflé that needs to rest. The state pension starts on your state pension birthday, and work doesn’t push that date back. So don’t stress—just keep earning.
The Bottom Line (With a Sprinkle of Fun)
Alright, let’s wrap this up like a cozy blanket. Yes, you can claim your state pension and still work. You can work full-time, part-time, or only on days that end in “Y.” The government doesn’t care. Your pension is your reward for decades of “adulting,” and you’ve earned the right to double-dip.
If you’re worried about forms or phone calls, relax—applying is easier than assembling IKEA furniture. You can do it online in 20 minutes, and they’ll send you a letter confirming your start date. Then the money just shows up, like a loyal, punctual friend.
One last little secret: many people who work after claiming their pension say it keeps them younger, happier, and less likely to talk to their plants (though plants are great listeners). You can have the best of both worlds: financial security from your pension, and purpose (and extra cash) from your job. It’s not a retirement; it’s a “refinement.”
So, put on your favorite work shoes—or slippers, we don’t judge—and go claim that pension. You’ve got this. And remember: working while on a pension just means you have more money for the things that matter, like travel, hobbies, or a truly ridiculous collection of cat T-shirts. Here’s to you, the unstoppable, pension-collecting, career-bending legend. Now go make that money—and smile while you’re at it.
