Cheapest Car To Insure As A New Driver

Let’s be honest: getting your first car is like winning a golden ticket, only to realize the fine print says you have to pay for the factory tour. You’ve spent months dreaming...
Let’s be honest: getting your first car is like winning a golden ticket, only to realize the fine print says you have to pay for the factory tour. You’ve spent months dreaming of freedom, the open road, and blasting your playlist at a volume your parents hate. Then reality hits you with the insurance quote, which looks less like a bill and more like a ransom note for your future paychecks. Suddenly, that 1998 sports car with the dented fender feels like a bad date you can’t ghost.
The first rule of thumb for new drivers is this: drive a toaster, not a rocketship. Insurance companies view new drivers the way we view a puppy in a china shop—cute, but we know something’s about to break. The cheapest cars to insure are the ones that scream “boring reliability” from every panel. Think of the Honda Civic, Toyota Corolla, or Mazda3. These cars have the personality of a beige office chair, but your wallet will love them.
Why do insurance companies love these pedestrian machines? Because nobody is drag-racing in a Corolla at 2 AM. These cars are hard to steal, cheap to fix, and their engines have the same adrenaline level as a librarian on a coffee break. You can’t get a speeding ticket if your car gently suggests you slow down. It’s a feature, not a bug.
Must Read
The “Clunker” Trick That Actually Works
I once knew a guy named Dave who bought a 2005 Hyundai Elantra for $900. The paint was peeling, the radio only played static, and the AC smelled like a wet sock. But Dave’s insurance was so cheap, he could afford to buy a better Bluetooth speaker to drown out the static.
Older, cheaper cars often come with lower insurance premiums because you’re only insuring against damage to others, not to your own rolling scrap heap. If you total it, you shrug and walk away. You don’t cry over a smashed toaster. The key is to find a car that’s safe, not sexy. A 2012 Kia Rio? Boring. Your bank account? Thrilled.
Don’t fall for the trap of a 2002 Mustang just because it’s cheap to buy. That car is a magnet for insurance surcharges. It’s like buying a cheap pizza—the cost seems low, but you’ll pay for it later in heartburn and regret.
What Actually Makes the Price Drop?
Here’s the secret sauce: cars with good safety ratings and low horsepower are insurance gold. A Subaru Impreza? Solid. A Ford Fiesta? Score. A Dodge Charger with a V8? That’s a personal finance crime. Insurers use a simple formula: more power equals more panic for them.
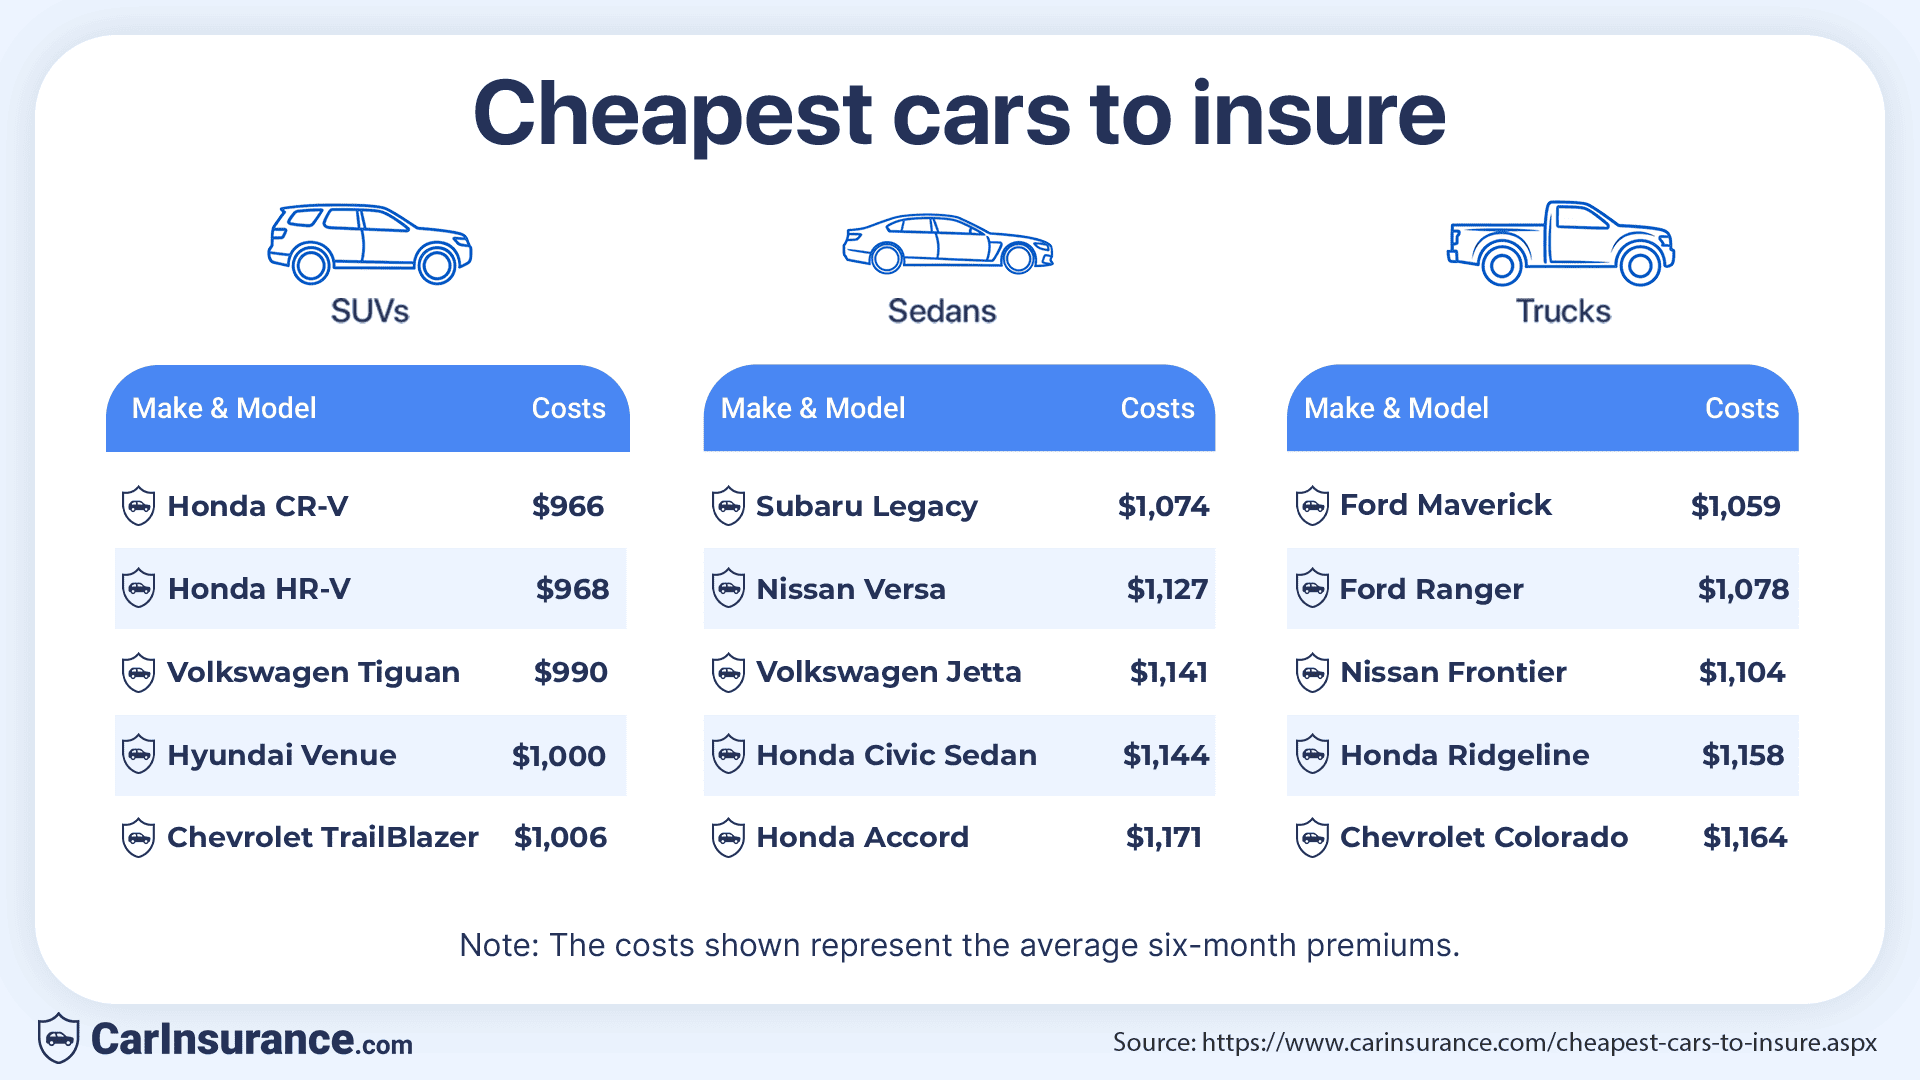 Get Free Car Insurance Quotes in the USA for 2025 | CarInsurance.com
Also, look for cars that are annoyingly common. If a car is everywhere (like a Honda CR-V), parts are cheap, and mechanics know them like their own kids. That means lower repair costs, which means lower insurance for you. It’s the same logic as ordering the cheapest item on the menu—nobody raves about it, but nobody cries over the bill.
I remember my first car was a 1999 Saturn SL1. It was the color of faded mustard. I named it “The Scooter.” It had no airbags in the back and the engine sounded like a lawnmower with a cold. But my insurance was $80 a month. Eighty dollars. I drove that sad little box like it was a chariot, because it was the only chariot I could afford to crash.
Don’t Forget the “Ghost” Factor
One weird trick that works? Look at mini-vans. Yes, the family van. A Honda Odyssey or Toyota Sienna will make you feel like your dad, but insurers see a low-risk, responsible driver. It’s the automotive equivalent of wearing a helmet to bed—boring, but safe.
The price difference can be shocking. A 21-year-old insuring a 2016 Ford Focus might pay $1,800 a year. The same person in a 2016 Dodge Challenger? Try $3,500. That’s the price of a decent used car every year. You could buy a new phone, a plane ticket, and still have cash left over. Choose wisely.
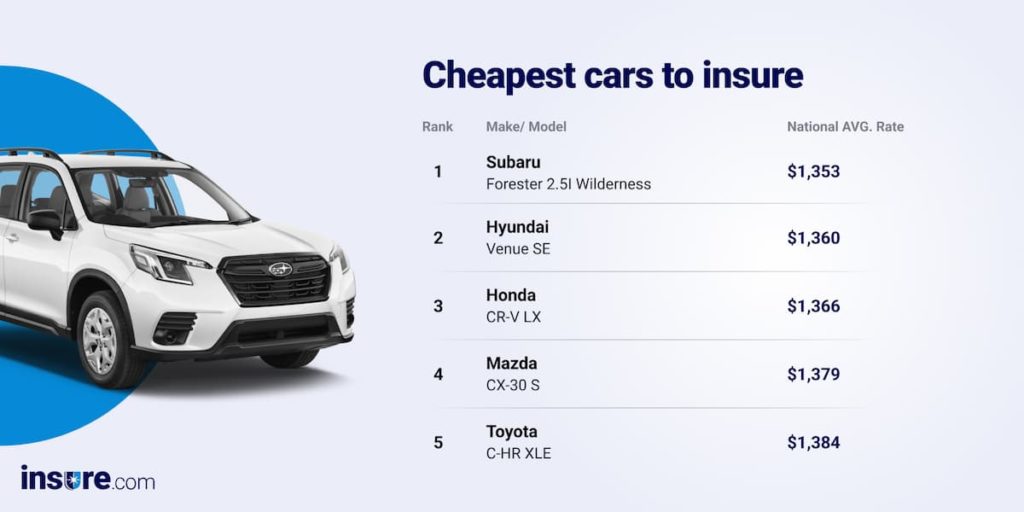 Ranking the most expensive & cheapest cars to insure for 2023
And please, for the love of your own sanity, avoid any car with the word “Turbo” in the name until you’ve been driving for at least three years. Turbos are for people who like excitement and high payments. You, my friend, are training for the marathon of adulting, not a drag race.
The car you drive in your twenties is a statement. Let that statement be: “I’m broke, but I’m smart.” Drive a car that’s cheap to fix, cheap to run, and has the aerodynamic charm of a shoebox. Your friends might laugh. You’ll laugh last when you’re the only one who can afford gas and dinner in the same week.
The Final Honk
Before you buy, check the insurance quote online. A 30-second search can save you $500 a year. That’s money for tacos. Or a better radio. Or therapy for the trauma of driving a beige sedan.
Remember this: the cheapest car to insure as a new driver is the one that makes you feel like a sensible adult, even if you’re still eating cereal for dinner. Go find a Subaru Outback, a Honda Fit, or a Toyota Yaris. They’re the unsung heroes of the driveway. They’ll never impress a date, but they’ll never embarrass your bank account either. And in the end, being able to afford your own car is cooler than any fancy paint job. Trust me. I’ve driven both.
