Credit Score For A Camper

So, you’ve decided to embrace the dream. The open road. The smell of pine. The eternal struggle of trying to back a thirty-foot box into a spot that looks exactly like the one...
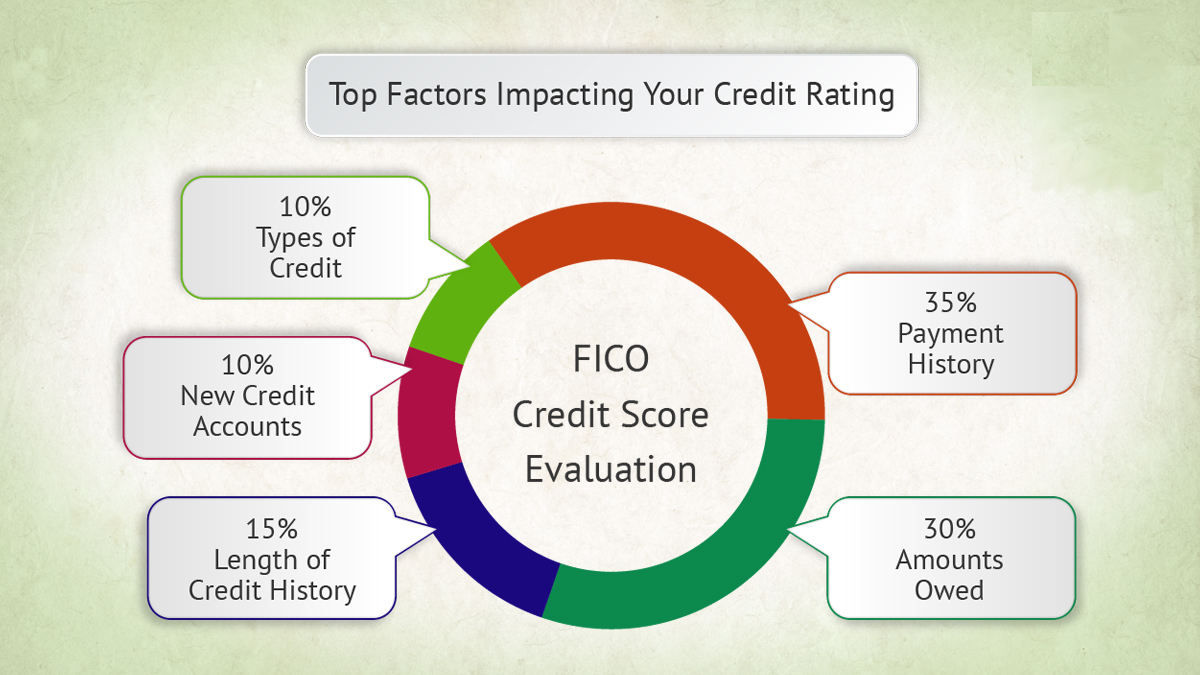
So, you’ve decided to embrace the dream. The open road. The smell of pine. The eternal struggle of trying to back a thirty-foot box into a spot that looks exactly like the one you just passed. You want a camper. But before you can channel your inner nomad, the bank wants to know one thing: what’s your credit score?
Let’s be real—your credit score feels like a report card for grown-ups, except you never studied for the test. It’s like trying to get a gold star for remembering to pay your phone bill while simultaneously forgetting you bought a vintage lamp on a whim. We’ve all been there.
Why a camper loan is like a first date
Think of applying for a camper loan as the financial equivalent of a first date. You show up, you try to look good on paper, and the lender squints at your history like they’re reading a menu in a dimly lit diner.
Must Read
If your score is shiny—say, over 740—you’re basically the prom king. Lenders will practically throw financing at you. They’ll offer low interest rates and sweet terms, like inviting you to the coolest campfire in town. You’ll walk out thinking, “Wow, I’m great at being an adult.”
But if your score is a little rough around the edges—maybe 600 or so—you’re the slightly awkward date who trips over the welcome mat. Suddenly, lenders are asking about your “debt-to-income ratio” and that one time you were late on a gym membership you swore you canceled in 2019.
The sneaky things that tank your score (and your camper dreams)
Remember that time you moved apartments and forgot to update your Netflix billing address? Your credit score remembers. It’s like an elephant with a grudge and an Excel spreadsheet. A missed credit card payment? Boom. A “hard inquiry” from a store card you opened for a 10% discount on throw pillows? Double boom.
Suddenly, your dream of sipping coffee in a tiny home on wheels turns into a lender saying, “We’ll need a larger down payment.” It’s like the universe is forcing you to actually save money. Rude, right?
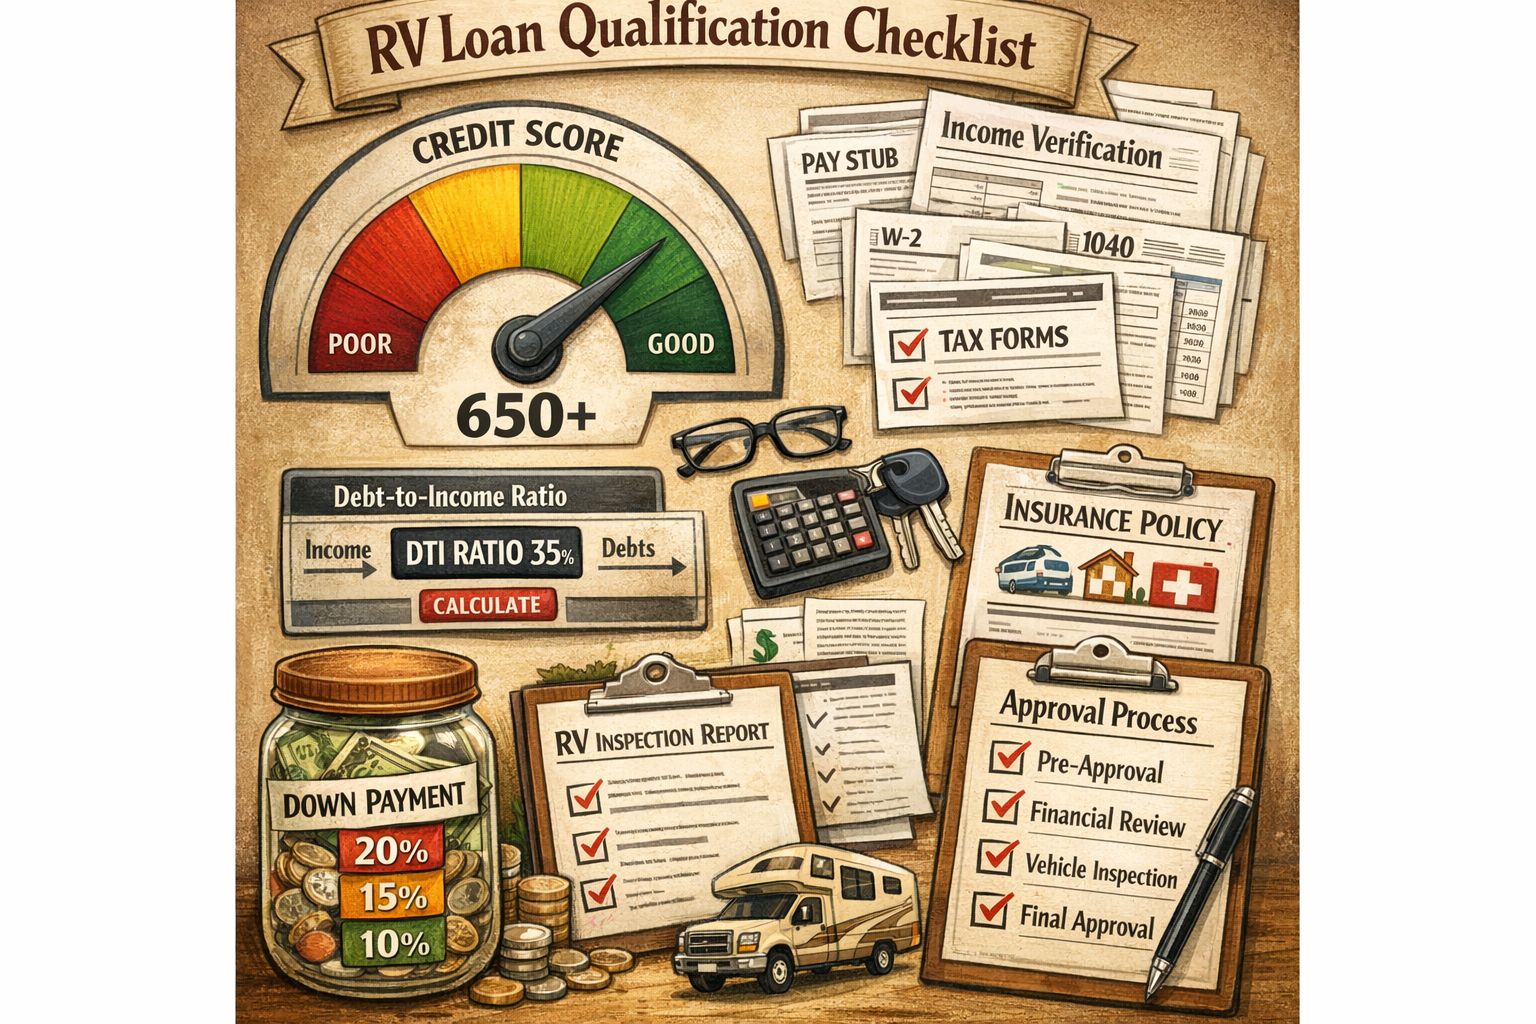 Can You Get a Mortgage on an RV? Complete 2026 Financing Gu
The FICO score vs. the camper fairy
There’s a myth that you need a perfect 850 to buy a camper. False. You don’t need to be a credit-card monk living on a mountain of pure financial virtue. Lenders for RVs and campers are often a bit more lenient than mortgage lenders. They know you’re not buying a house—you’re buying a very large, expensive tent that can drive.
If your score lands somewhere in the mid-600s, you might still get approved, but you’ll pay a higher interest rate. That’s the financial equivalent of “you can come to the party, but you have to bring a cooler.” And that cooler is money you could have spent on campfire snacks or new hiking boots.
I once met a guy named Dave who financed a 1988 Winnebago with a score of 620. He called it his “freedom machine.” He also called the interest rate “an apology for my twenties.” He paid an extra fifty bucks a month, but he spent every summer chasing sunsets. Was it worth it? He said yes, while eating a slice of gas-station pizza. Your mileage may vary.
How to “fluff up” your score before you shop
You don’t need to go full financial guru. Just do the basics. Pay your bills on time for three months in a row. That’s it. It’s like rolling a wet tent—annoying, but effective. Also, don’t open any new credit cards for six months before you apply for the camper loan. Lenders get nervous when they see you’ve suddenly become a credit-card collector.
 Which FICO Score Is Used for RV Loans: Understanding Credit Scores for
And for the love of campfires, check your credit report for mistakes. I found a collection notice on mine for a library book I returned in 2007. It was a battle, but I won. That little win bumped my score by 15 points. Fifteen points is the difference between a lender saying “hello” and saying “we’ll need a co-signer.”
The bottom line: it’s about the experience, not the number
Your credit score is just a tool. It’s not a judgment on your character. It’s a weird, grumpy algorithm that decides if you can buy a rolling tin can with a propane stove and a tiny sink. Don’t let a number stop you from living the camper life.
If your score is low, save a bigger down payment. If it’s high, enjoy your victory lap. Either way, someday you’ll be parked by a lake, listening to the rain on the roof, and you won’t care about the interest rate. You’ll just be glad you didn’t bring a tent.
And remember: even if your credit score is a disaster, you can still rent a camper for a weekend. You can pretend you’re a credit-score-free adventurer. It’s the best $200 you’ll ever spend—just don’t forget to return the camper without scratches. That could hurt your score. Or your dignity. Probably both.
