Ns&i Premium Bond Interest Rate Change

So, you’ve probably heard the news: NS&I just tweaked the Premium Bond interest rate again. And if you’re like me, your first thought was, “Wait, does this mean I’m finally go...

So, you’ve probably heard the news: NS&I just tweaked the Premium Bond interest rate again. And if you’re like me, your first thought was, “Wait, does this mean I’m finally going to win a million quid?” Probably not, but let’s dig into why this change is actually pretty cool.
The Big, Bold Number
The headline is that the prize fund rate has dropped from 4.4% to 4.0%. That’s a 0.4% cut, which in the world of bonds is like a gentle tap on the brakes—not a crash landing. But here’s the kicker: despite the drop, the odds of winning any single prize remain at 22,000 to 1.
Think of it like this: your £1 bond still has the same tiny, wonderful chance of striking gold. The change just means the pot of gold got a little smaller, so the big prizes—like the £100,000 and £50,000 ones—are being handed out a bit less often. Why is that interesting? Because it keeps the dream alive without totally flattening your expectations.
Must Read
Why Should You Care? (Spoiler: It’s Not Just About the Money)
Sure, a lower rate means you’ll earn less on average. But let’s be real: nobody buys Premium Bonds for the guaranteed return. You buy them for the thrill—the tiny dopamine hit every time you check your account and see that “Congratulations, you’ve won!” message.
It’s like having a lottery ticket that doesn’t expire, and it’s backed by the government. That’s a vibe. The interest rate change is just NS&I adjusting the dial so the game stays sustainable. Too high a rate, and they’d have to slash the odds or shrink the jackpots. Too low, and nobody buys them.
What Actually Changed? Let’s Get Nerdy for a Second
Here’s the math in plain English: the prize fund rate dropped by 0.4%, which means NS&I is putting a bit less money into the monthly prize pool. But they’ve redistributed that money to keep the smaller prizes (like £25, £50, and £100) flowing as steadily as possible.
 Income Bonds What Are Series I Savings Bonds? | The Motley Fool
So, you’re slightly less likely to snag a life-changing £1 million prize, but your chance of winning a nice little treat (a £25 win that feels like found money) is almost identical. It’s a trade-off, and honestly? It’s a clever one. Would you rather chase a unicorn or a reliable pony?
The Fun Comparison: It’s Like a Bumper Harvest
Imagine your Premium Bonds are an apple orchard. The interest rate is the total apple harvest each year. This year, the weather (the economy) isn’t as sunny, so the total crop is a bit smaller. But instead of letting every apple rot, NS&I is making sure the most common apples—the £25 ones—stay plump and juicy.
You still get to bite into a sweet apple every now and then, and the rare golden apple (the big prize) still exists. You just have to shake the tree a little longer. That’s not a bad deal, right?
So, Should You Keep Your Money In?
If you’re using Premium Bonds as an emergency fund or a safe place to park cash, this change is a gentle nudge—not a push. The average “prize rate” of 4.0% is still better than many easy-access savings accounts, and it’s tax-free.
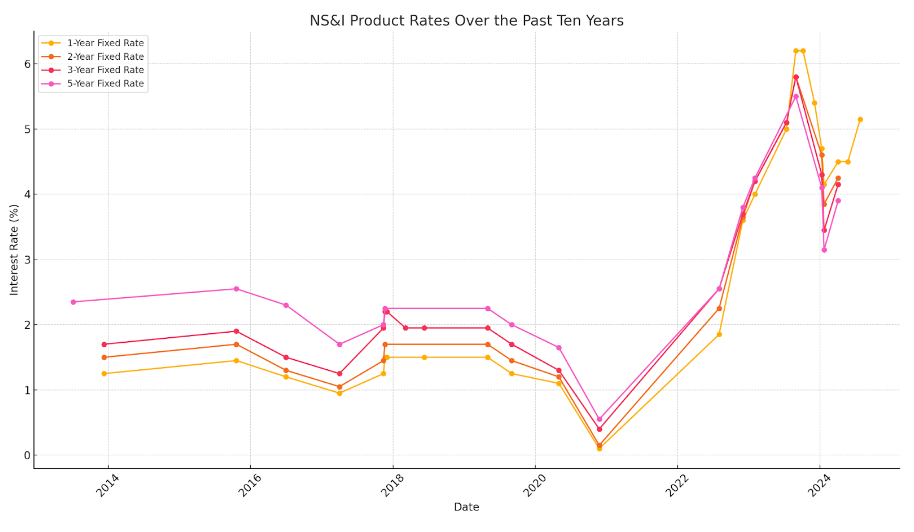
 What are the new NS&I interest rates? | Raisin UK
Plus, the real magic is the liquidity: you can pull your money out whenever you want. No penalties, no fees. It’s a savings account with a lottery ticket attached. And let’s be honest, how often do you get to daydream about winning £100,000 while also earning interest? That’s the cool part.
The Takeaway: Chill, But Stay Curious
This interest rate change isn’t a reason to panic. It’s a reason to pause and think: “Is this still working for me?” If you love the game—the monthly ritual of checking results, the quiet hope—then you’re fine. If you’re all about maxing out your guaranteed returns, maybe look elsewhere.
But here’s a final thought: NS&I is basically saying, “We’re keeping the dream alive, just a little slower.” And in a world where most things are boring and predictable, isn’t it nice to have a financial product that’s also a little bit of a mystery? Yeah, I think so too.
Now go check your bonds. Maybe today’s your lucky day.
