What's Next For Berkshire Hathaway After Warren Buffett's Historic Exit?

You know that feeling when you’re at a family reunion, and your super-smart, slightly intimidating Uncle Warren (the one who always knows which stock to pick) suddenly stands...

You know that feeling when you’re at a family reunion, and your super-smart, slightly intimidating Uncle Warren (the one who always knows which stock to pick) suddenly stands up and says, “Well, kids, I’m heading out for a smoke—forever”? That’s the vibe the financial world got when Warren Buffett officially passed the torch at Berkshire Hathaway. For decades, he was the Oracle of Omaha, the guy who turned a failing textile mill into a $900 billion monster. Now, he’s gone—and we’re all left staring at the buffet table wondering what’s for dessert.
Let me tell you a quick story. A few years ago, I overheard two guys at a coffee shop arguing about whether Berkshire was “just an index fund in a trench coat.” One said, “Buffett is the brand; without him, the stock tanks.” The other sipped his latte and retorted, “No way, the machine is built to outlive him.” Well, guess what? The machine just got its final pressure test—Buffett’s historic exit. So, what now? (Yeah, I’m asking you too.)
The Succession Plan Isn’t a Mystery—It’s Already Running
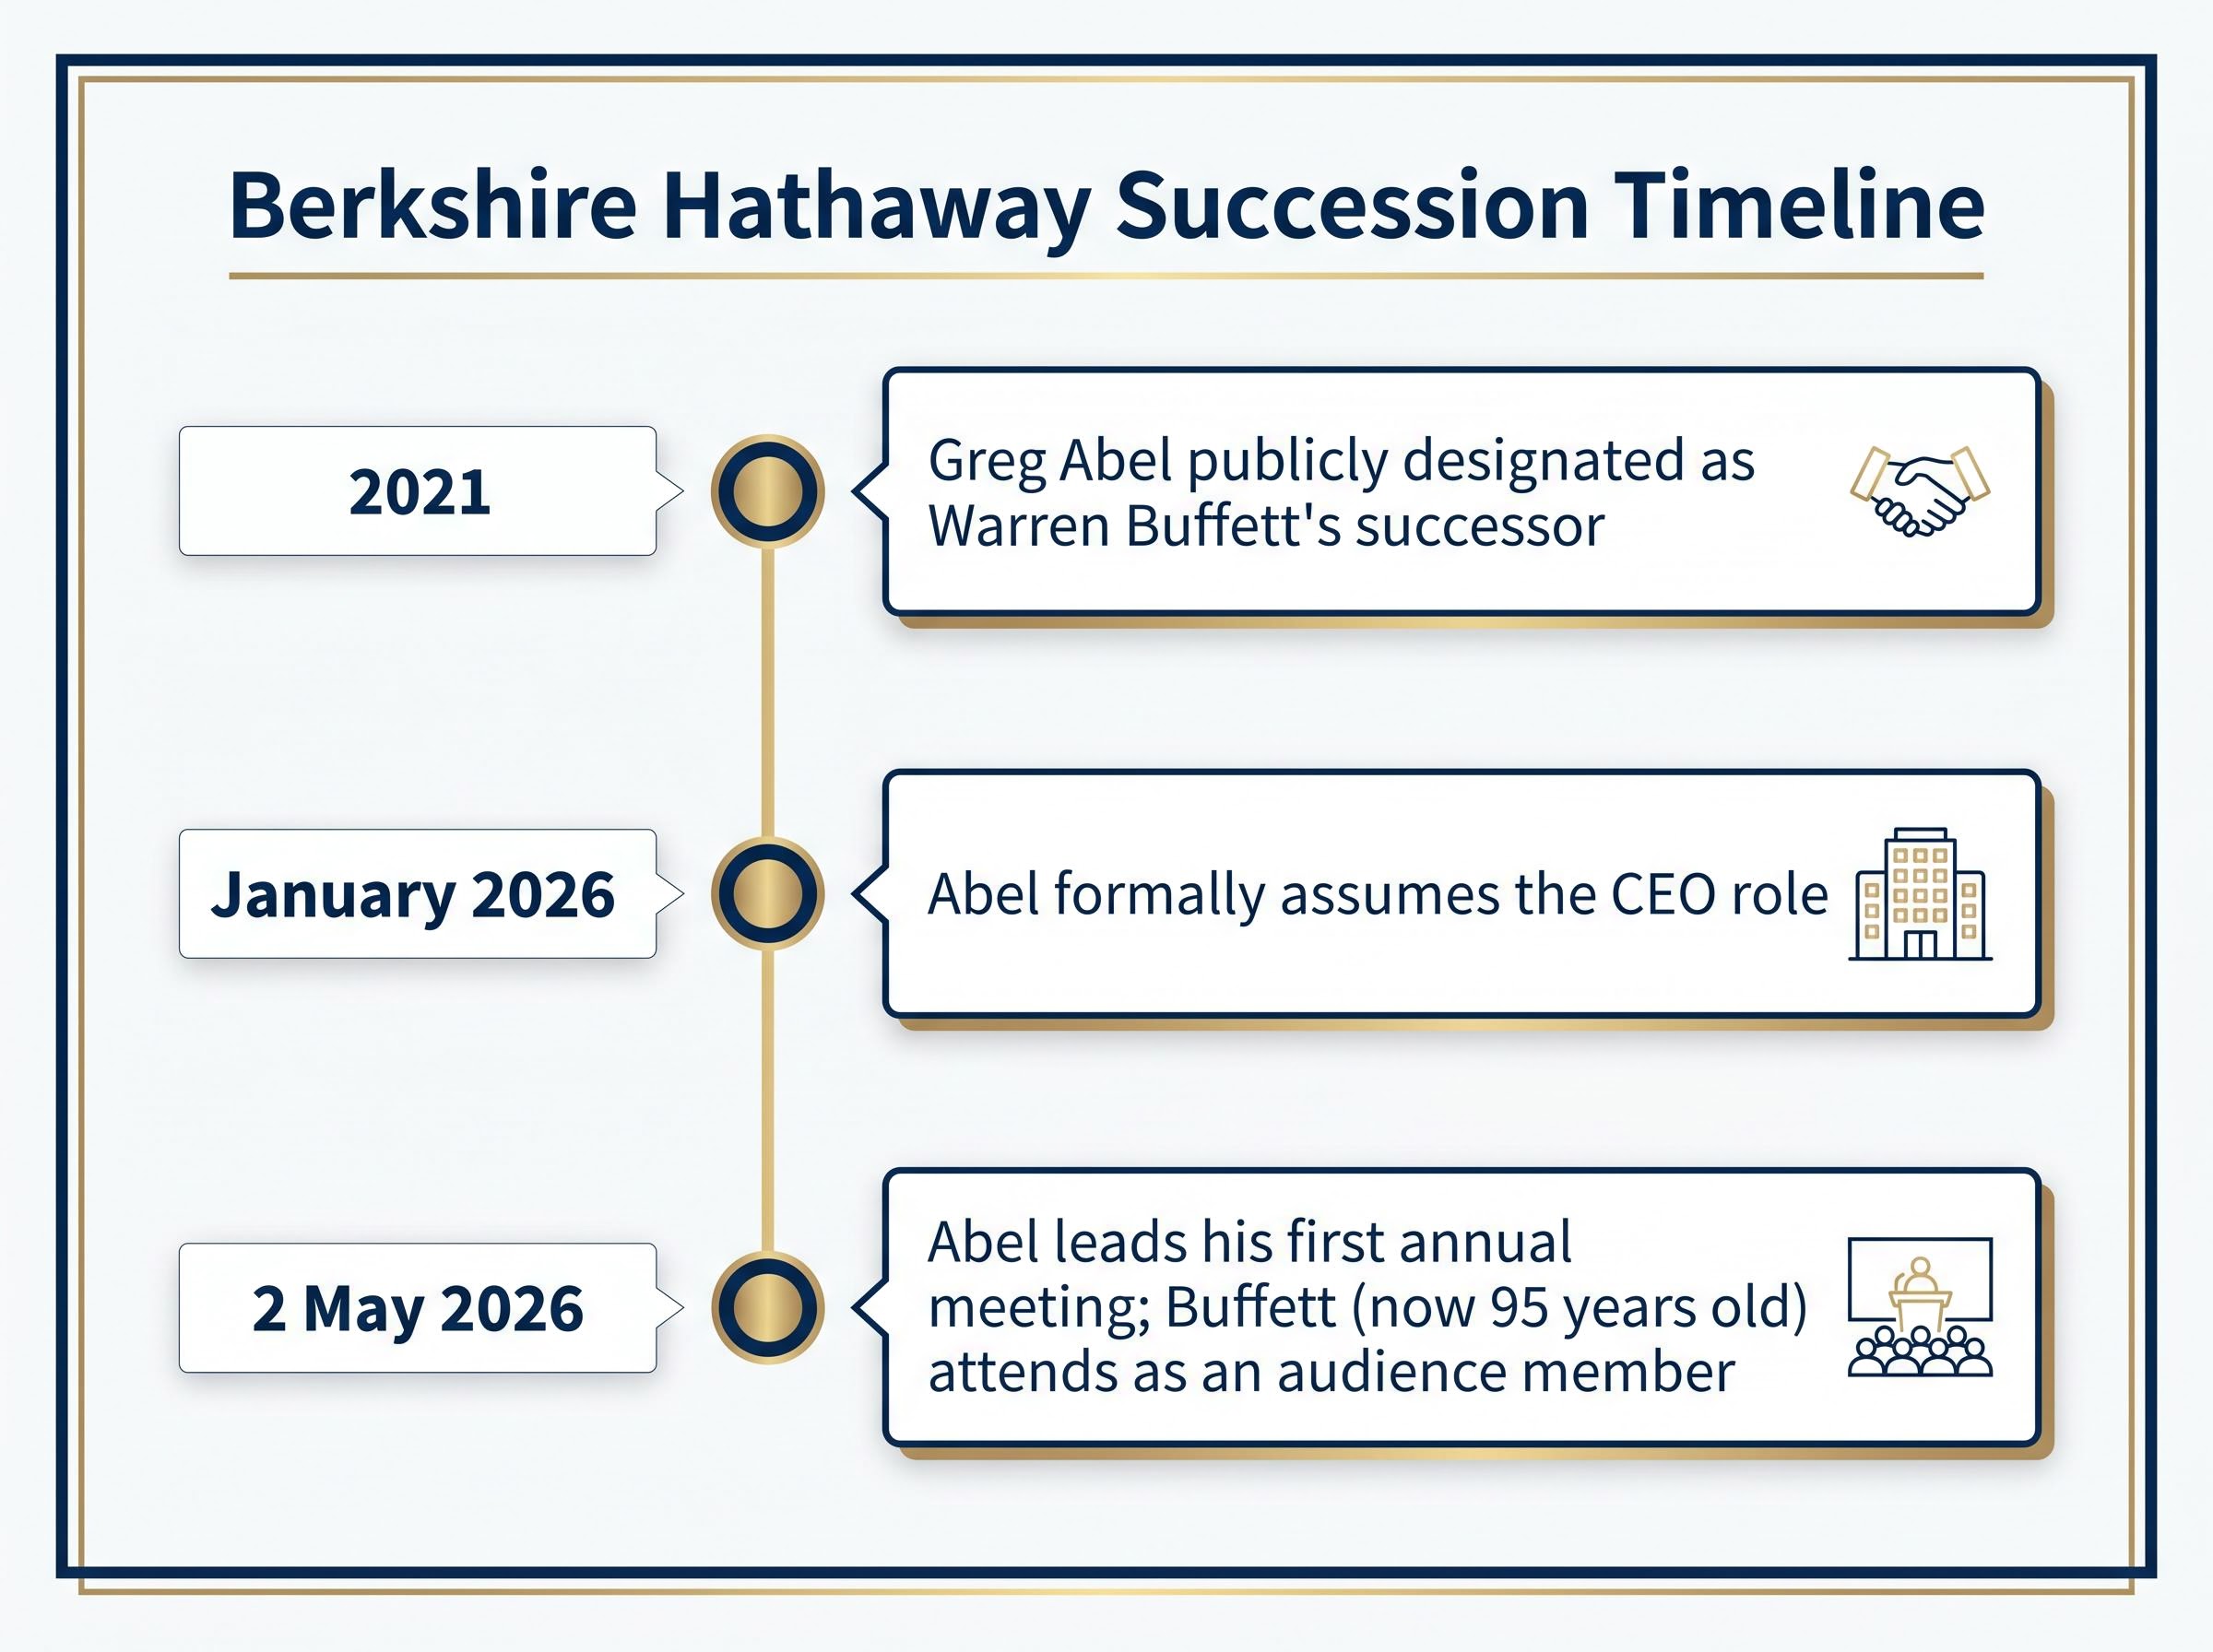
First, breathe. Berkshire isn’t a one-man show anymore—it hasn’t been for years. Buffett quietly handed the operational reins to Greg Abel (a no-nonsense Canadian who loves energy deals) and the investing side to Todd Combs and Ted Weschler (the guys who’ve been picking stocks behind the scenes since 2011). Think of it like this: Buffett was the architect who drew the blueprint, but the builders have been hammering nails for a decade. The real question isn’t who will run it, but how they’ll run it.
Must Read
Let’s be honest—the biggest fear is that Berkshire loses its magic mojo. You know, that contrarian instinct to buy when everyone else is selling, like when Buffett snapped up Goldman Sachs during the 2008 panic. Greg Abel isn’t a charismatic quote-machine; he’s a numbers guy who once said, “I’d rather earn a decent return on a great business than a great return on a decent one.” (Translation: He’s boring in the best way.) So, expect fewer “cigar butt” investments and more boring—but steady—utility and railroad profits.
Cash: The Elephant (or the $300 Billion Piggy Bank) in the Room
Here’s where it gets deliciously ironic. Berkshire is sitting on a record $325 billion cash pile (yes, that’s billion with a B). Under Buffett, that cash was like a dragon hoarding gold—waiting for a “fat pitch” like a market crash. But Abel and the team? They might start buying growth stocks or even (gasp!) paying a dividend. Can you imagine? A Berkshire dividend would be like your grandpa suddenly sending you a Venmo—surprising, but kind of awesome.
 Warren Buffett Retires: Berkshire’s Next Move Could Shake Markets
But here’s the catch: without Buffett’s golden reputation, Berkshire’s stock might lose its “trust premium.” (You know, the reason people paid 1.5x book value for decades.) If Abel makes a single dumb deal—like buying a failing tech unicorn—the market will punish them harder than it ever punished Buffett. The new leaders have zero margin for error. Zero.
The Real Wildcard: Will Berkshire Become a Different Beast?
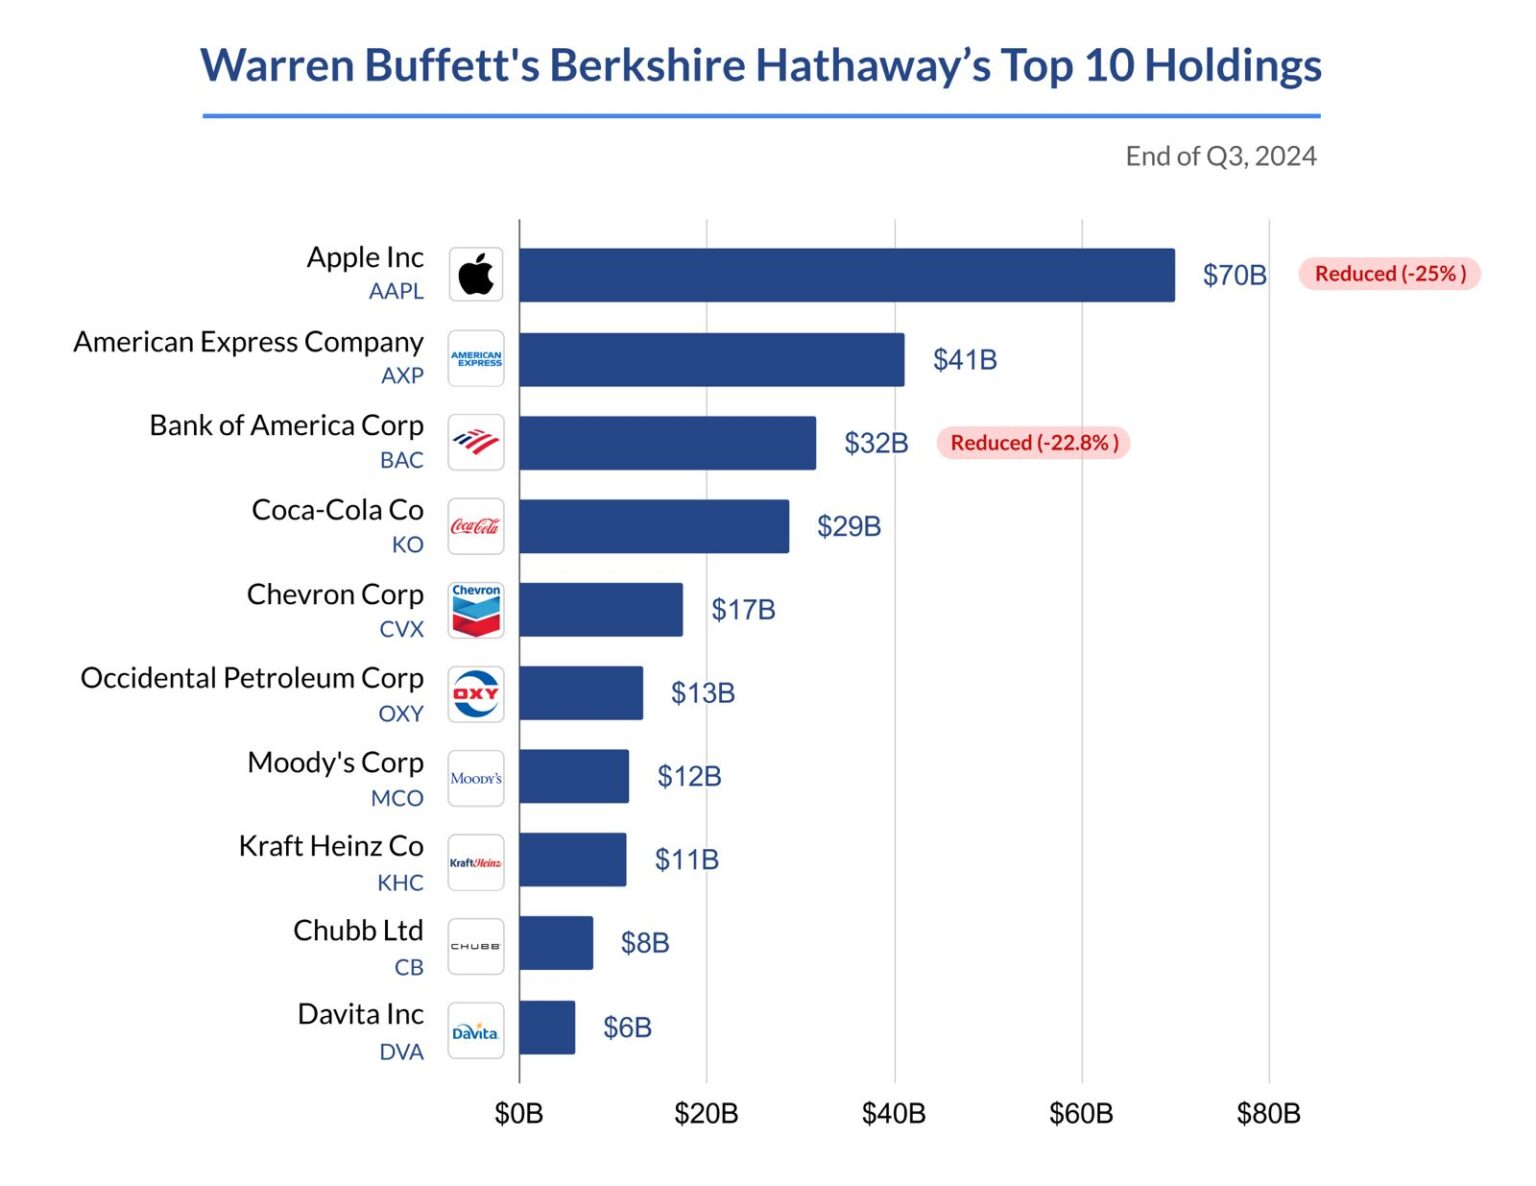
I think the most exciting (or terrifying) change is strategy drift. Buffett hated tech stocks—he called them “too hard” and famously passed on Amazon and Google. But Abel and Combs are younger, and they’ve already invested in Snowflake and a few fintech plays. Watch for Berkshire to quietly buy into AI or renewable energy startups—while still keeping a massive stake in Coca-Cola, because some things are sacred.
 Berkshire After Buffett: What Greg Abel's CEO Era Reveals
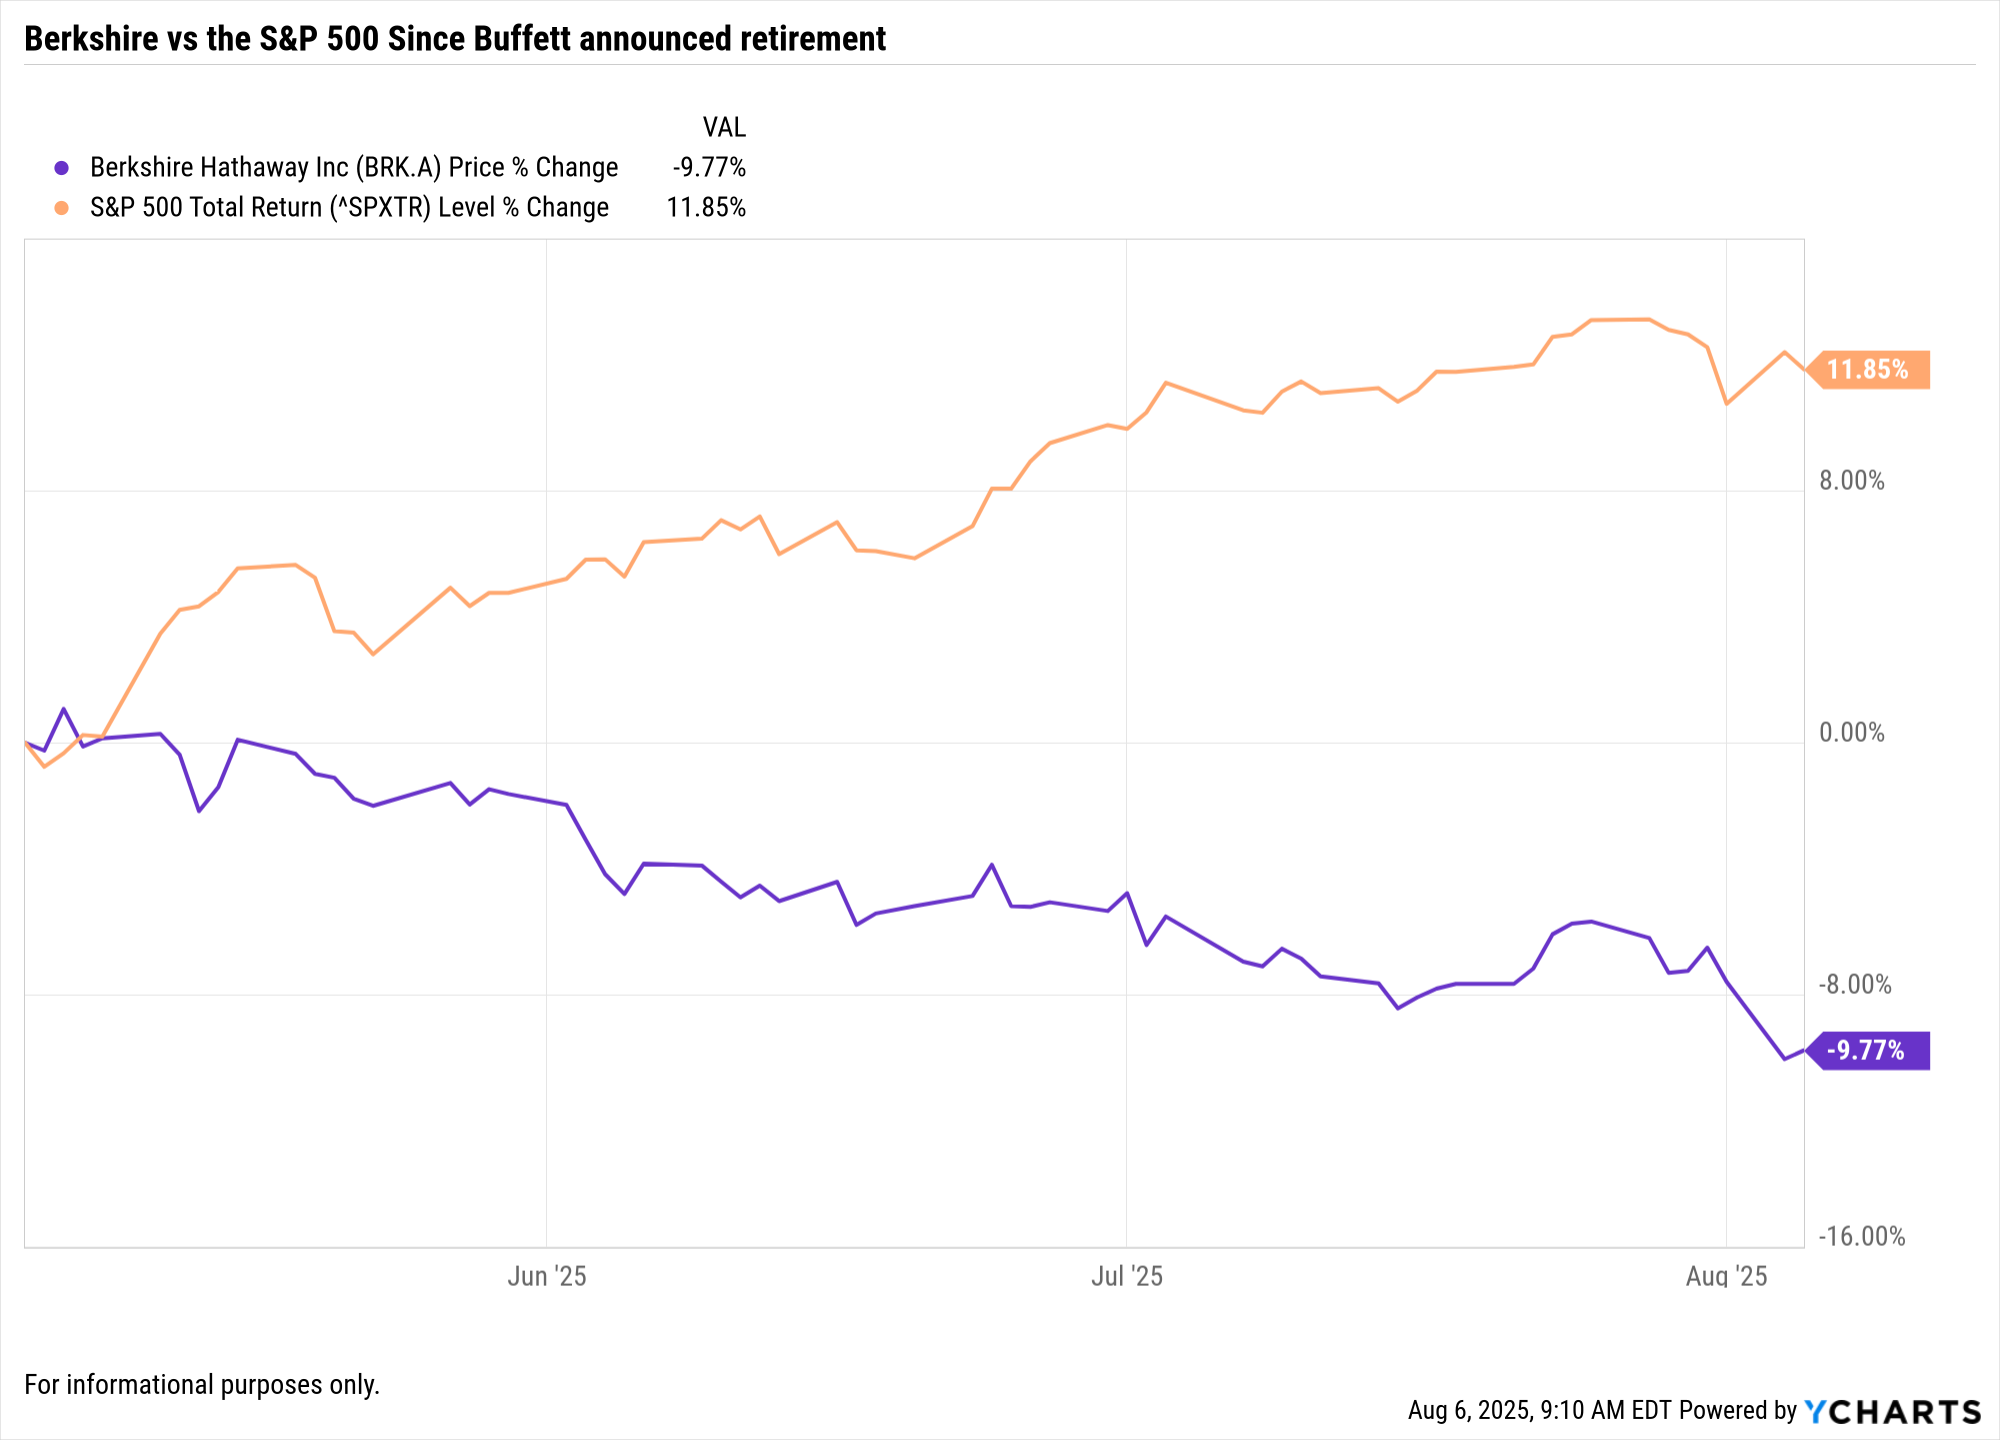
Also, expect more share buybacks. Under Buffett, buybacks were done when the stock was “obviously cheap,” which was rare. The new guard might be more aggressive, especially if the stock dips after the transition. (Hint: if Berkshire’s price drops 10% tomorrow, don’t panic—that’s a buying signal for the new team.)
The Final Verdict: Boring Is the New Exciting
Here’s my hot take: Berkshire Hathaway without Buffett is like The Beatles without John Lennon—still a great band, but the vibe changes. You’ll get fewer “Buffett-isms” (like “be fearful when others are greedy”) and more spreadsheets. But that’s not a bad thing. The business engine—GEICO, BNSF Railway, See’s Candies—is a cash-spewing machine that doesn’t need a CEO who buys newspapers for fun.
 What will become of Berkshire Hathaway now that Warren Buffett is
For investors, the next decade is about patience. Don’t expect 20% annual returns. Do expect slow, compound growth, maybe 8-10% a year. And if you’re nervous? Well, remember that the Oracle himself picked his successors. He once wrote, “The right people are in charge, and they’ll make the right decisions.” So, grab a Cherry Coke, read the annual report, and trust the process. (But maybe ignore the first quarterly letter after his exit—it’ll be very long and very dry.)
One last thing: keep an eye on insurance. Berkshire’s float (the money from premiums they hold) is its secret sauce. If Abel uses that float to take bigger risks in reinsurance or catastrophe bonds, you’ll see volatility. If he plays it safe, the stock becomes a cozy dividend utility. My money? On a bit of both—because nothing is ever simple in Omaha.