Cual Es El.codigo De Seguridad De Una Tarjeta De Debito

So, picture this: my buddy Dave is at a taco stand, phone in one hand, wallet in the other. He’s trying to order online, but the page keeps asking for that three-digit number...

So, picture this: my buddy Dave is at a taco stand, phone in one hand, wallet in the other. He’s trying to order online, but the page keeps asking for that three-digit number on his card. He stares at the back, squints, and mutters, “Is it the one with the shiny hologram?” I almost choked on my salsa.
We’ve all been there, right? That tiny, annoying code that feels like a secret handshake between you and your bank. It’s not exactly a spy thriller, but it is a major key to keeping your cash safe. Let’s crack that mystery wide open.
So, What Is This Magic Number?
In English, we call it the CVV, which stands for Card Verification Value. Fancy term for a simple thing. It’s that three-digit code on the back of your debit card, printed right next to the signature strip.
Must Read
Sometimes it’s four digits on a credit card, but for your standard debit card, expect three. Think of it as your card’s short, secret password for online and phone purchases.
And no, it’s not the same as your PIN. Your PIN is for the ATM or the store’s card reader. This little code is strictly for when you’re not physically holding the card out.
Why Does It Even Exist? (Or: The Superhero Origin Story)
The CVV was invented to stop people from stealing your card number and going on a shopping spree. Imagine you write your card number on a napkin, someone snaps a photo—if they also got the CVV, they’d be dangerous. So banks put that code in a separate, sneaky place.
They encode it on the magnetic stripe but with a twist: it’s calculated using a secret algorithm. If a hacker steals the number from a database but not the physical card, the code is useless. Clever, right?
Fun irony: some websites try to make you feel safe by asking for it. But if you’re on a shady site giving them that code, you’re basically handing them the keys. (Look at you, getting paranoid—good.)
Where the Heck Do I Find It?
Turn your debit card over. See that long, black magnetic strip? Don’t stare at that. Look to the right of the signature panel. That little white box has your CVV printed in it.
For cards from Visa, Mastercard, and Discover, it’s always three digits. American Express is the oddball—four digits on the front above the account number. But since you asked about debit, you’re likely in the three-digit club.
If your card has a shiny hologram sticker covering it, gently scratch it off (like a lottery ticket, but less exciting). It’s there, I promise.
The Golden Rule: Never, Ever Share It… Except When You Should?
Here’s the kicker: you should never give out your CVV to someone calling you. No bank, no “security department” from Visa, no Nigerian prince. They don’t need it. Ever.
But yes, you’ll have to type it into websites and maybe read it over the phone to a store you trust. The key word is trust. If you feel a tingle of weirdness, hang up and lock your card.
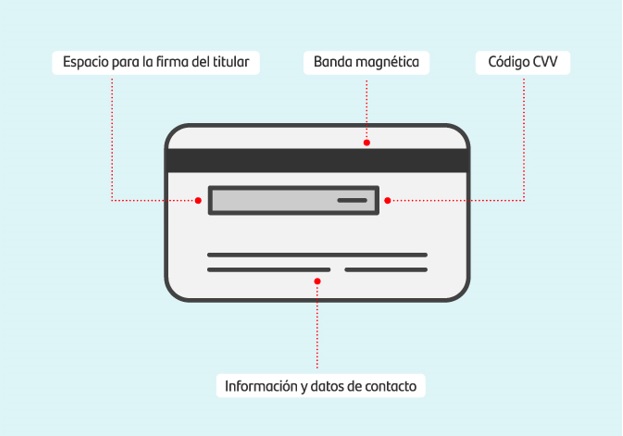 ¿Qué es el CVV de una tarjeta bancaria?
Oh, and don’t store it in your notes app labeled “secret debit code.” That’s like leaving your house key under a doormat that says “key here.” Just… don’t.
What If Someone Steals It? (Don’t Panic—Yet)
If you lose your card, or you get a weird notification from a random app, act fast. Call your bank immediately. They’ll cancel the card and send a new one with a brand-new CVV.
Most debit cards have zero liability protection if you report fraud quickly. But some banks are slow, so check your app daily. That tiny code is the gatekeeper; if it’s compromised, you lose.
Pro tip: if a website asks for your CVV and then says “store this card for later,” think twice. If that site gets hacked, your CVV is toast. Better to type it fresh each time, like a ritual.
The One Exception That Drives Everyone Nuts
Ever tried buying something and the site don’t ask for the CVV? Like Netflix or Amazon? That’s because they use a different system—tokenization. They don’t store your actual CVV; they get a special code from your bank.
Annoying reality: some legitimate online stores won’t ask for it for small purchases. That doesn’t mean it’s fake. But if a site asking for $200 doesn’t request a CVV, that’s a red flag.
Bottom line: if the code is optional, proceed with caution. If it’s mandatory, you’re protected.
Final Weird Thought: Why “Security” When It’s Right There?
Isn’t it a little silly that your “secret” code is printed on a card anyone can glance at? Yeah, it’s not perfect. That’s why banks also use two-factor authentication, texts, and app approvals. The CVV is just one layer.
Think of it as a speed bump, not a fortress. It slows down casual thieves but won’t stop a determined hacker. So pair it with common sense: don’t hand your card to a stranger to “read the back.”
If you’re still stressing, just memorize it. I have mine tattooed in my brain—okay, not literally, but I remember it like my birthday. Now you can, too. And hey, if Dave can figure it out, you definitely can. Go forth and tacofy safely.
