Financial Planning For High Net Worth Individuals
So, you’ve got a few more commas in your bank account than the rest of us. Congratulations! You’re officially a High Net Worth Individual, or as I like to call you, someone wh...
So, you’ve got a few more commas in your bank account than the rest of us. Congratulations! You’re officially a High Net Worth Individual, or as I like to call you, someone who accidentally bought a yacht while shopping for a kayak. But here’s the twist: having a pile of cash doesn’t mean you’re safe from stupid money mistakes. In fact, the bigger the pile, the more creative your disasters can be.
The Joy (and Horror) of Too Much Money
Let’s be honest: being rich sounds like a dream, but it’s actually a full-time job of keeping your money from running away with itself. You think inflation is annoying when you’re buying bread? Try watching a private jet depreciate faster than your teenager’s attention span. The secret truth is that high net worth financial planning is 50% strategy and 50% panic prevention.
Here’s a surprising fact: most millionaires lose more money to bad advice than to bad investments. You’ll meet “wealth managers” who talk faster than a used car salesman and dress like they’re auditioning for a James Bond villain. Approach them with the same suspicion you’d give a raccoon offering to hold your picnic basket.
Must Read
Taxes: The Uninvited Dinner Guest
If you’re wealthy, taxes don’t just show up—they move into your guest house and redecorate. The joke is that you can either pay taxes or fight them, but fighting costs even more. Smart planners use trusts, charitable donations, and something called “tax-loss harvesting,” which sounds like farming but is really just selling losers to annoy the IRS.
One trick: give money to a Donor Advised Fund. It’s like a charity piggy bank that makes you look like a saint while shrinking your tax bill. Plus, your friends will say, “Oh, you’re so philanthropic!” while you’re secretly thinking, “I just saved enough for a second helicopter.”
Insurance: The Boring Superhero
Everyone loves talking about stocks and real estate, but nobody wants to discuss insurance. It’s the broccoli of finance. But for the wealthy, it’s the broccoli that stops a lawsuit from eating your entire organic farm. You’ll need “umbrella policies” that cover you when your luxury car accidentally drives into a gallery of priceless art.
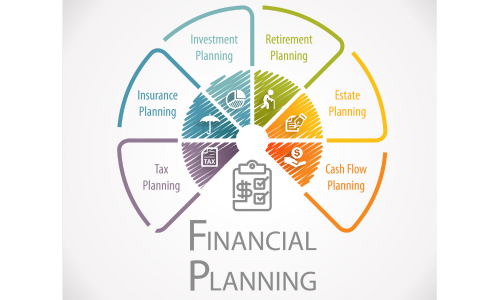
 Financial Planning Ideas for High Net Worth Individuals — IntelliVest
And yes, you can insure your hands if you’re a pianist, or your voice if you’re a singer. But if you’re just a regular rich person who trips over their own cash, get liability insurance. Trust me—your next über-wealthy neighbor’s dog does not care about your feelings, only your assets.
Investing: Don’t Try to Be a Genius
Here’s the most boring but true advice: stop trying to double your money in a year. You know who tries that? People who want to become poor quickly. High net worth individuals invest like they’re building a hill, not a skyscraper. Diversification is the fancy word for “don’t put all your caviar in one bowl.”
A shocking fact: many ultra-wealthy families have 60% or more of their portfolio in boring things like bonds, real estate, and private equity. They don’t chase Bitcoin because they’re too busy buying entire forests. Seriously, owning a forest is a status symbol because it grows, absorbs carbon, and nobody can build a parking lot on it during your lifetime.
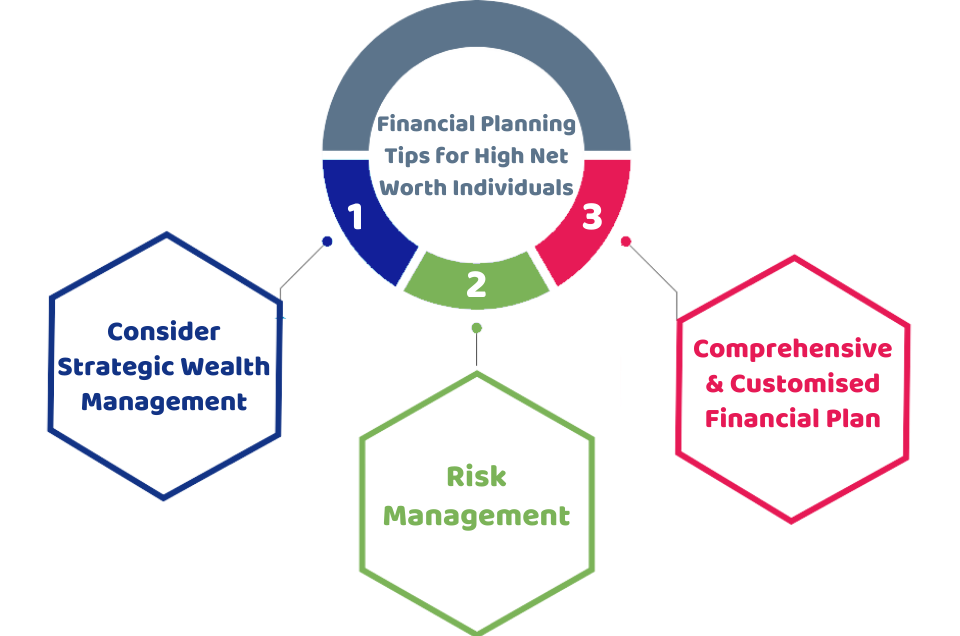 Tips for High Net Worth Individuals | Basic Guidelines - CruseBurke
The Family Office: Like a Butler for Your Money
When you have so much money that managing it becomes a circus, you start a “Family Office.” This is a team of accountants, lawyers, and therapists (yes, therapists) whose only job is to keep your family from suing each other over a vacation home in Monaco. Family offices are the ultimate flex—they’re proof you’re too rich to handle your own life.
The surprising part? These offices often cost more than your childhood home. But they’re worth it because they prevent your cousin Gary from “investing” the inheritance in a glow-in-the-dark llama farm. Family Offices: because even rich people need a referee.
The Golden Rule: Don’t Be the Punchline
In the end, financial planning for the rich is about not becoming a cautionary tale. You’ve seen the headlines: lottery winners who lose it all, actors who end up broke, tech founders who buy islands that sink. Don’t be those people. Be the rich person who quietly pays the bill and leaves a tip that funds someone’s vacation.
Here’s the last fact: the wealthiest 1% of families have an average of seven different advisors. That’s more than the number of friends they have from college. But hey, if you can afford seven people to tell you “don’t do that, you idiot,” you’re already ahead. So laugh, diversify, and for heaven’s sake, don’t buy that llama farm. Your grandchildren will thank you.
